
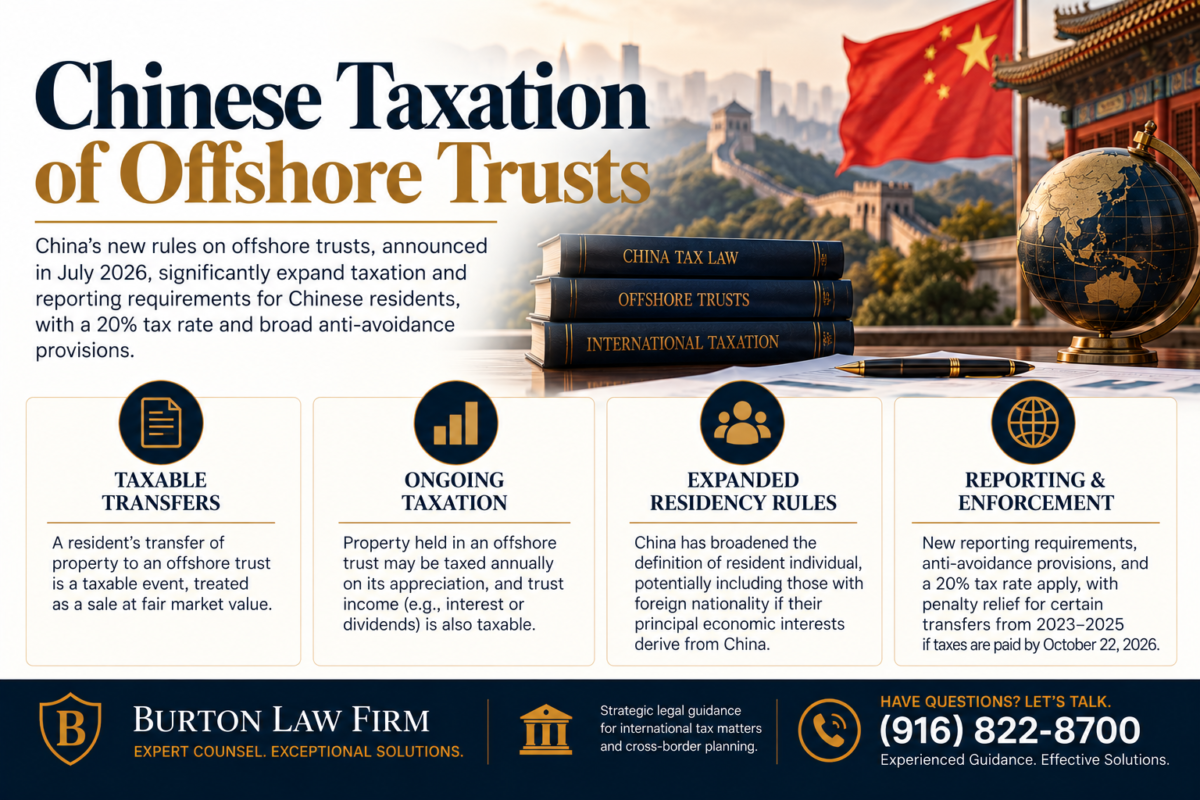
Chinese residents are taxed on their worldwide income by China. Nonresidents are taxed by China only on income sourced to China. Offshore trusts have become a popular means amongst wealthy Chinese to avoid the income tax. On July 24, 2026, China suddenly announced new rules for offshore trusts to stop this avoidance. These came in the form of Announcement 15 and Announcement 21 by the State Taxation Administration.[1] Announcement 21 provides most of the substantive rules, while Announcement 15 is primarily concerned with reporting obligations. These are short documents. Announcement 21 is only 5 pages long, while Announcement 15 is only 4 pages long.
In general, a resident’s transfer of property to an offshore trust is a taxable event as if it were sold for fair market value. For each year that the property is in an offshore trust under the resident’s control, the property is taxed on its appreciation, even if it was not sold or distributed. “Losses may not be carried forward to offset income in subsequent years.”[2] Any income from the offshore trust property, such as interest or dividends, is also taxed. If the offshore trust property is distributed to a resident, the resident must pay a tax on the property’s value to the extent such value was not already taxed by the trust grantor. If the resident becomes a nonresident, the property is taxed as if it were sold. If more than one resident contributes property to an offshore trust, each resident is taxed on the proportionate share of the property they contributed to the entirety of the offshore trust’s property. A nonresident’s transfer of property to an offshore trust is taxed only to the extent that the property is sourced to China. The tax rate is 20% throughout this process.
An “offshore trust” is defined as “a trust or other legal arrangement having trust functions established under the laws of a jurisdiction outside China.”[3] However, this definition “excludes financial products issued by banks, insurance companies, securities companies, fund companies, and similar institutions that are regulated by the financial regulatory authorities of the countries or regions in which they are located and that independently conduct business with an unspecified clientele and bear the associated risks.”[4] A transfer to an offshore trust is taxed on “the property’s market value, less its original value and reasonable expenses.”[5] The term “reasonable expenses” is undefined. Indirect transfers are also included in these rules. “Where an individual transfers property through another individual or organization, and the individual actually funds, bears the cost of, and controls that property, the individual shall be deemed to have acquired and contributed the property.”[6] Notably, the term “controls” is undefined. However, “[w]here an offshore trust to which a nonresident individual has contributed property distributes income to a nonresident individual, but another resident individual actually receives, uses, controls, or disposes of that income, the offshore trust shall be deemed to have distributed the income to that resident individual.”[7] China expanded the category of residents for these purposes. “An individual who has acquired foreign nationality or long-term or permanent residence rights outside China, but whose principal economic interests derive from within China, may be determined to be a resident individual domiciled in China.”[8]
These announcements are retroactive to an unknown degree. Although they claim to be effective immediately (July 24, 2026), there is a provision waiving penalties for unpaid tax liabilities arising from these new rules from transfers to offshore trusts from January 1, 2023, to December 31, 2025, if paid by October 22, 2026. The announcements are technically interpretations of existing law rather than the proclamation of a new law. It is theoretically possible that these rules apply to offshore trust transfers before 2023.
Separately, China announced that it “will impose a 20 percent individual income tax on dividends and bonuses that foreign individuals receive from foreign-invested enterprises starting September 1.” The “temporary exemption” in place since 1994 is now over.
[1] Unfortunately, neither of them appears to have an official English translation.
[2] Announcement No. 21, § 4(unofficial translation).
[3] Id. at § 1(unofficial translation).
[4] Id.(unofficial translation).
[5] Id. at § 4(unofficial translation).
[6] Id. at § 2(unofficial translation).
[7] Id. at § 8(unofficial translation).
[8] Id. at § 11(unofficial translation).