Expert Counsel. Exceptional Solutions.

+1 (916) 822-8700

Categories
News

Federal Circuit Gives Little Credit to the Treaty’s Foreign Tax Credit

Introduction

U.S. citizens are generally taxed on worldwide income. To alleviate double taxation, the Internal Revenue Code (IRC) offers a credit for foreign taxes paid. Tax treaties with the U.S. usually provide for a foreign tax credit as well. Estate of Bruyea v. United States and Christensen v. United States discuss the relationship between these two credits in the context of the Canadian tax treaty and the French tax treaty. Both cases were decided by the same panel of the Federal Circuit and were written by Judge Leonard Stark. Ultimately, the foreign tax credit offered by that treaty cannot surpass the limitations imposed by the Internal Revenue Code, according to the Federal Circuit. One limit is the exemption of the Net Investment Income Tax (NIIT) of 3.8% from the foreign tax credit’s scope. Section 27 of the IRC states in full and without a period at the end: “The amount of taxes imposed by foreign countries and possessions of the United States shall be allowed as a credit against the tax imposed by this chapter to the extent provided in section 901”.[1] In turn, section 901 also applies the FTC to “the tax imposed by this chapter.” Both sections are in Chapter 1, but the NIIT is in Chapter 2A.[2]

The Health Care and Education Reconciliation Act of 2010 created the NIIT decades after the French and Canadian treaties were written.[3] According to the Government Publishing Office, that legislation is 55 pages. The congressional report is divided into two volumes.[4] The first is 902 pages, and the second is 445 pages long. Neither mentions the NIIT.

The Disputed Language

The pertinent treaty language is:[5]

In the case of the United States, subject to the provisions of paragraphs 4, 5 and 6, double taxation shall be avoided as follows: In accordance with the provisions and subject to the limitations of the law of the United States (as it may be amended from time to time without changing the general principle hereof), the United States shall allow to a citizen or resident of the United States… as a credit against the United States tax on income the appropriate amount of income tax paid or accrued to Canada…

Where a United States citizen is a resident of Canada, the following rules shall apply… For the purposes of computing the United States tax, the United States shall allow as a credit against United States tax the income tax paid or accrued to Canada after the deduction referred to in subparagraph (a). The credit so allowed shall not reduce that portion of the United States tax that is deductible from Canadian tax in accordance with subparagraph (a).

This was parsed by the Federal Circuit through five clauses it numbered:[6]

[1] the “Avoidance Clause” (“subject to the provisions of paragraphs 4, 5, and 6, double taxation shall be avoided”);

[2] the “U.S. Law Limitation” (“In accordance with the provisions and subject to the limitations of the law of the United States (as it may be amended from time to time . . .)”);

[3] the “General Principle Clause,” which modifies the U.S. Law Limitation by providing that any post-Convention amendments to U.S. tax laws will not “chang[e] the general principle hereof;”

[4] the “paragraph 1 Credit Clause” (“the United States shall allow to a citizen . . . of the United States . . . as a credit against the United States tax on income the appropriate amount of income tax paid or accrued to Canada”); and

[5] a similar “paragraph 4(b) Credit Clause,” specifically available to “a United States citizen [who] is a resident of Canada” (“the United States shall allow as a credit against United States tax the income tax paid or accrued to Canada”).

Thus, the purpose is double taxation avoidance. There are two clauses allowing for a credit based on the tax paid to Canada. The first is paired with language subordinating it to U.S. law. This limitation is itself restricted. The “general principle” of the treaty remains unchanged. The second credit clause is three paragraphs away in the context of a U.S. citizen residing in Canada. Such a person is entitled to a credit after the application of Canada’s own version of the foreign tax credit, a deduction. However, the U.S. credit cannot reduce the tax for which the Canadian deduction applied.

Bruyea Analysis

The credit applies to the “United States tax,” which is broadly defined as the court explained in Bruyea: “Article II adds that the treaty ‘appl[ies] to taxes on income . . . imposed on behalf of [Canada and the United States], irrespective of the manner in which they are levied,’ including to “the Federal income taxes imposed by the Internal Revenue Code’ and ‘[a]ny taxes identical or substantially similar to those taxes’ that are added to the Code in the future.”[7] However, “just because the § 1411 [NIIT] is a ‘covered’ tax under Article II(3) of the Treaty does not mean that Article XXIV(1) authorizes a credit to offset that tax.”[8] This “is the start of the analysis, not its conclusion.”[9]

Despite being an “interpretive puzzle,” the Federal Court held that the solution is straightforward because the treaty version of the foreign tax credit is explicitly subject to the IRC.[10] The happenstance that the exclusion is due solely to the inclusion of NIIT in chapter 2A instead of chapter 1 is irrelevant. “[W]e conclude that the placement of the NIIT in chapter 2A, in view of Congress’ presumed knowledge that the Code only authorizes foreign tax credits to apply against chapter 1 taxes, constitutes an intentional decision to exclude the NIIT from the offset regime.”[11] The Court of Federal Claims held that this changed the “general principle.” In contrast, the Federal Circuit argued that “[t]here is no indication, in the Convention or elsewhere, that the creation of a single new type of income tax, and Congress’ determination not to make that tax eligible for a foreign tax credit, violates the General Principle Clause and its broad goal of reducing double taxation.”[12] The taxpayer “fails to persuade us that the adoption of the NIIT, subsequent to execution of the Convention, combined with the NIIT’s ineligibility under the Code for offset by a foreign tax credit, runs afoul of this general principle. The Convention does not entirely ‘eliminate’ double taxation; as the Avoidance Clause states, its ambition is only that ‘double taxation shall be avoided.’”[13] The court quoted the treaty provision that the two countries “may also consult together for the elimination of double taxation in cases not provided for in the Convention,” to suggest that the elimination of double taxation was not truly the treaty’s intention.[14] The title of the relevant treaty article is “Elimination of Double Taxation.” The Federal Circuit further suggested that even if the NIIT violated the treaty, the remedy is such “sovereign-to-sovereign relief.”[15] There is not any indication within the treaty that this is the exclusive remedy.

Perhaps the primary rationale for the Court of Federal Claims’ holding that the treaty version of the credit applies to the NIIT is that its subordination to the IRC would make the treaty credit superfluous. What is the point of the treaty credit if it is the same as the IRC credit? The Federal Circuit had an answer. “[G]enerally, a U.S. citizen cannot take a foreign tax credit on U.S.-source income.”[16] However, the treaty created an exception to this rule not found in the IRC. The Federal Circuit cited this phenomenon as proof that the treaty foreign tax credit is not independent. If it were, the court argued, this would be “superfluous.”[17] The court also pointed to the explicit inclusion of the accumulated earnings tax and the personal holding company tax (each otherwise excluded from the foreign tax credit’s scope) as “show[ing] that when the treaty drafters intended for the Convention to alter the Code’s default treatment of a category of credit-excepted taxes (like the NIIT), they said so explicitly.”[18]

The Federal Circuit further argued that adopting the taxpayer’s interpretation “would yield anomalous results” which “are to be avoided if at all possible.”[19] As discussed, there are two credit clauses. The general credit clause is paired with the U.S. Law Limitation clause, but the credit clause specific to U.S. citizens residing in Canada is not explicitly connected with the U.S. Law Limitation clause. To the court, the taxpayer’s interpretation would favor U.S. citizens residing in Canada. “We have no basis to conclude that the parties to the Convention intended these anomalous results of treating U.S. citizens living in Canada better than their similarly-situated counterparts living in the U.S.”[20] Nevertheless, the credit clause applicable only to U.S. citizens living in Canada remains. If it does not provide different treatment (which presumably can only be favorable), it is unclear what the purpose or function of this clause is. The court did not provide any suggestions.

Extrinsic Evidence

The trial court and the taxpayer argued that the U.S. Law Limitation is “restricted to computation-related ‘provisions’ and ‘limitations’ of the Code.”[21] This derives from extrinsic evidence, such as the treaty’s technical explanation contemporaneously written by the Treasury Department. The Federal Circuit doubted this evidence, but disclaimed that regardless of its strength, “it cannot alter our interpretation of the unambiguous provisions of the Convention.”[22] Implicitly, it would appear that the question of when the “general principle” is “chang[ed]” has an answer that is unambiguous to the Federal Circuit. However, the court did not reveal that answer.

In contrast, the Court of Federal Claims found the extrinsic evidence to be quite relevant and persuasive. The technical explanation states (with emphasis added by the court): “Paragraph 1 provides a credit for these specified taxes whether or not they qualify as creditable under Code section 901 or 903.”[23] This “alone is a complete refutation of the government’s overall position.”[24] The technical explanation also referred to a “taxpayer who claims credit under the Convention for Canadian taxes made creditable solely by paragraph 1.”[25] The trial court further credited the treaty’s transmittal letter and the Joint Committee on Taxation’s (JCT) explanation for the intent to eliminate double taxation. “And here’s another total refutation of the government’s position from the JCT Explanation: ‘[T]he treaty’s rules are used only if the taxes are not creditable under the Code.’”[26] The government’s attempt to rely on the separate technical explanation for the 2006 U.S. model treaty (twenty-six years later) backfired because it stated that “the United States will allow a credit to its citizens and residents in accordance with the Article, even if such credit were to provide a benefit not available under the [I.R.C.].”[27] The taxpayer in Bruyea also successfully enlisted Canada’s support, according to the court.[28] All of this was disregarded by the Federal Circuit.

Christensen Analysis

The trial court in Bruyea claimed that the U.S. Law Limitation clause applied to the second credit clause, the one specific to U.S. citizens residing in Canada. The Federal Circuit agreed but provided its rationale in Bruyea’s companion case, Christensen v. United States, published on the same day as Bruyea. Although Christensen regarded the French tax treaty, “the treaty provisions relevant to the dispute in Bruyea are materially identical to those at issue here.”[29] In Christensen, the Court of Federal Claims ruled in favor of the taxpayer because the U.S. Law Limitation clause did not appear with the second credit clause. Yet, that was irrelevant, according to the Federal Circuit. “It is commonplace to speak — and, more to the point, for Congress to draft — in economies that eliminate such redundancy.”[30] This is reflected in the “distributive canon” of statutory interpretation, which “recognizes that sometimes where a sentence contains several antecedents and several consequents, courts should read them distributively and apply the words to the subjects which, by context, they seem most properly to relate.”[31] Paragraphs of the same section must be read together. Once they “are read together, it is clear the introductory U.S. Law Limitation carries over,” functioning “as an overarching qualifier,” according to the Federal Circuit.[32] The remainder of Christensen’s opinion was essentially a copy of Bruyea’s opinion.

Conclusion

“Simply put, we cannot read an amendment into the Convention.”[33] Instead, “[i]n our view, the government correctly reads the U.S. Law Limitation, and therefore the Code, as governing in all instances except when the Convention expressly states that it does not.”[34]As often repeated in cases denying taxpayers an exemption or a deduction, “[w]hether and to what extent deductions shall be allowed depends upon legislative grace; and only as there is clear provision therefor can any particular deduction be allowed.”[35] Thus, such tax provisions are construed against the taxpayer. However, the 6th Circuit reflected in 1945: “Relief from double taxation is not so much an act of grace as one of justice in determining the true net income of the taxpayer.”[36] As Bruyea itself asserted, “[i]n construing a treaty, the terms thereof are given their ordinary meaning in the context of the treaty and are interpreted, in accordance with that meaning, in the way that best fulfills the purposes of the treaty.”[37] As of writing, it is unclear whether the taxpayers will appeal these decisions, whether to the Supreme Court or as a petition to the Federal Circuit for a rehearing en banc by the full court and not just a panel. For now, taxpayers may rely only on explicit tax treaty positions to the extent they are contrary to the IRC. Although each tax treaty is different, most are based on a model tax treaty, as is the case with the Canadian and French tax treaties.

If you have any foreign tax credit questions, please call 916-822-8700 or email info@lawburton.com.


[1] IRC § 27.

[2] IRC § 1411.

[3] Public Law 111-152.

[4] H. Rept. 111-443.

[5] U.S.—Canada Tax Treaty, Art. XXIV(1) & (4).

[6] Est. of Bruyea v. United States, No. 2025-1563, 2026 U.S. App. LEXIS 26543, at *9 (Fed. Cir. Aug. 31, 2026).

[7] Id. at *23-24(brackets and ellipsis added by the court).

[8] Id. at *25.

[9] Id. at *24.

[10] Id. at *13.

[11] Id. at *14.

[12] Id. at *26.

[13] Id. at *25(emphasis added by the court).

[14] Id.

[15] Id. at *26 n.6. As support, the Federal Circuit cited the treaty provision “setting out, in Article XXVI, ‘Mutual Agreement Procedure,’ including how taxpayer should proceed when he “considers that the actions of one or both of the Contracting States result or will result for him in taxation not in accordance with the provisions of this Convention.” Yet the court interrupted the quoted provision, which continued “he may, irrespective of the remedies provided by the domestic law of those States, present his case in writing to the competent authority of the Contracting State of which he is a resident or, if he is a resident of neither Contracting State, or which he is a national.” U.S.—Canada Tax Treaty, Art. XXVI(1).

[16] Est. of Bruyea v. United States, No. 2025-1563, 2026 U.S. App. LEXIS 26543, at *19 (Fed. Cir. Aug. 31, 2026).

[17] Id. at *20.

[18] Id. at *18.

[19] Id. at *20(omitting internal quotation marks).

[20] Id. at *22.

[21] Id. at *27.

[22] Id. at *29.

[23] Bruyea v. United States, 174 Fed. Cl. 238, 257 (2024)(emphasis added by the court).

[24] Id.

[25] Id.(emphasis added by the court).

[26] Id.(emphasis and brackets added by the court).

[27] Id. at 258(emphasis and brackets added by the court).

[28] “The position of the Canadian competent authority in this regard is that Canada, as the country of source, has the right to tax the gain, while the US, as the country which has residual taxation rights, must provide relief in accordance with Article XXIV of the Convention.” Id.

[29] Christensen v. United States, No. 2024-1284, 2026 U.S. App. LEXIS 26539, at *8 (Fed. Cir. Aug. 31, 2026).

[30] Id. at *10-11.

[31] Id. at *11.

[32] Id. at *12.

[33] Est. of Bruyea v. United States, No. 2025-1563, 2026 U.S. App. LEXIS 26543, at *18 (Fed. Cir. Aug. 31, 2026).

[34] Id. at *20 n.5(emphasis in original).

[35] Id. at *15(quoting New Colonial Ice Co. v. Helvering, 292 U.S. 435, 440 (1934)).

[36] Gentsch v. Goodyear Tire & Rubber Co., 151 F.2d 997, 1000 (6th Cir. 1945).

[37] Est. of Bruyea v. United States, No. 2025-1563, 2026 U.S. App. LEXIS 26543, at *11 (Fed. Cir. Aug. 31, 2026)(quoting Xerox Corp. v. United States, 41 F.3d 647, 652 (Fed. Cir. 1994)).
Categories
News

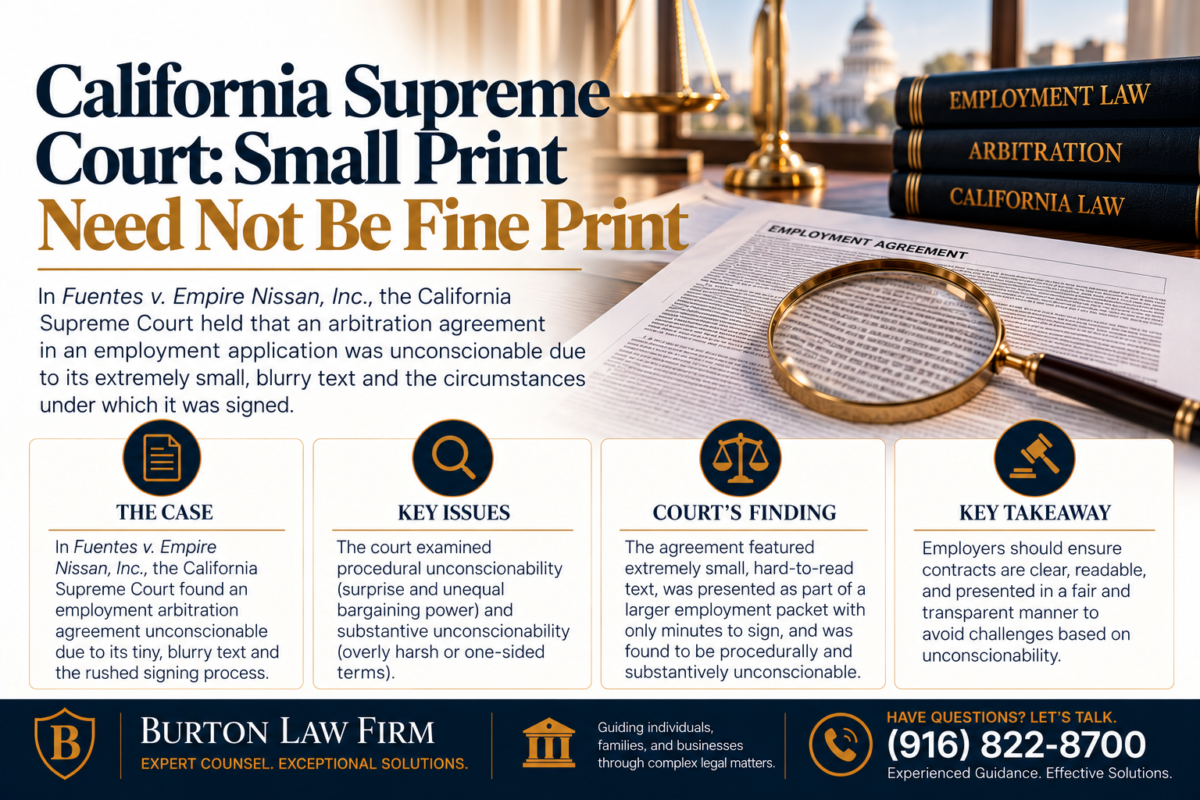
California Supreme Court: Small Print Need Not Be Fine Print

In Fuentes v. Empire Nissan, Inc., a discharged employee sued in a Superior Court, arguing that the arbitration agreement was unconscionable. The trial court sided in her favor, only to be reversed by the California Court of Appeal in 2023, which in turn was reversed by the California Supreme Court. Now the plaintiff needs to start over.

Seldom has any case focused so much on a contract’s cosmetics as Fuentes. To the California Supreme Court, “[t]he document is printed in a very small font and its text is so blurry and broken up that it is nearly unreadable.”[1] The Court of Appeal was so struck that it uploaded the contract’s photocopy from the court record as an appendix to the opinion to demonstrate its lamentable quality. It is reproduced at the end of this article as well (without shrinking). The Supreme Court noted that its difficulty was not merely aesthetic. “[T]he arbitration agreement consists of a mammoth paragraph consisting of something like 900 words, with 35 lines squeezed into about three vertical inches of text.  One sentence, by itself, is 214 words long.”[2] Its state was such that the Supreme Court suggested legislative reform as a cure.[3]

As if to craft an ideal law school exam question, the circumstances of its signing were no less dubious. This document was but one component in an employment application packet for which the plaintiff was given five minutes to complete. It was a race:

She was told that the documents in the packet had to do with her employment application, contacting her references, and a drug testing requirement, that she had to complete the documents to work for Empire Nissan, and that she should hurry because the drug testing facility was about to close. She was not offered an opportunity to ask questions. She did not receive a copy.[4]

The question was whether this contract is unconscionable.

         “A contract is unconscionable if one of the parties lacked a meaningful choice in deciding whether to agree and the contract contains terms that are unreasonably favorable to the other party.”[5] This test is divided into procedural unconscionability and substantive unconscionability. “The procedural element concerns the circumstances of contract negotiation and formation, particularly oppression or surprise due to unequal bargaining power. The substantive element, by contrast, concerns the fairness of an agreement’s actual terms, i.e., whether those terms are overly harsh or one-sided.”[6] These components are weighed in “a sliding scale analysis under which the more substantively oppressive a term, the less evidence of procedural unconscionability is required to come to the conclusion that the term is unenforceable, and vice versa.”[7] If unconscionability is a large explosion of two hazardous chemicals of equal combustibility, both must be present regardless of either chemical’s amount. However, the explosion’s size is still dependent on the mass of both chemicals, regardless of the proportion therein.

         Clearly, this case featured “a contract of adhesion, i.e., a standardized contract which, imposed and drafted by the party of superior bargaining strength, relegates to the subscribing party only the opportunity to adhere to the contract or reject it.”[8] “Some procedural unconscionability” is present in every contract of adhesion.[9] “[O]rdinary contracts of adhesion are indispensable facts of modern life that are generally enforced.”[10] Nevertheless, “[b]ecause contracts of adhesion are not the result of freedom or equality of bargaining, we examine them carefully.”[11] The power disparity between employer and employee, the small font, the blurry font, the linguistic complexity, the misinformation provided to the plaintiff, the brief amount of time to review the contract, and the failure to provide a copy of the contract to the plaintiff all supported a finding of extraordinary procedural unconscionability. Since “the agreement involved such a high degree of procedural unconscionability, even a low degree of substantive unconscionability may render the agreement unenforceable.”[12]

         The next question was whether the contract was substantively unconscionable. Terms that are “overly harsh, unduly oppressive, so one-sided as to shock the conscience, or unfairly one-sided” are substantively unconscionable.[13] Fuentes v. Empire Nissan, Inc. was decided in the shade of OTO, L.L.C. v. Kho, another case regarding the unconscionability of an employee’s arbitration agreement with the employer.[14] Kho held that substantively unconscionable contracts “may include fine-print terms, unreasonably or unexpectedly harsh terms regarding price or other central aspects of the transaction, and terms that undermine the nondrafting party’s reasonable expectations.”[15] An appellate case, Davis v. TWC Dealer Group, Inc., interpreted Kho’s “fine-print terms” to mean terms “so small as to challenge the limits of legibility.”[16] Thus, Davis held, illegibility is a factor for substantive unconscionability. Fuentes clarified that the California Supreme Court meant “substantively unfair or one-sided terms hidden in a legal document,” by “fine-print terms.”[17] “Such terms may be hidden in a variety of ways, including by printing them in text that is smaller than the surrounding text, burying them in a large block of text, or placing them in a part of the document likely to be overlooked.”[18] The Court explained that Kho quoted from Sonic-Calabasas A, Inc. v. Moreno, which quoted from a secondary source, “Williston on Contracts.”[19] “The Williston treatise observes that contract terms ‘whether in fine print or legal ‘gobbledygook’ would hardly be of concern unless they were substantively harmful to the nondrafting party as well.’”[20] This observation was neither in Sonic-Calabasas nor Kho. Yet “[t]his context makes clear that we did not mean by our reference to ‘fine-print terms’ in Kho that a contractual term could be substantively unconscionable merely because it was printed in a small font.”[21]

Using unquoted language in a secondary source to explain what a court meant by the secondary source’s quoted language may be risky, but it was obvious to Fuentes. Kho, a case regarding a contract with small font,also had a brief nonexclusive list for procedural unconscionability, yet it did not include the font size in that list.[22] For its part, Black’s Law Dictionary defines “fine print” as: “The part of an agreement or document — usu. in small, light print that is not easily noticeable — referring to disclaimers, restrictions, or limitations.”[23] Merely being a disclaimer, restriction, or limitation does not make a term substantively unconscionable—all contracts are limited. The Court did not offer its own definition of “fine print.” Ultimately, “because font size does not affect the substance of an agreement’s terms, it cannot render a contractual term substantively unconscionable.”[24]

Some time after signing the arbitration agreement, the plaintiff signed two confidentiality agreements with her employer. These agreements provided that the employer “may seek any remedies available at law or in equity and that the prevailing party in a ‘legal action’ to enforce the agreements may recover attorney fees and costs.”[25] The Court held that “legal action” meant a judicial proceeding. “Most significantly, the confidentiality agreements make no reference to arbitration,” which “suggests that, at the time of their signing, the parties did not intend for claims under them to be subject to mandatory arbitration.”[26] Nevertheless, the arbitration agreement required any amendment to be signed by the president of the employer, and the confidentiality agreements allegedly lacked any such signature. The Court of Appeal took that allegation along with the notion that “the law strongly favors” arbitration to hold that the arbitration agreement remained intact.[27] “The Court of Appeal’s reliance on the policy favoring arbitration as an interpretive presumption was misplaced.”[28] Such a policy merely provides an “equal treatment principle” ensuring that arbitration agreements “are treated like other contracts.”[29] The Court seemingly redefined the meaning of “favoring.”

In addition, “[t]he Court of Appeal relied on the lack of signature without a factual record to support that conclusion.”[30] Therefore, the case was remanded. The sole dissenter to the majority opinion vigorously opposed this decision because the plaintiff did not make this argument before the Court (although she did so in the trial court), even though the employer “waived any argument that its president did not sign the agreement by failing to make that argument in the trial court.”[31] The majority opinion simply thought it proper for the factual question regarding the signatures to be answered in the trial court. In addition, the majority opinion noted the argument that the plaintiff could not have assented to the contract because it was so illegible. However, the trial court did not rule on this question. On remand, “the trial court may, in its discretion, allow the parties to submit additional briefing on the relationship between legibility and mutual assent. We express no view on this subject.”[32]

If you are concerned that a contract may be unconscionable, please call 916-822-8700 or email info@lawburton.com.


[1] Fuentes v. Empire Nissan, Inc., 19 Cal. 5th 93, 100 (2026).

[2] Id. at 105(omitting internal quotation marks and citation).

[3] “The Legislature may wish to consider specifying requirements for employment contracts that promote legibility and comprehensibility, as it has with other types of contracts.” Id. at 105 n.2.

[4] Id. at 100.

[5] Id. at 102-103.

[6] Id. at 103(omitting internal quotation marks and citation).

[7] Id.

[8] Id.

[9] Id.

[10] Id. at 103-104.

[11] Id. at 104(omitting internal quotation marks).

[12] Id. at 105.

[13] Id. at 106(omitting internal citations and quotation marks).

[14] OTO, L.L.C. v. Kho, 8 Cal. 5th 111, 121 (2019).

[15] Id. at 130(emphasis added).

[16] Davis v. TWC Dealer Grp., Inc., 41 Cal. App. 5th 662, 674 (2019).

[17] Fuentes v. Empire Nissan, Inc., 19 Cal. 5th 93, 107 (2026).

[18] Id.

[19] Sonic-Calabasas A, Inc. v. Moreno, 57 Cal. 4th 1109, 1145 (2013).

[20] Fuentes v. Empire Nissan, Inc., 19 Cal. 5th 93, 107 (2026).

[21] Id.

[22] “The circumstances relevant to establishing oppression include, but are not limited to (1) the amount of time the party is given to consider the  proposed contract; (2) the amount and type of pressure exerted on the party to sign the proposed contract; (3) the length of the proposed contract and the length and complexity of the challenged provision; (4) the education and experience of the party; and (5) whether the party’s review of the proposed contract was aided by an attorney.” OTO, L.L.C. v. Kho, 8 Cal. 5th 111, 126-27 (2019)(quoting Grand Prospect Partners, L.P. v. Ross Dress for Less, Inc., 232 Cal. App. 4th 1332, 1348 (2015)).

[23] Black’s Law Dictionary (8th ed. 2004).

[24] Fuentes v. Empire Nissan, Inc., 19 Cal. 5th 93, 107 (2026).

[25] Id. at 108.

[26] Id. at 122.

[27] Id. at 110.

[28] Id.

[29] Id.

[30] Id. at 112 n.5.

[31] Id. at 111-112.

[32] Id. at 114.

Categories
News

Statutory Economic Substance Doctrine

In 2010, Congress codified the economic substance doctrine in § 7701(o) of the Internal Revenue Code.[1] Patel v. Commissioner “is the Court’s first opportunity to examine when the codified economic substance doctrine applies.”[2] The taxpayers engaged in a microcaptive insurance company scheme to avoid taxes. They did not engage in any “feasibility study to determine the costs and merits of a captive arrangement,” and they did not “explore[] the cost and availability of the same policies on the commercial market.”[3]  They used ordinary commercial insurance for their bona fide businesses at a cost of between $68,000 and $106,000 while choosing to pay nearly $1.2 million in annual premiums to their microcaptive insurance company (at the time $1.2 million was the limit for favorable § 831(b) treatment). Yet one purported reason for the microcaptive insurance company was to insure their businesses. Worst of all, the taxpayers’ emails were quite explicit regarding the tax avoidance purpose. Two prior Tax Court opinions already determined that the insurance deductions were disallowed. Now, the issue was whether any penalties applied.

Section 6662 lists ten grounds for an accuracy-related penalty on underpayments. “Only one accuracy-related penalty may be applied with respect to any given portion of an underpayment, even if that portion is penalizable on more than one of the grounds set forth in section 6662(b).”[4] One of these is the “accuracy-related penalty on the portion of an underpayment of tax required to be shown on a return attributable to the disallowance of claimed tax benefits by reason of a transaction lacking economic substance within the meaning of section 7701(o).”[5] This is an important penalty because its rate doubles to 40% if “the relevant facts affecting the tax treatment are not adequately disclosed in the return nor in a statement attached to the return.”[6] Such a transaction is termed a “nondisclosed noneconomic substance transaction.”[7] The 40% penalty has § 7701(o) applicability as a necessary, but not sufficient, condition.

Turning to § 7701(o), the Tax Court “easily conclude[d] that the statute requires a relevancy determination. To put it plainly—the statute says so, right there, on its face.”[8] Furthermore, this relevancy determination was preliminary and apart from the two-part test contained in the statute. This is determined “as if the statute had never been enacted.”[9] Here, the Tax Court found plenty of caselaw before 2010 applying the doctrine to captive insurance cases and concluded that it was relevant. Therefore, economic substance can be found only when “the transaction changes in a meaningful way (apart from Federal income tax effects) the taxpayer’s economic position, and the taxpayer has a substantial purpose (apart from Federal income tax effects) for entering into such transaction.”[10]

There was “a circular flow of funds” between the insurer and the insured, controlled by related parties to the extent that there was not a meaningful economic change for the taxpayers.[11] The tax purpose was all but admitted through the emails. Yet the conclusion was still otherwise inevitable, given that the “premiums were not set by actuarial principles, but by their only customer whose expressed interest was in paying the maximum deductible amount” and who “sat on both sides of the transactions” by “doubling as [the insurance company’s] sole customer and founder.”[12] There were many other facts unfavorable to the taxpayer in a profusion of discrepancies seemingly designed by a law professor to create an exam question with an easy answer.

Section 6662(b)(6) imposes a penalty on the occurrence of: “Any disallowance of claimed tax benefits by reason of a transaction lacking economic substance (within the meaning of section 7701(o)) or failing to meet the requirements of any similar rule of law.” Patel next pondered the meaning of “by reason of.” “The most natural reading of this statute is that a lack of economic substance must be the cause of the disallowance of the claimed tax benefit (here, deductions for purported insurance premiums).”[13] The Tax Court further equated “by reason of” with “because of” in the English language.[14] Strikingly, the notices of deficiencies imposed the § 6662(b)(6) penalty yet forbore from disallowing the deductions giving rise to the penalty. These were disallowed only through the IRS’s pleadings in Tax Court. The penalty increase from 20% to 40% also only occurred through such pleadings. “[W]here the Commissioner asserts a new matter, such as a penalty, in an answer (rather than in the NOD), the Commissioner bears the full burden of proof regarding the penalty, including the taxpayer’s lack of reasonable cause or any other applicable affirmative defense.”[15] The absence of economic substance was well proven. 

The 40% nondisclosed noneconomic substance transaction penalty requires the lack of disclosure. For the Tax Court, “[t]his is our first opportunity to consider what constitutes adequate disclosure under section 6662(i)(2).”[16] However, the court simply adopted caselaw regarding adequate disclosure in other contexts. This is a question of fact requiring disclosure to “be sufficiently detailed to alert the Commissioner and his agents as to the nature of the transaction so that the decision as to whether to select the return for audit may be a reasonably informed one.”[17] Slightly more specifically, “[t]he disclosure must be more substantial than providing a clue that would intrigue the likes of Sherlock Holmes but need not recite every underlying fact.”[18] Again, this requirement was clearly wanting. Unfortunately, the Tax Court did not describe or even indicate what might have been sufficient disclosure for these purposes. The remaining penalties (the 40% percent penalty was not sought for all years) were imposed with ease. Notably, the taxpayer’s characterization of himself as a “savvy financial person” who did not need tax advice undermined his attempt to claim reliance on a tax professional as a defense

There are certain tantalizing aspects of Patel v. Commissioner. One is the recognition of the preliminary requirement’s existence. “Congress could hardly have been clearer, at least on this narrow point.”[19] The Tax Court did not explain how relevance is determined, but did so by reviewing caselaw. It is unclear whether there is another means for finding relevance. The statute itself provides that it “[t]he determination of whether the economic substance doctrine is relevant to a transaction shall be made in the same manner as if this subsection had never been enacted.”[20] Yet limiting relevance based on caselaw prior to codification may allow an entirely novel question to escape the statutory economic substance doctrine’s grasp. For now, this appears to be the sole clue on the map toward the realm where economic substance is irrelevant.

The Tax Court treated the penalty in question as if entirely dependent on the statutory economic substance doctrine. Yet that is incorrect. The statute permits the violation of “any similar rule of law” to the statutory economic substance doctrine to be an alternative for the purpose of imposing the penalty. The Tax Court quoted the pertinent statutory language, but otherwise ignored what a “similar rule of law” may mean. Yet the most intriguing part of Patel was the least explained.

The Tax Court observed that one of the taxpayers “transferred ownership of these entities to his children so that assets would pass outside of his taxable estate.”[21] It further noted that the taxpayers “did not argue that their estate planning objective gave their microcaptive arrangement economic substance; we likewise restrict our analysis to the microcaptive transaction and its income tax effects.”[22] Patel v. Commissioner took pains to be thorough, pointedly explaining its holdings in full for multiple reasons even when one would be enough. It had the patience to address each of the taxpayer’s arguments in considerable detail, whether hidden in a footnote to a responsive pleading or nearly frivolous (e.g., claiming that the taxpayers were “Congressionally induced” into the tax scheme and therefore justified). The statutory version of the economic substance doctrine only applies to Subtitle A—estate taxation is in Subtitle B. It is unlikely that the Tax Court suggested that Subtitle B taxes are exempt from the common law version. Instead, perhaps, since the penalty provision was pegged by the court to the definition of economic substance to § 7701(o), which in turn is limited to Subtitle A (income) taxes, the taxpayers might have had a creditable argument had they claimed that estate tax avoidance was a sufficient non-income tax reason.

            Section 7701(o) is a powerful tool for the IRS with a powerful exception. Therefore, it is perplexing that the exception was not addressed. “In the case of an individual, [the statutory economic substance doctrine] shall apply only to transactions entered into in connection with a trade or business or an activity engaged in for the production of income.”[23] Here, the taxpayer did not operate the microcaptive insurance company for income. That was a significant reason why there was not any economic substance to the scheme. Furthermore, it is well established that “to be engaged in a trade or business, the taxpayer must be involved in the activity with continuity and regularity and that the taxpayer’s primary purpose for engaging in the activity must be for income or profit.”[24] It would appear that the taxpayer left a cogent argument forlorn.

If the IRS accuses you of conducting your affairs without economic substance, please call 916-822-8700 or email info@lawburton.com.


[1] “In relevant part, section 7701(o) provides:

Sec. 7701(o). Clarification of economic substance

doctrine.—

(1) Application of doctrine.—In the case of any transaction to which the economic substance doctrine is relevant, such transaction shall be treated as having economic substance only if—

(A) the transaction changes in a meaningful way (apart from Federal income tax effects) the taxpayer’s economic position, and

(B) the taxpayer has a substantial purpose (apart from Federal income tax effects) for entering into such transaction.

. . . .

(5) Definitions and special rules.—For purposes of this subsection–

(A) Economic substance doctrine.—The term “economic substance doctrine” means the common law doctrine under which tax benefits under subtitle A with respect to a transaction are not allowable if the transaction does not have economic substance or lacks a business purpose.

(B) Exception for personal transactions of individuals.—In the case of an individual, paragraph (1) shall apply only to transactions entered into in connection with a trade or business or an activity engaged in for the production of income.

(C) Determination of application of doctrine not affected.—The determination of whether the economic substance doctrine is relevant to a transaction shall be made in the same manner as if this subsection had never been enacted.

(D) Transaction.—The term ‘transaction’ includes a series of transactions.” Patel v. Commissioner, 165 T.C. No. 10 (2025) at *15-16.

[2] Id. at *16.

[3] Id. at *6.

[4] Id. at *30.

[5] Id. at *13.

[6] IRC § 6662(i)(2).

[7] Id.

[8] Patel v. Commissioner, 165 T.C. No. 10 (2025) at *17.

[9] Id.

[10] § 7701(o)(1).

[11] Patel v. Commissioner, 165 T.C. No. 10 (2025) at *23.

[12] Id. at *25.

[13] Id. at *27.

[14] Id.

[15] Id. at 11-12.

[16] Id. at 29.

[17] Id.

[18] Id.

[19] Id. at 17.

[20] § 7701(o)(5).

[21] Patel v. Commissioner, 165 T.C. No. 10 (2025) at *23-24.

[22] Id. at *24 n.17.

[23] § 7701(o)(5)(B).

[24] Commissioner v. Groetzinger, 480 U.S. 23, 35 (1987)(Analyzing the term in a different context).

Categories
News

Deficient Answer for Deficiency Definition

One of the most important rights a taxpayer enjoys is the opportunity of judicial review before a “deficiency” is “assessed.”[1] “Assessment is the formal recording of a taxpayer’s tax liability.”[2] Deficiency has a longer meaning. “The Code defines a deficiency as the amount by which the income, gift, estate, or excise tax imposed exceeds the excess of the sum of the amount shown as the tax by the taxpayer upon his return plus any previously assessed amounts, over the amount of rebates made.”[3] In Walker v. Commissioner, taxpayers erroneously claimed and received an excess Premium Tax Credit amount of $20,904 for the 2018 tax year. This was reported on Form 8962, an attachment to Form 1040, upon request by the IRS in 2019 because it was missing from the original 2018 tax return. The IRS claimed that this constituted a taxpayer-reported tax, obviating the need for a deficiency notice before assessing that amount. Form 8962 functions as the reconciliation of the advance Premium Tax Credit (APTC) amount with the allowable amount. The excess is treated as tax due. The Tax Court ruled in favor of the taxpayers. Unfortunately, its reasoning was rather parsimonious:

Form 8962, however, does not ultimately determine an amount of tax due from petitioners. Furthermore, petitioners’ return, as originally filed, failed to account for the PTC. Therefore, and upon receipt of information received in Form 8962, it was necessary for the IRS to determine whether petitioners had a deficiency in tax… We decline to accept the notion that this reconciliation acts as a self-assessment of additional tax. See, e.g., I.R.C. §36B(f)(2)(B) (limiting the amount of any tax due upon receipt of excess APTC to $600, $1,500, or $2,500, depending on the percentage of the taxpayer’s household income above the poverty line). Considering the specific wording of section 36B(f), we conclude that the IRS determined that petitioners owed additional tax notwithstanding their original filing, which is the quintessential definition of a deficiency.[4]

It is unclear what part of the “specific wording of section 36B(f)” prevented this reconciliation from being a self-assessment. The given example did not apply here. The limitation of repayment, which has since been repealed, is applicable only to certain income levels that the taxpayers exceeded—they were obliged to repay the excess amount in full.

Seemingly, the Tax Court is treating self-assessment in a manner reminiscent of self-incrimination—narrowly construed in the taxpayer’s favor and compliant with formalities to be valid. Technically, the amount given as excess APTC need not be part of the tax owed. It is possible that such amounts could be reduced by credits. Line 24 of Form 1040 states with emphasis: “This is your total tax.” Is the Tax Court claiming that self-assessment must be so explicit? In addition, the Tax Court emphasized that the original return lacked the owed tax and that Form 8962 was filed only in response to explicit prompting by the IRS. Is the Tax Court suggesting that compliance with an IRS inquiry is not a self-assessment? Is it the combination of the two circumstances? In another facet, the Tax Court declared after giving the definition of “deficiency”: “On the basis of the foregoing plain text of the Code, we find that petitioners’ legal argument that the Assessment is a deficiency determination under the Code is well supported.”[5] This was written before the Tax Court analyzed § 36B(f) regarding the APTC, suggesting that § 36B(f) was not necessarily determinative.            

There is little caselaw regarding when an amount is self-assessed for the purposes of deficiency lexicology. This makes Walker v. Commissioner’s vagaries all the more perplexing. Apparently, the result was nearly self-evident to the Tax Court. Overall, it appears that this rule provides that amounts outside the main body of Form 1040 or equivalent tax return are presumed not to be self-assessment for the purposes of defining “deficiency.” Although not explicitly stated, the IRS is likely barred by the statute of limitations from properly assessing the amount that the taxpayer conceded.

If the IRS wrongly assesses a deficiency before an opportunity for judicial review, please call 916-822-8700 or email info@lawburton.com.


[1] § 6213(a).

[2] Walker v. Commissioner, No. 2801-24L, 2026 Tax Ct. Memo LEXIS 4, at *12 n.9 (T.C. Jan. 8, 2026)(omitting internal quotation mark).

[3] Walker v. Commissioner, No. 2801-24L, 2026 Tax Ct. Memo LEXIS 4, at *12 (T.C. Jan. 8, 2026)(omitting internal quotation marks, brackets, and ellipses).

[4] Walker v. Commissioner, No. 2801-24L, 2026 Tax Ct. Memo LEXIS 4, at *11 & 13 (T.C. Jan. 8, 2026).

[5] Walker v. Commissioner, No. 2801-24L, 2026 Tax Ct. Memo LEXIS 4, at *13 (T.C. Jan. 8, 2026).

Categories
News

Second Circuit Overturns Tax Court on Assessable Penalties

Section 6038 generally requires a U.S. person to file an information return regarding each foreign business the U.S. person controls. For example, Form 5471 is for controlled foreign corporations, and Form 8865 is for controlled foreign partnerships. Failing to file incurs two penalties. One (§ 6038(b)) charges a minimum of $10,000 and a maximum of $60,000 if not cured.[1] The other (§ 6038(c)) reduces the foreign tax credit by a minimum of 10% and a maximum of 100% if not cured, but this is reduced by the amount of the other penalty.[2]

Normally, a creditor must sue in a court of law to collect a debt. There is an exception for one of the most common debts, the income tax. Then, “[o]nly in rare instances is a lawsuit necessary. The agency can instead usually collect taxpayers’ liabilities through ‘assessment.’”[3] An assessment “allow[s] the IRS to seize assets, freeze bank accounts, and create liens—all without setting foot in a courtroom.”[4] This can be contested, but only on the taxpayer’s initiative. A private creditor sues to collect a debt, and a taxpayer sues for a tax not to be collected.

Safdieh v. Commissioner

In Safdieh v. Commissioner, the taxpayer failed to file under § 6038 for the 2005-2009 tax years. The penalties totaled $50,000. The question is whether this can be assessed. This was first answered by the Tax Court in 2023 through Farhy v. Commissioner.[5] There, the Tax Court ruled that § 6038(b) is not an assessable penalty. However, the D.C. Circuit reversed the Tax Court, holding that § 6038(b) is an assessable penalty.[6] This did not settle the matter outside of the D.C. Circuit. Another § 6038(b) case arose, and the Tax Court clarified in Mukhi v. Commissioner that it will follow its original Farhy reasoning outside of the D.C. Circuit.[7] The Tax Court repeated this policy in subsequent decisions, including Safdieh v. Commissioner.[8] The 2nd Circuit joined the D.C. Circuit in overruling the Tax Court in this matter.

Section 6038(b) does not explain whether the penalty is assessable. “Despite the parties’ attempts at exegesis, the text simply does not say whether the penalty is, or is not, assessable.”[9] Nevertheless, the 2nd Circuit found three reasons why the penalty is assessable. The first is through legislative history, the second is the statutory purpose, and the third is the placement of statutory language in the United States Code.

The penalty in question was enacted in 1982. The accompanying Senate report explained that the existing penalty (regarding the foreign tax credit) is insufficient for multiple reasons, including its complexity. To the 2nd Circuit, this makes the decision to make the new penalty nonassessable “implausible”: “It is unlikely that Congress would have wished to put even more logs in the way of the tax harvester when its stated aim was to clear the road.”[10] Specifically, “[t]he Committee Print indicates that the fixed dollar penalty was meant to ‘simplify the penalty for failure to furnish information’ by ‘giv[ing] Internal Revenue Service agents a simple straight-forward penalty to impose where reports . . . are not filed or are inadequate.’”[11] Requiring the IRS to go to the Justice Department to go to a district court would not accomplish that mission of simplicity. The IRS has assessed the penalty since its enactment. “As evidence of the statute’s original meaning, it deserves substantial weight.”[12] This is distinct from deferring to the IRS, the 2nd Circuit argued. Furthermore, Congress knowingly acquiesced in this practice of assessment.  The Federal Courts Improvement Act was also enacted in the same year as the penalty for the purpose of decreasing the caseload of the district courts. It would be illogical for the same Congress to increase the caseload. Furthermore, the threshold for diversity jurisdiction was ten times the original § 6038(b) penalty amount. “Saddling the Commissioner with a federal case over such a small sum would hamper the federal courts and the Commissioner at a time when the evidence suggests that Congress wished to relieve both.”[13]

Section 6038(c)(3) coordinates the two § 6038 penalties by providing that the § 6038(c) penalty regarding the foreign tax credit is decreased by the amount of the § 6038(b) penalty. To the 2nd Circuit, this was ample proof that the two penalties were intended to be assessed in tandem. Diverging the two penalties would result in gross inefficiency. “We give Congress more credit than that.”[14] Due to this dissonance “parties may try to game the proceedings by rushing to judgment in the ‘right’ court and erecting barriers to judgment in the ‘wrong’ one.”[15]

The taxpayer claimed that 28 U.S.C. § 2461(a) is the Commissioner’s sole authority to collect the penalty. This is not in the Internal Revenue Code, which was determinative for the 2nd Circuit. “Even more revealingly, in the thirty-four years between this provision’s enactment in 1948 and the dollar penalty’s enactment in 1982, the provision was never used to collect a tax or tax penalty.”[16]

Farhy & Mukhi

            The Tax Court’s theory, as articulated in Farhy v. Commissioner and Mukhi v. Commissioner, was left entirely unmentioned. Consequently, it is unlikely that the Tax Court will change its mind after Safdieh when it declined to do so in Mukhi v. Commissioner after the D.C. Circuit Court overturned the Tax Court in Farhy v. Commissioner.

The Tax Court premised its analysis in both Farhy and Mukhion on a Supreme Court quote, “[a]gencies have only those powers given to them by Congress.”[17] This was unmentioned by the 2nd Circuit Court. To the Tax Court, the IRC simply did not designate the penalties as “assessable” and therefore they were not assessable. It refused to “infer[] the power to administratively assess and collect the section 6038(b) penalties when Congress did not see fit to grant that power to the Secretary of the Treasury expressly as it did for other penalties in the Code.”[18] Even if the legislative history indicated otherwise, it cannot overcome the plain (lack of) language in the statute. “The text is clear, and therefore we need not consider legislative history to attempt to ascertain Congress’s intentions.”[19] In any case, the Tax Court was unimpressed with the passage that so moved the circuit courts. “We will not read a passing statement about the complicated nature of a penalty as empowering the IRS to assess a different penalty.”[20]

Ultimately, the Tax Court considers appellate decisions by courts other than the Supreme Court as essentially optional to follow. “The Tax Court adheres to the doctrine of stare decisis” and “takes seriously its obligation to facilitate uniformity in the tax law” as a nationwide court.[21] “When one of our decisions is reversed by an appellate court, the Court will thoroughly reconsider the problem in the light of the reasoning of the reversing appellate court and, if convinced thereby, follow the higher court.”[22] Yet if “convinced that our original decision was right, the proper course is to follow our own honest beliefs until the Supreme Court decides the point.”[23] Nevertheless it will follow a contrary appellate decision when both the decision is “squarely on point” and an appeal from the Tax Court would rest in the circuit court that issued the contrary decision.[24] “To do otherwise would be futile and wasteful given the inevitable reversal from the appellate court.”[25]

If you were assessed with a penalty for failing to file Form 5471, Form 8865, or another IRS form, please call 916-822-8700 or email info@lawburton.com.


[1] IRC § 6038(b). The minimum penalty is $10,000, with another $10,000 charged for each 30-day period (up to $50,000) after 90 days from the day the IRS mails notice of the failure to file to the taxpayer.

[2] § 6038(c). Similar to the other penalty, the foreign tax credit reduction starts at 10% and is further reduced by 5% for each additional 3-month period that the taxpayer does not file after 90 days from the day that notice of the failure to file is mailed by the IRS to the taxpayer.

[3] Safdieh v. Comm’r, 2026 U.S. App. LEXIS 5796, *3.

[4] Id. at *4.

[5] 160 T.C. 399 (2023), rev’d and remanded, 100 F.4th 223 (D.C. Cir. 2024).

[6] Farhy v. Comm’r of IRS, 100 F.4th 223 (2024).

[7] 163 T.C. 150 (2024).

[8] Safdieh v. Commissioner, No. 11680-20L, 2024 U.S. Tax Ct. LEXIS 3021 (T.C. Dec. 5, 2024); Cauchon v. Commissioner, No. 23863-22L, 2025 U.S. Tax Ct. LEXIS 405 (T.C. Feb. 14, 2025).

[9] Safdieh v. Comm’r, 2026 U.S. App. LEXIS 5796, *5 fn.18.

[10] Id. at *7.

[11] Id. at *7 fn.29.

[12] Id. at *7.

[13] Id. at *9.

[14] Id. at *11.

[15] Id. at *12.

[16] Id. at *13.

[17] Farhy v. Commissioner, 160 T.C. 399, 404 (2023)(quoting West Virginia v. EPA, 597 U.S. 697, 723 (2022)); Mukhi v. Commissioner, 163 T.C. 150, 156 (2024)(quoting West Virginia v. EPA, 597 U.S. 697, 723 (2022)).

[18] Farhy v. Commissioner, 160 T.C. 399, 406 (2023).

[19] Mukhi v. Commissioner, 163 T.C. 150, 160 (2024).

[20] Id. at 165..

[21] Id. at 154 (2024).

[22] Id.(omitting internal quotation mark and ellipsis).

[23] Id.(omitting internal quotation mark and brackets).

[24] Id.(omitting internal brackets).

[25] Id.(omitting internal quotation marks).

Categories
News

Chinese Taxation of Offshore Trusts

Chinese residents are taxed on their worldwide income by China. Nonresidents are taxed by China only on income sourced to China. Offshore trusts have become a popular means amongst wealthy Chinese to avoid the income tax. On July 24, 2026, China suddenly announced new rules for offshore trusts to stop this avoidance. These came in the form of Announcement 15 and Announcement 21 by the State Taxation Administration.[1] Announcement 21 provides most of the substantive rules, while Announcement 15 is primarily concerned with reporting obligations. These are short documents. Announcement 21 is only 5 pages long, while Announcement 15 is only 4 pages long.

In general, a resident’s transfer of property to an offshore trust is a taxable event as if it were sold for fair market value. For each year that the property is in an offshore trust under the resident’s control, the property is taxed on its appreciation, even if it was not sold or distributed. “Losses may not be carried forward to offset income in subsequent years.”[2] Any income from the offshore trust property, such as interest or dividends, is also taxed. If the offshore trust property is distributed to a resident, the resident must pay a tax on the property’s value to the extent such value was not already taxed by the trust grantor. If the resident becomes a nonresident, the property is taxed as if it were sold. If more than one resident contributes property to an offshore trust, each resident is taxed on the proportionate share of the property they contributed to the entirety of the offshore trust’s property. A nonresident’s transfer of property to an offshore trust is taxed only to the extent that the property is sourced to China. The tax rate is 20% throughout this process.

An “offshore trust” is defined as “a trust or other legal arrangement having trust functions established under the laws of a jurisdiction outside China.”[3] However, this definition “excludes financial products issued by banks, insurance companies, securities companies, fund companies, and similar institutions that are regulated by the financial regulatory authorities of the countries or regions in which they are located and that independently conduct business with an unspecified clientele and bear the associated risks.”[4] A transfer to an offshore trust is taxed on “the property’s market value, less its original value and reasonable expenses.”[5] The term “reasonable expenses” is undefined. Indirect transfers are also included in these rules. “Where an individual transfers property through another individual or organization, and the individual actually funds, bears the cost of, and controls that property, the individual shall be deemed to have acquired and contributed the property.”[6] Notably, the term “controls” is undefined. However, “[w]here an offshore trust to which a nonresident individual has contributed property distributes income to a nonresident individual, but another resident individual actually receives, uses, controls, or disposes of that income, the offshore trust shall be deemed to have distributed the income to that resident individual.”[7] China expanded the category of residents for these purposes. “An individual who has acquired foreign nationality or long-term or permanent residence rights outside China, but whose principal economic interests derive from within China, may be determined to be a resident individual domiciled in China.”[8]

These announcements are retroactive to an unknown degree. Although they claim to be effective immediately (July 24, 2026), there is a provision waiving penalties for unpaid tax liabilities arising from these new rules from transfers to offshore trusts from January 1, 2023, to December 31, 2025, if paid by October 22, 2026. The announcements are technically interpretations of existing law rather than the proclamation of a new law. It is theoretically possible that these rules apply to offshore trust transfers before 2023.

Separately, China announced that it “will impose a 20 percent individual income tax on dividends and bonuses that foreign individuals receive from foreign-invested enterprises starting September 1.” The “temporary exemption” in place since 1994 is now over.


[1] Unfortunately, neither of them appears to have an official English translation.

[2] Announcement No. 21, § 4(unofficial translation).

[3] Id. at § 1(unofficial translation).

[4] Id.(unofficial translation).

[5] Id. at § 4(unofficial translation).

[6] Id. at § 2(unofficial translation).

[7] Id. at § 8(unofficial translation).

[8] Id. at § 11(unofficial translation).

$15 Million Tax-Free Stock Sales and How to Exclude Income by Including Income

California is the land of start-ups. From January to August 2026, venture capitalists invested about $366 billion in California businesses. This venture capital is over triple the amount received by the remaining 49 states combined. Yet most founders, investors, and key employees are likely unaware of two valuable opportunities available under the Internal Revenue Code for start-ups.

The first is qualified small business stock treatment provided by section 1202 of the Internal Revenue Code. A person who purchased stock in a small C corporation (not more than $75 million in gross assets) can potentially exclude up to $15 million of gain if held for more than 5 years. There are several technical requirements. One of the most significant limitations is the disqualification of service industries “where the principal asset of such trade or business is the reputation or skill of 1 or more of its employees.”[1] Yet, there is flexibility facilitating gifts, inheritances, and indirect share ownership (such as through partnerships). There are relatively few regulations regarding qualified small business stock. Consequently, multiple advanced techniques remain viable, especially for the $15 million exclusion limitation.

The second overlooked opportunity lies in the regulations under Internal Revenue Code section 409A. The tax treatment of stock options is multifaceted. If part of a nonqualified deferred compensation plan, the stock option holder is taxed on that option’s value plus 20% of that value, along with interest. One means to avoid this outcome is to follow section 409A’s strict rules, which result in deferring the income inclusion until the option is struck. Another is to file an election under section 83(b) through Form 15620 if the option price is no less than the underlying stock’s fair market value as of the date the stock option was granted.[2] This requires a specific form of appraisal known as a section 409A valuation. If executed correctly, the option’s owner will not be taxed on the stock purchased through the option’s exercise (although any subsequent sale of that stock would still be taxed). Someone who received a stock option with a fair market value of $1 per share for 1,000 shares in 2026 would recognize $1,000 in income. The same person striking that option would not include any income from that exercise even if the fair market value grew to $100 per share.

            Tax planning is usually circumstantial. If you receive a stock option for a corporation’s shares eligible under section 1202 for qualified small business stock treatment, you would probably benefit most by striking that option immediately because the 5-year holding period does not include stock options. However, if the corporation is ineligible under section 1202 and you want to wait to exercise your option, your best tax strategy may be to choose to be taxed on that option now, thereby avoiding the tax on the stock you purchase later. If you suspect that either opportunity is at hand, please call 916-822-8700 or email info@lawburton.com.


[1] IRC § 1202(e)(3).

[2] 26 CFR § 1.409A-1(b)(5).

Categories
News

The 2026 Billionaire Tax Act Part Five:

Enforcement, Credits, and Apportionment

Summary

Welcome to the fifth and final part of this series on Proposition 40, “The 2026 Billionaire Tax Act.”[1] This part discusses penalties, enforcement provisions, credits, and apportionment. The penalties are largely copied from the income tax law. Proposition 40 attempts to preempt avoidance attempts by delegating the Franchise Tax Board with extensive powers to generally disregard any transaction or series of transactions performed to escape this wealth tax. The credit and apportionment provisions contemplate constitutional challenges to Proposition 40, but generally place a heavy burden on any attempt for relief on constitutional grounds.

Penalties

In addition to any other penalty imposed by law, there would be a penalty of 20% for the “understatement of tax” in the event of a “substantial understatement” and a penalty of 40% of the “understatement of tax” in the event of a “gross understatement.”[2] An “understatement of tax” is defined as “ the amount by which the tax imposed by this part exceeds the amount of tax shown on an original return or shown on an amended return filed on or before the original or extended due date of the return for the taxable year.”[3] If the understated amount is more than the greater of $1 million or 20% of the tax shown on the return, the understatement is a “substantial understatement.”[4] If the understated amount is more than the greater of $10 million or 40% of the tax shown on the return, the understatement is a “gross understatement.”[5] However, these penalties “shall not apply to estimated payments required to be made by April 2027.”[6]

The FTB would be empowered to treat the appraiser as the taxpayer “[i]n the case of any underpayment of tax attributable to a substantial or gross overstatement or understatement of valuation in a certified appraisal,” and be penalized as if the appraiser were the taxpayer, except that the penalties would be 2% or 4% of the understatement of tax for substantial or gross overstatements or understatements respectively.[7]

The 2026 Billionaire Tax Act borrows the standard defenses to penalties from income tax law, including:

  • Changes in the law giving rise to the understatement.[8]
    • This “means a statutory change or an interpretation of law or rule of law by regulation or legal ruling of counsel, within the meaning of subdivision (b) of Section 11340.9 of the Government Code, or a published federal or California court decision.”[9]
  • Reasonable reliance on a legal ruling by the chief counsel of the Franchise Tax Board (akin to a Private Letter Ruling).[10]
  • “[S]ubstantial authority” for the treatment of the item giving rise to the understatement.[11]
  • “[R]easonable basis” for the treatment of the item giving rise to the understatement if there is adequate disclosure of the tax treatment.[12]

Administrative Procedures

Unless “inconsistent” with the 2026 Billionaire Tax Act (specifically, proposed RTC §§ 50308-50313), “the provisions for the administration, assessment, collection, enforcement, and appeals of the income tax shall apply to the taxation of net worth.”[13] The 2026 Billionaire Tax Act would exempt the Franchise Tax Board from the Administrative Procedure Act for rules and guidance regarding the 2026 Billionaire Tax Act until January 1, 2028.[14] The agency would be empowered to issue regulations regarding the 2026 Billionaire Tax Act, including (without limitation) regulations:[15]

  • “Identifying abusive transactions whose aim is to change the nature of an asset from public to nonpublic or vice versa.”
  • “Identifying abusive transactions whose aim is to artificially reduce the assessed value of a taxpayer’s assets.”

A separate section provides that the 2026 Billionaire Tax Act “shall be liberally construed to effectuate its purposes.”[16] The treatment of gifts is perhaps an exemplar of such purposes. Most substantial gifts will be included in net worth even if given before Proposition 40 comes into effect.[17] Proposition 40 anticipates taxpayers to take steps to avoid its tax. Similarly, an individual’s net worth will generally include their dependents’ net worth.[18]

            The 2026 Billionaire Tax Act would codify the economic substance doctrine regarding this new tax. That is, if “a transaction or series of transactions lack economic substance, or that a substantial purpose for any transaction or series of transactions was to obtain a tax benefit” under the 2026 Billionaire Tax Act “that is not intended by the voters or the Legislature, the Board may determine the tax consequences to any person in a manner that is reasonable in light of all the facts and circumstances in order to deny such benefit.”[19] Economic substance is determined by whether a person has “a valid and substantial nontax business purpose for entering into the transaction or series of transactions, taking into account the overall economic effect of the transaction or series of transactions apart from state and federal tax effects.”[20]

            The Franchise Tax Board would also be empowered to allocate tax items relevant to net worth “[i]n any case of two or more organizations, trades, businesses, entities, or arrangements owned or controlled, directly or indirectly, by the same interests” when “necessary in order to prevent avoidance of the tax imposed” by the 2026 Billionaire Tax Act “or clearly to reflect the economic ownership and enjoyment of such tax items.”[21] As part of this process, “the Board may disregard any entity, arrangement, or transaction that lacks economic substance, treat related transactions as a single transaction under the step transaction doctrine, or otherwise give effect to the substance rather than the form of the transaction.”[22] Furthermore, “legal principles developed with respect to interpretation and application of state and federal income taxes, including, without limitation, doctrines relating to economic substance, business purpose, sham transactions, step transactions, and substance over form” apply.[23]

Proposition 40 would “provide for expedited, conclusive resolution of the facial validity of this Act through a validation action.”[24] The deadline would be 60 days after Proposition 40 passes. “If no action is filed within that period, the tax and all proceedings in relation thereto, including the adoption and approval of the Act, shall be held to be facially valid and in every respect legal and incontestable.”[25] This would begin in the Superior Court for the County of Sacramento.[26] “Any appeal from an adverse determination in the Sacramento County Superior Court shall be directly to the California Supreme Court, without intermediate appellate review.”[27] Proposition 40 would give specific deadlines for these courts: “[T]he Sacramento Superior Court shall make every effort to resolve any validation action by April 1, 2027, and the California Supreme Court shall make every effort to resolve any review proceeding by November 1, 2027, or as soon as possible thereafter.”[28]

Credits

There are two credits under the 2026 Billionaire Tax Act:

  • A credit for other taxes on net wealth.[29]
    • This is “an amount equal to the taxpayer’s pro rata share of any taxes paid on a tax on net wealth that is also taxed under” the 2026 Billionaire Tax Act.
    • “[T]he pro rata share shall be the ratio in which the numerator shall be the total number of days the taxpayer resided within the other taxing state or jurisdiction and the denominator shall be 365.”
    • However, this credit does not account for “taxes on directly-held real property.”
  • “A credit shall additionally be allowed against taxes paid in other jurisdictions to the extent required by the U.S. Constitution.”[30]

Apportionment

            Generally, the Constitution requires a state’s tax on a nonresident to be apportioned based on that nonresident’s connection with the state. Proposition 40 provides for two forms of apportionment.  The standard apportionment preserves 100% of the wealth tax “without  reduction or multiplier based on residency history.”[31] However, “[i]f the standard apportionment method does not fairly represent the extent to which the taxpayer’s excessive wealth was accumulated in, or substantially sustained by, California, the taxpayer may petition for or the Board may require in a notice of proposed assessment, use of an alternative apportionment method for all or any part of the taxpayer’s wealth.”[32] This petition would be proved only if the taxpayer “proves by clear and convincing evidence that both of the following are true:”[33]

  • “The excessive wealth did not substantially accumulate in California.”
  • “The excessive wealth was not substantially sustained in California for at least 365 days in the aggregate” from January 1, 2025, through December 31, 2026.

In addition, “[t]he petitioning party bears the burden to show the standard method is unfair or invalid and to propose a more fair and reasonable method that is practicable to administer.”[34] If an alternative apportionment method were used, it would be applied before any credit is applied.[35]

The allocation percentage generally could not be lowered below 25%.[36] This limit could be overcome only if “Office of Tax Appeals ( or a court on review) finds on the record that a lower percentage is required to avoid grossly disproportionate taxation in violation of the United States or California Constitutions or governing federal law.”[37] This determination requires consideration of “whether the taxpayer’s net worth has a meaningful connection to California, and shall reduce the apportionment percentage, including below twenty-five percent and, where appropriate, to zero, to the extent necessary to avoid taxation that is arbitrary or out of all appropriate proportion to the taxpayer’s contacts with this State.”[38]


[1] Nothing should be construed as support of or opposition to Proposition 40 by the author or The Burton Law Firm. 

[2] Proposed RTC §§ 50312(c) & (d).

[3] Proposed RTC § 50312(c)(1).

[4] Proposed RTC § 50312(a).

[5] Proposed RTC § 50312(b).

[6] Proposed RTC § 50312(i).

[7] Proposed RTC § 50305(c).

[8] Proposed RTC § 50312(f).

[9] Proposed RTC § 50312(f)(2).

[10] Proposed RTC § 50312(g).

[11] Proposed RTC § 50312(h)(1).

[12] Proposed RTC § 50312(h)(2).

[13] Proposed RTC § 50309(d).

[14] Proposed RTC § 50309(b)(2).

[15] Proposed RTC § 50309(b)(1).

[16] Proposed RTC § 50313.

[17] “Net worth shall include the value of any property the individual transferred (other than property transferred to a trust described above) for less than fair market value after October 15, 2025, if such property either considered alone or together with other substantially interchangeable transferred items has a fair market value in excess of $1 million ($1,000,000). An asset included in the net worth of the transferor as a result of this subparagraph shall not be included in the net worth of the transferee.”  Proposed RTC § 50303(c)(11).

[18] “Any assets of a person who can be claimed as a dependent that are in excess of fifty thousand dollars ($50,000), shall be deemed to be assets of the taxpayer who can claim them as a dependent.” Proposed RTC § 50303(c)(12).

[19] Proposed RTC § 50312(k)(1).

[20] Proposed RTC § 50312(k)(2).

[21] Proposed RTC § 50312(l)(1).

[22] Proposed RTC § 50312(l)(2).

[23] Proposed RTC § 50312(m).

[24] Proposed RTC § 50314(a).

[25] Proposed RTC § 50314(c).

[26] Proposed RTC § 50314(d)(1).

[27] Proposed RTC § 50314(d)(2).

[28] Proposed RTC § 50314(d)(4).

[29] Proposed RTC § 50307(a).

[30] Proposed RTC § 50307(b).

[31] Proposed RTC § 50306(a).

[32] Proposed RTC § 50306(b)(2).

[33] Proposed RTC § 50306(b)(3).

[34] Proposed RTC § 50306(b)(5). Proposition 40 goes to some length describing the circumstance of the Franchise Tax Board being the petitioning party for an alternative method rather than the standard method. However, it is unclear why the Board would do so when the standard method makes the taxpayer liable for 100% of the tax. Proposed RTC § 50306(b)(5).

[35] Proposed RTC § 50306(b)(2).

[36] Proposed RTC § 50306(b)(6).

[37] Id.

[38] Id.

Categories
News

“Just Compensation”: A Contextual Term

Introduction

Pung v. Isabella County is the sequel to the 2023 Supreme Court case Tyler v. Hennepin County. In a foreclosure for a defaulted property tax debt, Tyler held that the Takings Clause requires the government to remit the surplus of foreclosure proceeds over the tax debt. Now, Pung addresses how to measure that surplus. It is simply the difference between the tax debt and the foreclosure proceeds, regardless of the fair market value.

In 2015, Isabella County, Michigan, foreclosed a home for a $2,241.93 property tax debt after lengthy litigation. The home was purchased in 1991 for $125,000. It was assessed at $194,400 at the time of foreclosure, and it was resold about 18 months later by the purchaser for $195,000. However, the property was sold at the foreclosure auction for only $76,008, and Isabella County kept all proceeds. The taxpayer sued for the excess of the fair market value over the debt. The District Court granted the difference between the auction price and the tax debt, but denied the claim regarding the fair market value. The 6th Circuit confirmed in an unpublished opinion.

What is Just?

History predetermined the Supreme Court’s ruling. “[F]or hundreds of years, English and American law have allowed the seizure and sale of property as a tax-collection method, provided that the government return any surplus proceeds to the debtor.”[1] Throughout that time, the surplus has been measured as “the sale price, not the property’s hypothetical fair market value.”[2] “[A]t least when the sale is fairly conducted in light of our country’s history of tax sales,” that constitutes “just compensation.”[3] The Court did not examine whether the sale reflects the fair market value. Unquestionably, “the fair market value is the default measure of ‘just compensation’” in eminent domain cases.[4] Yet, even then, “there are situations where this standard is inappropriate” as when the fair market value is “too difficult to find, or when its application would result in manifest injustice to owner or public.”[5] “Just” is a relative construct.  “[W]hat is ‘just’ in one context may not be ‘just’ in another.”[6] The Court noted that a property owner facing foreclosure could obtain a loan to pay the taxes or sell the property themselves. “Here, the Pungs had years to take these steps and avoid foreclosure.  They failed to do so. In such a situation, the traditional rule, under which the taxpayer receives only the difference between the auction sale price and unpaid taxes, is ‘just.’”[7]

“[T]ax sales are designed to collect unpaid taxes without undue delay and administrative expense,” resulting in suboptimal prices.[8] The alternative “would impose unprecedented burdens on jurisdictions that wish to collect unpaid taxes and might well make tax sales impractical.”[9] Real property sales are time-consuming, costly, and risky. The Court warned that governments would likely need to pay the taxpayer in many situations. “The possibility of such a perverse result would render tax sales infeasible as a debt-collection mechanism,” despite acknowledging that some states do so earlier.[10]  Moreover, governments “might well compensate for this lost revenue by increasing the burden on residents who do pay their taxes.”[11] Therefore, tax sales actually benefit taxpayers as a whole.

The Court disclaimed that “[o]ur task in this case, however, is not to decide whether tax sales as historically conducted represent good public policy.”[12] The fact that such tax sales are historically entrenched decides the matter. “If the Takings Clause had been understood to impose restrictions that rendered these sales untenable, they would have presumably faded away, at least after the Fourteenth Amendment incorporated the Takings Clause against the States.”[13] Any interpretation that is contrary to historical practices will likely be poorly received. “That Pung’s novel interpretation of the Takings Clause would whisk this longstanding practice into the dust bin is strong evidence that his interpretation is incorrect.”[14]

The Court dismissed the taxpayer’s arguments regarding the procedure of the sale and the county’s choice to forsake lesser alternatives to foreclosure because they were not part of the question presented before the Court. In contrast, the taxpayer’s Eighth Amendment argument was properly presented to the Court. Nevertheless, the Court’s response to the taxpayer’s claim that the sale amounted to an “excessive fine” was quite brief. It acknowledged that “[f]orfeiture of property can be a fine for purposes of the Eighth Amendment if it serves in part to punish,” but “historical practice” influences this analysis.[15]  Here, the taxpayer’s Eighth Amendment argument fails for the same reason as the Fifth Amendment fails. It “lacks historical or precedential support.”[16] Like the “Fifth Amendment theory,” this would also mean “the demise of this country’s longstanding use of tax sales to collect debts.”[17] There was not any further explanation. Unfortunately, the Court did not indicate whether the tax sale constituted a fine or, if so, why it is not excessive.

A Concurring Dissent

According to the Court: “The Pung family lost its property because it failed to pay its taxes.”[18] However, Justice Thomas highlighted details revealing a more nuanced scenario. Pung was unanimously decided with two concurrences, technically speaking. Justice Sotomayor, joined by Justice Gorsuch and Justice Jackson, wrote a brief opinion emphasizing that the Court’s opinion does not have any implications for “identifying the contours of a fair auction.”[19] In contrast, Justice Thomas’s opinion was longer than the Court’s opinion. Although he joined all but one section of the majority opinion, Justice Thomas’s concurrence was more of a dissent.[20] Justice Thomas, joined by Justice Gorsuch, agreed that history determines the constitutionality of tax sales, but differed as to what that history is, concluding that “[w]hat Isabella County did to the Pungs was wrong, and, on my initial view, likely unconstitutional.”[21] He emphasized the peculiarities of the underlying tax debt. There was extensive litigation on the merits of the tax debt, which the taxpayer won. “The tax assessor, however, chose to not respect the court’s decision. ‘I don’t care what he says,’ she said of the judge who ruled for the Pungs.”[22] Indeed, “[w]hen asked at oral argument, the County’s attorney stated: ‘I don’t know what the township assessor’s reasoning was.’”[23]

Justice Thomas argued that the two prior exceptions the Court’s opinion recognized for the fair market value were the only two before this case. Neither applies here. “It is not too difficult to find the market value of an ordinary suburban home; the County already did so in assessing the amount of the tax that the Pungs owed. Likewise, there is no injustice, let alone manifest injustice, in paying the Pungs in full for their home.”[24] He agreed that history justifies the new third exception, “[b]ut, any exception based on history can be no broader than what that history justifies.”[25] Justice Thomas stressed that historically, courts held tax foreclosure sales to strict standards that were not met here. For example, the personal property needed to be seized before the real property could be taken. As for the argument that requiring foreclosure sales to be for fair market value hinders government operations, “that is the point of the Takings Clause, which necessarily prioritizes homeowners’ property rights over the government’s interest in efficiency and public necessity.”[26] Moreover, the government’s interest is to preserve property rights. “The government exists to protect property; property does not exist to support the government.”[27] Despite “concurring,” Justice Thomas seemingly disagreed with the Court’s ruling. Perhaps surprisingly, he did not comment on the Eighth Amendment issue.

Conclusion

It appears there will be a trilogy of tax sale cases. In 2023, Tyler v. Hennepin County held that the surplus of the sale must be given, and in 2026, Pung v. Isabella County explained how the surplus is measured. Yet it explicitly left questions of procedural sufficiency for the tax sale unanswered.


[1] Pung v. Isabella Cty., 146 S. Ct. 1964, 1969 (2026).

[2] Id. at 1970.

[3] Id.

[4] Id.

[5] Id. at 1971.

[6] Id. at 1970.

[7] Id. at 1971.

[8] Id.

[9] Id.

[10] Id. at 1972. On the previous page, the Court noted in a footnote that “various States have enacted regimes that require these kinds of choices” that incorporate fair market value, but it is inappropriate “for this Court to impose such a regime as a matter of constitutional law.” Id. at 1971.

[11] Id. at 1972.

[12] Id.

[13] Id.

[14] Id.

[15] Id. at 1973.

[16] Id.

[17] Id.

[18] Id.

[19] Id.(J. Sotomayor concurring).

[20]  “I join the Court’s opinion as to all but Part II–B because I agree that the auction surplus from a tax foreclosure sale can constitute just compensation if it is consistent with historical practice, and because I agree that the parties should have the opportunity to litigate below whether the local government’s conduct here was consistent with that practice.” Id. at 1974, fn.1(J. Thomas concurring).

[21] Id. at 1981(J. Thomas concurring).

[22] Id. at 1975(J. Thomas concurring).

[23] Id.(J. Thomas concurring).

[24] Id. at 1978(J. Thomas concurring)(omitting internal quotation marks).

[25] Id. at 1979(J. Thomas concurring).

[26] Id. at 1981(J. Thomas concurring).

[27] Id.(J. Thomas concurring).

Categories
News

ADA and Website Accessibility

The Americans with Disabilities Act (ADA) generally requires publicly accessible businesses to be accessible to individuals with disabilities. Wheelchair ramps are perhaps the most visible feature required by the ADA, but less tangible accommodations are necessary, too. Courts have adapted this 1990 law to 21st-century needs by requiring many websites to be accessible to people with visual impairments and other disabilities.[1] This does not bind every website, but any establishment subject to the ADA’s physical mandates must comply with the ADA’s virtual mandates.[2]  

Unfortunately, there is not an official standard for private actors.[3] However, courts often use adherence to the Web Content Accessibility Guidelines (WCAG) promulgated by the World Wide Web Consortium to measure ADA compliance. “A failure to comply with WCAG may not be dispositive of ADA non-compliance, but compliance with this common accessibility standard is certainly helpful and informative in that respect.”[4] Consequently, it is often unclear what exactly is required for minimum accessibility under the ADA, but WCAG conformity can serve as a safe harbor. The latest standard is WCAG 2.2, which urges websites to be:

  • Perceivable: “Information and user interface components must be presentable to users in ways they can perceive.”
    • For example, all content (such as images) should have text alternatives.
  • Operable: “User interface components and navigation must be operable.”
    • As one application, all functionality should be performable through a keyboard alone.
  • Understandable: “Information and the operation of the user interface must be understandable.”
    • For instance, “[i]f an input error is automatically detected, the item that is in error is identified and the error is described to the user in text.”
  • Robust: “Content must be robust enough that it can be interpreted by a wide variety of user agents, including assistive technologies.”
    • Specifically, the website should be compatible with screen readers.

If there is good news for a defendant in ADA litigation, it is that the lawsuit can be mooted. “Courts routinely declare ADA access claims are moot when defendants modify noncompliant items.”[5] This may be difficult when the demands are on physical architecture, but it may be easier for simpler websites. Nevertheless, detecting WCAG compliance is a technical skill in and of itself. While there are automated detectors, a human-based determination is necessary to be certain. The Burton Law Firm does not endorse any vendor or particular method for either WCAG compliance detection or remediation. Nevertheless, the California Department of Rehabilitation has a list of potential vendors, many of which have been used by the state of California, and a few to an extensive degree. Of course, the Department of Rehabilitation also disclaims any recommendation or endorsement, even for these much-used vendors.


[1] Robles v. Domino’s Pizza, LLC, 913 F.3d 898 (9th Cir. 2019).

[2] Robles v. Domino’s Pizza, LLC, 913 F.3d 898, 905 (9th Cir. 2019).

[3] There is for state and local government entities, though. This uses WCAG 2.1, buttressing its role as a safe harbor for the private sector.

[4] Merrell v. Ralph Lauren Corp., No. 23-cv-06669-HSG, 2026 U.S. Dist. LEXIS 152333, at *19 (N.D. Cal. July 9, 2026).

[5] Merrell v. Tapestry Inc., No. 5:25-cv-02510-RGK-MAR, 2026 U.S. Dist. LEXIS 150519, at *7-8 (C.D. Cal. May 12, 2026).