Expert Counsel. Exceptional Solutions.

+1 (916) 822-8700

Categories
News

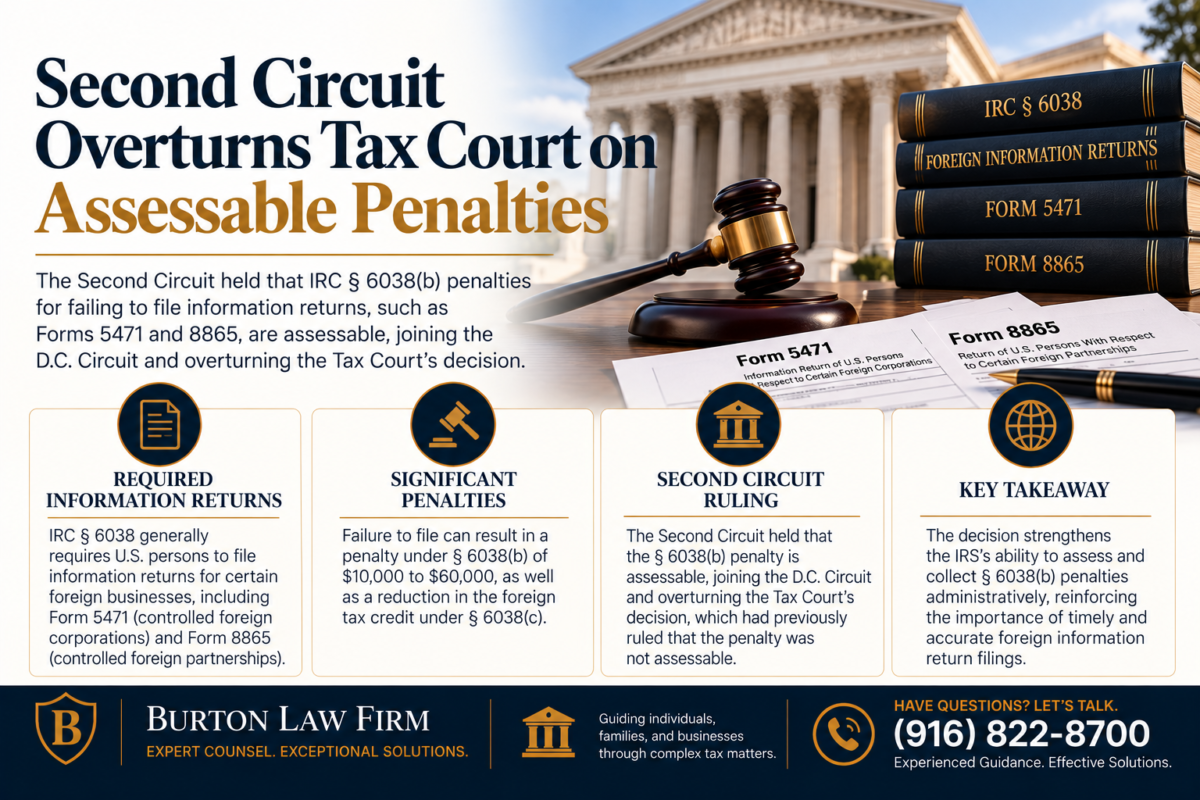
Second Circuit Overturns Tax Court on Assessable Penalties

Section 6038 generally requires a U.S. person to file an information return regarding each foreign business the U.S. person controls. For example, Form 5471 is for controlled foreign corporations, and Form 8865 is for controlled foreign partnerships. Failing to file incurs two penalties. One (§ 6038(b)) charges a minimum of $10,000 and a maximum of $60,000 if not cured.[1] The other (§ 6038(c)) reduces the foreign tax credit by a minimum of 10% and a maximum of 100% if not cured, but this is reduced by the amount of the other penalty.[2]

Normally, a creditor must sue in a court of law to collect a debt. There is an exception for one of the most common debts, the income tax. Then, “[o]nly in rare instances is a lawsuit necessary. The agency can instead usually collect taxpayers’ liabilities through ‘assessment.’”[3] An assessment “allow[s] the IRS to seize assets, freeze bank accounts, and create liens—all without setting foot in a courtroom.”[4] This can be contested, but only on the taxpayer’s initiative. A private creditor sues to collect a debt, and a taxpayer sues for a tax not to be collected.

Safdieh v. Commissioner

In Safdieh v. Commissioner, the taxpayer failed to file under § 6038 for the 2005-2009 tax years. The penalties totaled $50,000. The question is whether this can be assessed. This was first answered by the Tax Court in 2023 through Farhy v. Commissioner.[5] There, the Tax Court ruled that § 6038(b) is not an assessable penalty. However, the D.C. Circuit reversed the Tax Court, holding that § 6038(b) is an assessable penalty.[6] This did not settle the matter outside of the D.C. Circuit. Another § 6038(b) case arose, and the Tax Court clarified in Mukhi v. Commissioner that it will follow its original Farhy reasoning outside of the D.C. Circuit.[7] The Tax Court repeated this policy in subsequent decisions, including Safdieh v. Commissioner.[8] The 2nd Circuit joined the D.C. Circuit in overruling the Tax Court in this matter.

Section 6038(b) does not explain whether the penalty is assessable. “Despite the parties’ attempts at exegesis, the text simply does not say whether the penalty is, or is not, assessable.”[9] Nevertheless, the 2nd Circuit found three reasons why the penalty is assessable. The first is through legislative history, the second is the statutory purpose, and the third is the placement of statutory language in the United States Code.

The penalty in question was enacted in 1982. The accompanying Senate report explained that the existing penalty (regarding the foreign tax credit) is insufficient for multiple reasons, including its complexity. To the 2nd Circuit, this makes the decision to make the new penalty nonassessable “implausible”: “It is unlikely that Congress would have wished to put even more logs in the way of the tax harvester when its stated aim was to clear the road.”[10] Specifically, “[t]he Committee Print indicates that the fixed dollar penalty was meant to ‘simplify the penalty for failure to furnish information’ by ‘giv[ing] Internal Revenue Service agents a simple straight-forward penalty to impose where reports . . . are not filed or are inadequate.’”[11] Requiring the IRS to go to the Justice Department to go to a district court would not accomplish that mission of simplicity. The IRS has assessed the penalty since its enactment. “As evidence of the statute’s original meaning, it deserves substantial weight.”[12] This is distinct from deferring to the IRS, the 2nd Circuit argued. Furthermore, Congress knowingly acquiesced in this practice of assessment.  The Federal Courts Improvement Act was also enacted in the same year as the penalty for the purpose of decreasing the caseload of the district courts. It would be illogical for the same Congress to increase the caseload. Furthermore, the threshold for diversity jurisdiction was ten times the original § 6038(b) penalty amount. “Saddling the Commissioner with a federal case over such a small sum would hamper the federal courts and the Commissioner at a time when the evidence suggests that Congress wished to relieve both.”[13]

Section 6038(c)(3) coordinates the two § 6038 penalties by providing that the § 6038(c) penalty regarding the foreign tax credit is decreased by the amount of the § 6038(b) penalty. To the 2nd Circuit, this was ample proof that the two penalties were intended to be assessed in tandem. Diverging the two penalties would result in gross inefficiency. “We give Congress more credit than that.”[14] Due to this dissonance “parties may try to game the proceedings by rushing to judgment in the ‘right’ court and erecting barriers to judgment in the ‘wrong’ one.”[15]

The taxpayer claimed that 28 U.S.C. § 2461(a) is the Commissioner’s sole authority to collect the penalty. This is not in the Internal Revenue Code, which was determinative for the 2nd Circuit. “Even more revealingly, in the thirty-four years between this provision’s enactment in 1948 and the dollar penalty’s enactment in 1982, the provision was never used to collect a tax or tax penalty.”[16]

Farhy & Mukhi

            The Tax Court’s theory, as articulated in Farhy v. Commissioner and Mukhi v. Commissioner, was left entirely unmentioned. Consequently, it is unlikely that the Tax Court will change its mind after Safdieh when it declined to do so in Mukhi v. Commissioner after the D.C. Circuit Court overturned the Tax Court in Farhy v. Commissioner.

The Tax Court premised its analysis in both Farhy and Mukhion on a Supreme Court quote, “[a]gencies have only those powers given to them by Congress.”[17] This was unmentioned by the 2nd Circuit Court. To the Tax Court, the IRC simply did not designate the penalties as “assessable” and therefore they were not assessable. It refused to “infer[] the power to administratively assess and collect the section 6038(b) penalties when Congress did not see fit to grant that power to the Secretary of the Treasury expressly as it did for other penalties in the Code.”[18] Even if the legislative history indicated otherwise, it cannot overcome the plain (lack of) language in the statute. “The text is clear, and therefore we need not consider legislative history to attempt to ascertain Congress’s intentions.”[19] In any case, the Tax Court was unimpressed with the passage that so moved the circuit courts. “We will not read a passing statement about the complicated nature of a penalty as empowering the IRS to assess a different penalty.”[20]

Ultimately, the Tax Court considers appellate decisions by courts other than the Supreme Court as essentially optional to follow. “The Tax Court adheres to the doctrine of stare decisis” and “takes seriously its obligation to facilitate uniformity in the tax law” as a nationwide court.[21] “When one of our decisions is reversed by an appellate court, the Court will thoroughly reconsider the problem in the light of the reasoning of the reversing appellate court and, if convinced thereby, follow the higher court.”[22] Yet if “convinced that our original decision was right, the proper course is to follow our own honest beliefs until the Supreme Court decides the point.”[23] Nevertheless it will follow a contrary appellate decision when both the decision is “squarely on point” and an appeal from the Tax Court would rest in the circuit court that issued the contrary decision.[24] “To do otherwise would be futile and wasteful given the inevitable reversal from the appellate court.”[25]

If you were assessed with a penalty for failing to file Form 5471, Form 8865, or another IRS form, please call 916-822-8700 or email info@lawburton.com.


[1] IRC § 6038(b). The minimum penalty is $10,000, with another $10,000 charged for each 30-day period (up to $50,000) after 90 days from the day the IRS mails notice of the failure to file to the taxpayer.

[2] § 6038(c). Similar to the other penalty, the foreign tax credit reduction starts at 10% and is further reduced by 5% for each additional 3-month period that the taxpayer does not file after 90 days from the day that notice of the failure to file is mailed by the IRS to the taxpayer.

[3] Safdieh v. Comm’r, 2026 U.S. App. LEXIS 5796, *3.

[4] Id. at *4.

[5] 160 T.C. 399 (2023), rev’d and remanded, 100 F.4th 223 (D.C. Cir. 2024).

[6] Farhy v. Comm’r of IRS, 100 F.4th 223 (2024).

[7] 163 T.C. 150 (2024).

[8] Safdieh v. Commissioner, No. 11680-20L, 2024 U.S. Tax Ct. LEXIS 3021 (T.C. Dec. 5, 2024); Cauchon v. Commissioner, No. 23863-22L, 2025 U.S. Tax Ct. LEXIS 405 (T.C. Feb. 14, 2025).

[9] Safdieh v. Comm’r, 2026 U.S. App. LEXIS 5796, *5 fn.18.

[10] Id. at *7.

[11] Id. at *7 fn.29.

[12] Id. at *7.

[13] Id. at *9.

[14] Id. at *11.

[15] Id. at *12.

[16] Id. at *13.

[17] Farhy v. Commissioner, 160 T.C. 399, 404 (2023)(quoting West Virginia v. EPA, 597 U.S. 697, 723 (2022)); Mukhi v. Commissioner, 163 T.C. 150, 156 (2024)(quoting West Virginia v. EPA, 597 U.S. 697, 723 (2022)).

[18] Farhy v. Commissioner, 160 T.C. 399, 406 (2023).

[19] Mukhi v. Commissioner, 163 T.C. 150, 160 (2024).

[20] Id. at 165..

[21] Id. at 154 (2024).

[22] Id.(omitting internal quotation mark and ellipsis).

[23] Id.(omitting internal quotation mark and brackets).

[24] Id.(omitting internal brackets).

[25] Id.(omitting internal quotation marks).
Categories
News

Chinese Taxation of Offshore Trusts

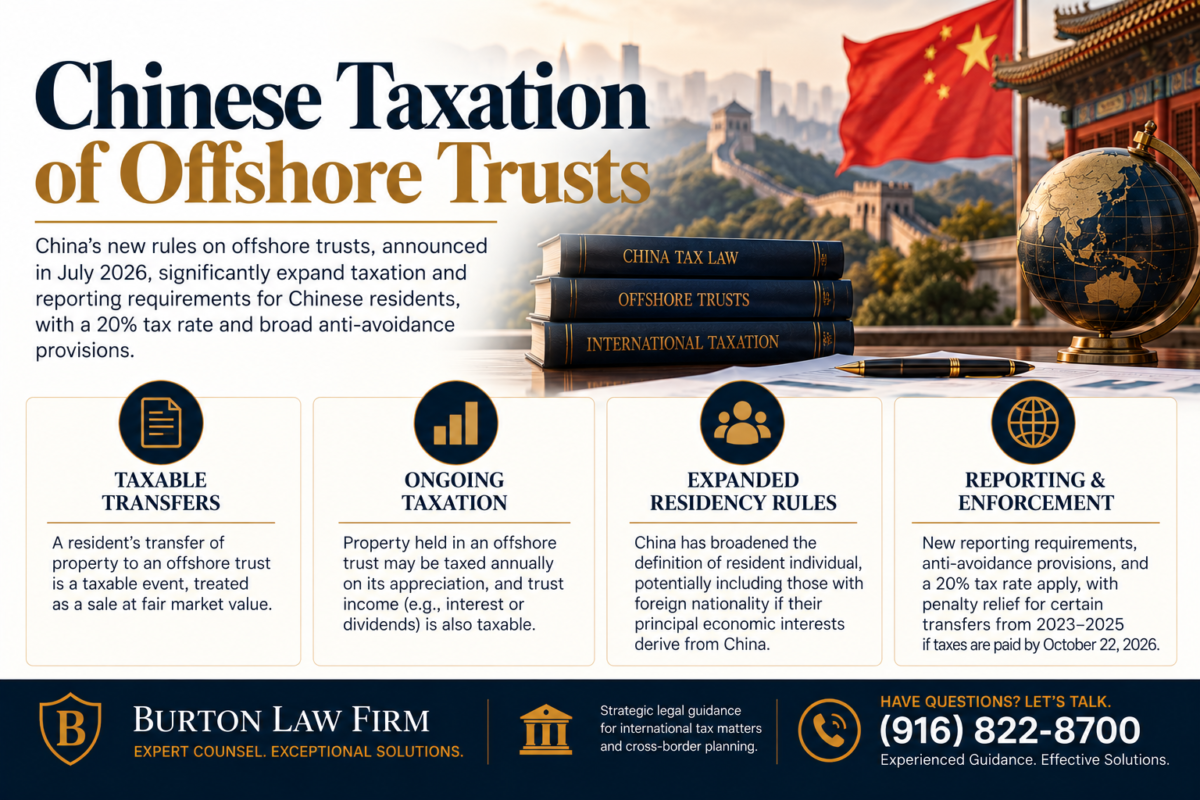
Chinese residents are taxed on their worldwide income by China. Nonresidents are taxed by China only on income sourced to China. Offshore trusts have become a popular means amongst wealthy Chinese to avoid the income tax. On July 24, 2026, China suddenly announced new rules for offshore trusts to stop this avoidance. These came in the form of Announcement 15 and Announcement 21 by the State Taxation Administration.[1] Announcement 21 provides most of the substantive rules, while Announcement 15 is primarily concerned with reporting obligations. These are short documents. Announcement 21 is only 5 pages long, while Announcement 15 is only 4 pages long.

In general, a resident’s transfer of property to an offshore trust is a taxable event as if it were sold for fair market value. For each year that the property is in an offshore trust under the resident’s control, the property is taxed on its appreciation, even if it was not sold or distributed. “Losses may not be carried forward to offset income in subsequent years.”[2] Any income from the offshore trust property, such as interest or dividends, is also taxed. If the offshore trust property is distributed to a resident, the resident must pay a tax on the property’s value to the extent such value was not already taxed by the trust grantor. If the resident becomes a nonresident, the property is taxed as if it were sold. If more than one resident contributes property to an offshore trust, each resident is taxed on the proportionate share of the property they contributed to the entirety of the offshore trust’s property. A nonresident’s transfer of property to an offshore trust is taxed only to the extent that the property is sourced to China. The tax rate is 20% throughout this process.

An “offshore trust” is defined as “a trust or other legal arrangement having trust functions established under the laws of a jurisdiction outside China.”[3] However, this definition “excludes financial products issued by banks, insurance companies, securities companies, fund companies, and similar institutions that are regulated by the financial regulatory authorities of the countries or regions in which they are located and that independently conduct business with an unspecified clientele and bear the associated risks.”[4] A transfer to an offshore trust is taxed on “the property’s market value, less its original value and reasonable expenses.”[5] The term “reasonable expenses” is undefined. Indirect transfers are also included in these rules. “Where an individual transfers property through another individual or organization, and the individual actually funds, bears the cost of, and controls that property, the individual shall be deemed to have acquired and contributed the property.”[6] Notably, the term “controls” is undefined. However, “[w]here an offshore trust to which a nonresident individual has contributed property distributes income to a nonresident individual, but another resident individual actually receives, uses, controls, or disposes of that income, the offshore trust shall be deemed to have distributed the income to that resident individual.”[7] China expanded the category of residents for these purposes. “An individual who has acquired foreign nationality or long-term or permanent residence rights outside China, but whose principal economic interests derive from within China, may be determined to be a resident individual domiciled in China.”[8]

These announcements are retroactive to an unknown degree. Although they claim to be effective immediately (July 24, 2026), there is a provision waiving penalties for unpaid tax liabilities arising from these new rules from transfers to offshore trusts from January 1, 2023, to December 31, 2025, if paid by October 22, 2026. The announcements are technically interpretations of existing law rather than the proclamation of a new law. It is theoretically possible that these rules apply to offshore trust transfers before 2023.

Separately, China announced that it “will impose a 20 percent individual income tax on dividends and bonuses that foreign individuals receive from foreign-invested enterprises starting September 1.” The “temporary exemption” in place since 1994 is now over.


[1] Unfortunately, neither of them appears to have an official English translation.

[2] Announcement No. 21, § 4(unofficial translation).

[3] Id. at § 1(unofficial translation).

[4] Id.(unofficial translation).

[5] Id. at § 4(unofficial translation).

[6] Id. at § 2(unofficial translation).

[7] Id. at § 8(unofficial translation).

[8] Id. at § 11(unofficial translation).

Categories
News

The 2026 Billionaire Tax Act Part Five:

Enforcement, Credits, and Apportionment

Summary

Welcome to the fifth and final part of this series on Proposition 40, “The 2026 Billionaire Tax Act.”[1] This part discusses penalties, enforcement provisions, credits, and apportionment. The penalties are largely copied from the income tax law. Proposition 40 attempts to preempt avoidance attempts by delegating the Franchise Tax Board with extensive powers to generally disregard any transaction or series of transactions performed to escape this wealth tax. The credit and apportionment provisions contemplate constitutional challenges to Proposition 40, but generally place a heavy burden on any attempt for relief on constitutional grounds.

Penalties

In addition to any other penalty imposed by law, there would be a penalty of 20% for the “understatement of tax” in the event of a “substantial understatement” and a penalty of 40% of the “understatement of tax” in the event of a “gross understatement.”[2] An “understatement of tax” is defined as “ the amount by which the tax imposed by this part exceeds the amount of tax shown on an original return or shown on an amended return filed on or before the original or extended due date of the return for the taxable year.”[3] If the understated amount is more than the greater of $1 million or 20% of the tax shown on the return, the understatement is a “substantial understatement.”[4] If the understated amount is more than the greater of $10 million or 40% of the tax shown on the return, the understatement is a “gross understatement.”[5] However, these penalties “shall not apply to estimated payments required to be made by April 2027.”[6]

The FTB would be empowered to treat the appraiser as the taxpayer “[i]n the case of any underpayment of tax attributable to a substantial or gross overstatement or understatement of valuation in a certified appraisal,” and be penalized as if the appraiser were the taxpayer, except that the penalties would be 2% or 4% of the understatement of tax for substantial or gross overstatements or understatements respectively.[7]

The 2026 Billionaire Tax Act borrows the standard defenses to penalties from income tax law, including:

  • Changes in the law giving rise to the understatement.[8]
    • This “means a statutory change or an interpretation of law or rule of law by regulation or legal ruling of counsel, within the meaning of subdivision (b) of Section 11340.9 of the Government Code, or a published federal or California court decision.”[9]
  • Reasonable reliance on a legal ruling by the chief counsel of the Franchise Tax Board (akin to a Private Letter Ruling).[10]
  • “[S]ubstantial authority” for the treatment of the item giving rise to the understatement.[11]
  • “[R]easonable basis” for the treatment of the item giving rise to the understatement if there is adequate disclosure of the tax treatment.[12]

Administrative Procedures

Unless “inconsistent” with the 2026 Billionaire Tax Act (specifically, proposed RTC §§ 50308-50313), “the provisions for the administration, assessment, collection, enforcement, and appeals of the income tax shall apply to the taxation of net worth.”[13] The 2026 Billionaire Tax Act would exempt the Franchise Tax Board from the Administrative Procedure Act for rules and guidance regarding the 2026 Billionaire Tax Act until January 1, 2028.[14] The agency would be empowered to issue regulations regarding the 2026 Billionaire Tax Act, including (without limitation) regulations:[15]

  • “Identifying abusive transactions whose aim is to change the nature of an asset from public to nonpublic or vice versa.”
  • “Identifying abusive transactions whose aim is to artificially reduce the assessed value of a taxpayer’s assets.”

A separate section provides that the 2026 Billionaire Tax Act “shall be liberally construed to effectuate its purposes.”[16] The treatment of gifts is perhaps an exemplar of such purposes. Most substantial gifts will be included in net worth even if given before Proposition 40 comes into effect.[17] Proposition 40 anticipates taxpayers to take steps to avoid its tax. Similarly, an individual’s net worth will generally include their dependents’ net worth.[18]

            The 2026 Billionaire Tax Act would codify the economic substance doctrine regarding this new tax. That is, if “a transaction or series of transactions lack economic substance, or that a substantial purpose for any transaction or series of transactions was to obtain a tax benefit” under the 2026 Billionaire Tax Act “that is not intended by the voters or the Legislature, the Board may determine the tax consequences to any person in a manner that is reasonable in light of all the facts and circumstances in order to deny such benefit.”[19] Economic substance is determined by whether a person has “a valid and substantial nontax business purpose for entering into the transaction or series of transactions, taking into account the overall economic effect of the transaction or series of transactions apart from state and federal tax effects.”[20]

            The Franchise Tax Board would also be empowered to allocate tax items relevant to net worth “[i]n any case of two or more organizations, trades, businesses, entities, or arrangements owned or controlled, directly or indirectly, by the same interests” when “necessary in order to prevent avoidance of the tax imposed” by the 2026 Billionaire Tax Act “or clearly to reflect the economic ownership and enjoyment of such tax items.”[21] As part of this process, “the Board may disregard any entity, arrangement, or transaction that lacks economic substance, treat related transactions as a single transaction under the step transaction doctrine, or otherwise give effect to the substance rather than the form of the transaction.”[22] Furthermore, “legal principles developed with respect to interpretation and application of state and federal income taxes, including, without limitation, doctrines relating to economic substance, business purpose, sham transactions, step transactions, and substance over form” apply.[23]

Proposition 40 would “provide for expedited, conclusive resolution of the facial validity of this Act through a validation action.”[24] The deadline would be 60 days after Proposition 40 passes. “If no action is filed within that period, the tax and all proceedings in relation thereto, including the adoption and approval of the Act, shall be held to be facially valid and in every respect legal and incontestable.”[25] This would begin in the Superior Court for the County of Sacramento.[26] “Any appeal from an adverse determination in the Sacramento County Superior Court shall be directly to the California Supreme Court, without intermediate appellate review.”[27] Proposition 40 would give specific deadlines for these courts: “[T]he Sacramento Superior Court shall make every effort to resolve any validation action by April 1, 2027, and the California Supreme Court shall make every effort to resolve any review proceeding by November 1, 2027, or as soon as possible thereafter.”[28]

Credits

There are two credits under the 2026 Billionaire Tax Act:

  • A credit for other taxes on net wealth.[29]
    • This is “an amount equal to the taxpayer’s pro rata share of any taxes paid on a tax on net wealth that is also taxed under” the 2026 Billionaire Tax Act.
    • “[T]he pro rata share shall be the ratio in which the numerator shall be the total number of days the taxpayer resided within the other taxing state or jurisdiction and the denominator shall be 365.”
    • However, this credit does not account for “taxes on directly-held real property.”
  • “A credit shall additionally be allowed against taxes paid in other jurisdictions to the extent required by the U.S. Constitution.”[30]

Apportionment

            Generally, the Constitution requires a state’s tax on a nonresident to be apportioned based on that nonresident’s connection with the state. Proposition 40 provides for two forms of apportionment.  The standard apportionment preserves 100% of the wealth tax “without  reduction or multiplier based on residency history.”[31] However, “[i]f the standard apportionment method does not fairly represent the extent to which the taxpayer’s excessive wealth was accumulated in, or substantially sustained by, California, the taxpayer may petition for or the Board may require in a notice of proposed assessment, use of an alternative apportionment method for all or any part of the taxpayer’s wealth.”[32] This petition would be proved only if the taxpayer “proves by clear and convincing evidence that both of the following are true:”[33]

  • “The excessive wealth did not substantially accumulate in California.”
  • “The excessive wealth was not substantially sustained in California for at least 365 days in the aggregate” from January 1, 2025, through December 31, 2026.

In addition, “[t]he petitioning party bears the burden to show the standard method is unfair or invalid and to propose a more fair and reasonable method that is practicable to administer.”[34] If an alternative apportionment method were used, it would be applied before any credit is applied.[35]

The allocation percentage generally could not be lowered below 25%.[36] This limit could be overcome only if “Office of Tax Appeals ( or a court on review) finds on the record that a lower percentage is required to avoid grossly disproportionate taxation in violation of the United States or California Constitutions or governing federal law.”[37] This determination requires consideration of “whether the taxpayer’s net worth has a meaningful connection to California, and shall reduce the apportionment percentage, including below twenty-five percent and, where appropriate, to zero, to the extent necessary to avoid taxation that is arbitrary or out of all appropriate proportion to the taxpayer’s contacts with this State.”[38]


[1] Nothing should be construed as support of or opposition to Proposition 40 by the author or The Burton Law Firm. 

[2] Proposed RTC §§ 50312(c) & (d).

[3] Proposed RTC § 50312(c)(1).

[4] Proposed RTC § 50312(a).

[5] Proposed RTC § 50312(b).

[6] Proposed RTC § 50312(i).

[7] Proposed RTC § 50305(c).

[8] Proposed RTC § 50312(f).

[9] Proposed RTC § 50312(f)(2).

[10] Proposed RTC § 50312(g).

[11] Proposed RTC § 50312(h)(1).

[12] Proposed RTC § 50312(h)(2).

[13] Proposed RTC § 50309(d).

[14] Proposed RTC § 50309(b)(2).

[15] Proposed RTC § 50309(b)(1).

[16] Proposed RTC § 50313.

[17] “Net worth shall include the value of any property the individual transferred (other than property transferred to a trust described above) for less than fair market value after October 15, 2025, if such property either considered alone or together with other substantially interchangeable transferred items has a fair market value in excess of $1 million ($1,000,000). An asset included in the net worth of the transferor as a result of this subparagraph shall not be included in the net worth of the transferee.”  Proposed RTC § 50303(c)(11).

[18] “Any assets of a person who can be claimed as a dependent that are in excess of fifty thousand dollars ($50,000), shall be deemed to be assets of the taxpayer who can claim them as a dependent.” Proposed RTC § 50303(c)(12).

[19] Proposed RTC § 50312(k)(1).

[20] Proposed RTC § 50312(k)(2).

[21] Proposed RTC § 50312(l)(1).

[22] Proposed RTC § 50312(l)(2).

[23] Proposed RTC § 50312(m).

[24] Proposed RTC § 50314(a).

[25] Proposed RTC § 50314(c).

[26] Proposed RTC § 50314(d)(1).

[27] Proposed RTC § 50314(d)(2).

[28] Proposed RTC § 50314(d)(4).

[29] Proposed RTC § 50307(a).

[30] Proposed RTC § 50307(b).

[31] Proposed RTC § 50306(a).

[32] Proposed RTC § 50306(b)(2).

[33] Proposed RTC § 50306(b)(3).

[34] Proposed RTC § 50306(b)(5). Proposition 40 goes to some length describing the circumstance of the Franchise Tax Board being the petitioning party for an alternative method rather than the standard method. However, it is unclear why the Board would do so when the standard method makes the taxpayer liable for 100% of the tax. Proposed RTC § 50306(b)(5).

[35] Proposed RTC § 50306(b)(2).

[36] Proposed RTC § 50306(b)(6).

[37] Id.

[38] Id.

Categories
News

“Just Compensation”: A Contextual Term

Introduction

Pung v. Isabella County is the sequel to the 2023 Supreme Court case Tyler v. Hennepin County. In a foreclosure for a defaulted property tax debt, Tyler held that the Takings Clause requires the government to remit the surplus of foreclosure proceeds over the tax debt. Now, Pung addresses how to measure that surplus. It is simply the difference between the tax debt and the foreclosure proceeds, regardless of the fair market value.

In 2015, Isabella County, Michigan, foreclosed a home for a $2,241.93 property tax debt after lengthy litigation. The home was purchased in 1991 for $125,000. It was assessed at $194,400 at the time of foreclosure, and it was resold about 18 months later by the purchaser for $195,000. However, the property was sold at the foreclosure auction for only $76,008, and Isabella County kept all proceeds. The taxpayer sued for the excess of the fair market value over the debt. The District Court granted the difference between the auction price and the tax debt, but denied the claim regarding the fair market value. The 6th Circuit confirmed in an unpublished opinion.

What is Just?

History predetermined the Supreme Court’s ruling. “[F]or hundreds of years, English and American law have allowed the seizure and sale of property as a tax-collection method, provided that the government return any surplus proceeds to the debtor.”[1] Throughout that time, the surplus has been measured as “the sale price, not the property’s hypothetical fair market value.”[2] “[A]t least when the sale is fairly conducted in light of our country’s history of tax sales,” that constitutes “just compensation.”[3] The Court did not examine whether the sale reflects the fair market value. Unquestionably, “the fair market value is the default measure of ‘just compensation’” in eminent domain cases.[4] Yet, even then, “there are situations where this standard is inappropriate” as when the fair market value is “too difficult to find, or when its application would result in manifest injustice to owner or public.”[5] “Just” is a relative construct.  “[W]hat is ‘just’ in one context may not be ‘just’ in another.”[6] The Court noted that a property owner facing foreclosure could obtain a loan to pay the taxes or sell the property themselves. “Here, the Pungs had years to take these steps and avoid foreclosure.  They failed to do so. In such a situation, the traditional rule, under which the taxpayer receives only the difference between the auction sale price and unpaid taxes, is ‘just.’”[7]

“[T]ax sales are designed to collect unpaid taxes without undue delay and administrative expense,” resulting in suboptimal prices.[8] The alternative “would impose unprecedented burdens on jurisdictions that wish to collect unpaid taxes and might well make tax sales impractical.”[9] Real property sales are time-consuming, costly, and risky. The Court warned that governments would likely need to pay the taxpayer in many situations. “The possibility of such a perverse result would render tax sales infeasible as a debt-collection mechanism,” despite acknowledging that some states do so earlier.[10]  Moreover, governments “might well compensate for this lost revenue by increasing the burden on residents who do pay their taxes.”[11] Therefore, tax sales actually benefit taxpayers as a whole.

The Court disclaimed that “[o]ur task in this case, however, is not to decide whether tax sales as historically conducted represent good public policy.”[12] The fact that such tax sales are historically entrenched decides the matter. “If the Takings Clause had been understood to impose restrictions that rendered these sales untenable, they would have presumably faded away, at least after the Fourteenth Amendment incorporated the Takings Clause against the States.”[13] Any interpretation that is contrary to historical practices will likely be poorly received. “That Pung’s novel interpretation of the Takings Clause would whisk this longstanding practice into the dust bin is strong evidence that his interpretation is incorrect.”[14]

The Court dismissed the taxpayer’s arguments regarding the procedure of the sale and the county’s choice to forsake lesser alternatives to foreclosure because they were not part of the question presented before the Court. In contrast, the taxpayer’s Eighth Amendment argument was properly presented to the Court. Nevertheless, the Court’s response to the taxpayer’s claim that the sale amounted to an “excessive fine” was quite brief. It acknowledged that “[f]orfeiture of property can be a fine for purposes of the Eighth Amendment if it serves in part to punish,” but “historical practice” influences this analysis.[15]  Here, the taxpayer’s Eighth Amendment argument fails for the same reason as the Fifth Amendment fails. It “lacks historical or precedential support.”[16] Like the “Fifth Amendment theory,” this would also mean “the demise of this country’s longstanding use of tax sales to collect debts.”[17] There was not any further explanation. Unfortunately, the Court did not indicate whether the tax sale constituted a fine or, if so, why it is not excessive.

A Concurring Dissent

According to the Court: “The Pung family lost its property because it failed to pay its taxes.”[18] However, Justice Thomas highlighted details revealing a more nuanced scenario. Pung was unanimously decided with two concurrences, technically speaking. Justice Sotomayor, joined by Justice Gorsuch and Justice Jackson, wrote a brief opinion emphasizing that the Court’s opinion does not have any implications for “identifying the contours of a fair auction.”[19] In contrast, Justice Thomas’s opinion was longer than the Court’s opinion. Although he joined all but one section of the majority opinion, Justice Thomas’s concurrence was more of a dissent.[20] Justice Thomas, joined by Justice Gorsuch, agreed that history determines the constitutionality of tax sales, but differed as to what that history is, concluding that “[w]hat Isabella County did to the Pungs was wrong, and, on my initial view, likely unconstitutional.”[21] He emphasized the peculiarities of the underlying tax debt. There was extensive litigation on the merits of the tax debt, which the taxpayer won. “The tax assessor, however, chose to not respect the court’s decision. ‘I don’t care what he says,’ she said of the judge who ruled for the Pungs.”[22] Indeed, “[w]hen asked at oral argument, the County’s attorney stated: ‘I don’t know what the township assessor’s reasoning was.’”[23]

Justice Thomas argued that the two prior exceptions the Court’s opinion recognized for the fair market value were the only two before this case. Neither applies here. “It is not too difficult to find the market value of an ordinary suburban home; the County already did so in assessing the amount of the tax that the Pungs owed. Likewise, there is no injustice, let alone manifest injustice, in paying the Pungs in full for their home.”[24] He agreed that history justifies the new third exception, “[b]ut, any exception based on history can be no broader than what that history justifies.”[25] Justice Thomas stressed that historically, courts held tax foreclosure sales to strict standards that were not met here. For example, the personal property needed to be seized before the real property could be taken. As for the argument that requiring foreclosure sales to be for fair market value hinders government operations, “that is the point of the Takings Clause, which necessarily prioritizes homeowners’ property rights over the government’s interest in efficiency and public necessity.”[26] Moreover, the government’s interest is to preserve property rights. “The government exists to protect property; property does not exist to support the government.”[27] Despite “concurring,” Justice Thomas seemingly disagreed with the Court’s ruling. Perhaps surprisingly, he did not comment on the Eighth Amendment issue.

Conclusion

It appears there will be a trilogy of tax sale cases. In 2023, Tyler v. Hennepin County held that the surplus of the sale must be given, and in 2026, Pung v. Isabella County explained how the surplus is measured. Yet it explicitly left questions of procedural sufficiency for the tax sale unanswered.


[1] Pung v. Isabella Cty., 146 S. Ct. 1964, 1969 (2026).

[2] Id. at 1970.

[3] Id.

[4] Id.

[5] Id. at 1971.

[6] Id. at 1970.

[7] Id. at 1971.

[8] Id.

[9] Id.

[10] Id. at 1972. On the previous page, the Court noted in a footnote that “various States have enacted regimes that require these kinds of choices” that incorporate fair market value, but it is inappropriate “for this Court to impose such a regime as a matter of constitutional law.” Id. at 1971.

[11] Id. at 1972.

[12] Id.

[13] Id.

[14] Id.

[15] Id. at 1973.

[16] Id.

[17] Id.

[18] Id.

[19] Id.(J. Sotomayor concurring).

[20]  “I join the Court’s opinion as to all but Part II–B because I agree that the auction surplus from a tax foreclosure sale can constitute just compensation if it is consistent with historical practice, and because I agree that the parties should have the opportunity to litigate below whether the local government’s conduct here was consistent with that practice.” Id. at 1974, fn.1(J. Thomas concurring).

[21] Id. at 1981(J. Thomas concurring).

[22] Id. at 1975(J. Thomas concurring).

[23] Id.(J. Thomas concurring).

[24] Id. at 1978(J. Thomas concurring)(omitting internal quotation marks).

[25] Id. at 1979(J. Thomas concurring).

[26] Id. at 1981(J. Thomas concurring).

[27] Id.(J. Thomas concurring).

Categories
News

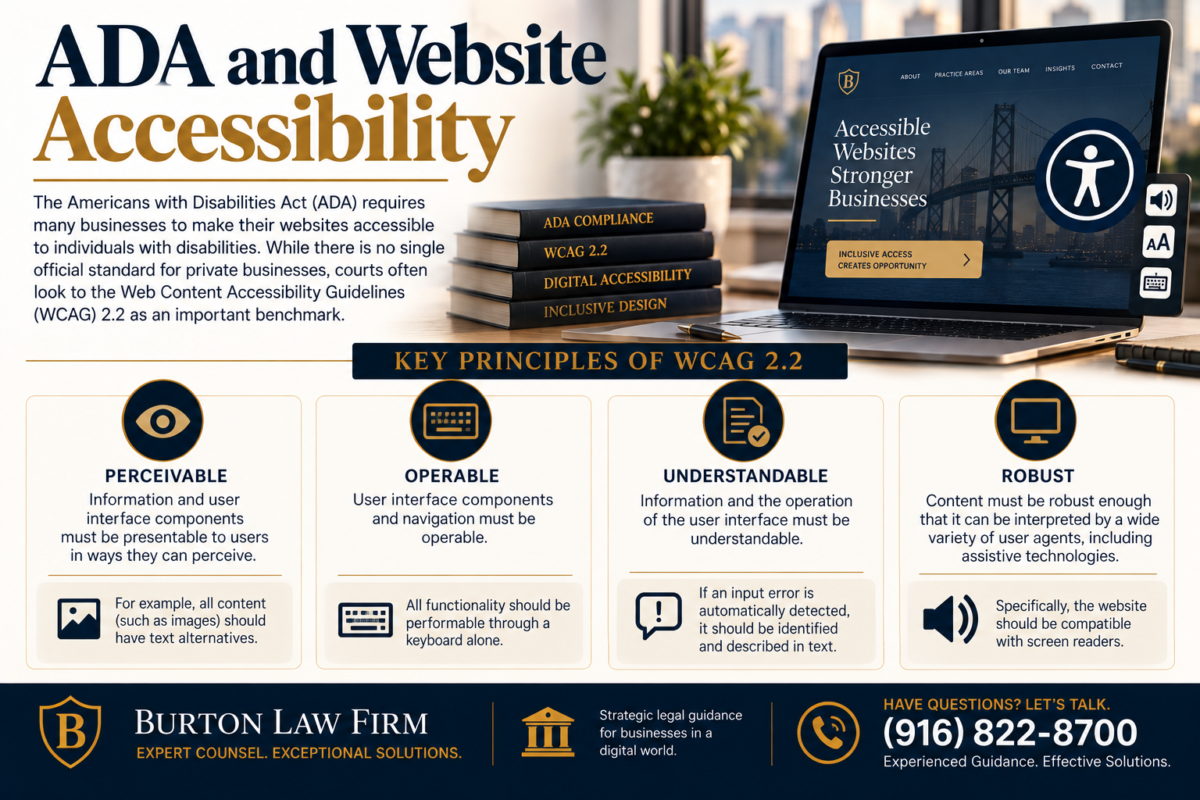
ADA and Website Accessibility

The Americans with Disabilities Act (ADA) generally requires publicly accessible businesses to be accessible to individuals with disabilities. Wheelchair ramps are perhaps the most visible feature required by the ADA, but less tangible accommodations are necessary, too. Courts have adapted this 1990 law to 21st-century needs by requiring many websites to be accessible to people with visual impairments and other disabilities.[1] This does not bind every website, but any establishment subject to the ADA’s physical mandates must comply with the ADA’s virtual mandates.[2]  

Unfortunately, there is not an official standard for private actors.[3] However, courts often use adherence to the Web Content Accessibility Guidelines (WCAG) promulgated by the World Wide Web Consortium to measure ADA compliance. “A failure to comply with WCAG may not be dispositive of ADA non-compliance, but compliance with this common accessibility standard is certainly helpful and informative in that respect.”[4] Consequently, it is often unclear what exactly is required for minimum accessibility under the ADA, but WCAG conformity can serve as a safe harbor. The latest standard is WCAG 2.2, which urges websites to be:

  • Perceivable: “Information and user interface components must be presentable to users in ways they can perceive.”
    • For example, all content (such as images) should have text alternatives.
  • Operable: “User interface components and navigation must be operable.”
    • As one application, all functionality should be performable through a keyboard alone.
  • Understandable: “Information and the operation of the user interface must be understandable.”
    • For instance, “[i]f an input error is automatically detected, the item that is in error is identified and the error is described to the user in text.”
  • Robust: “Content must be robust enough that it can be interpreted by a wide variety of user agents, including assistive technologies.”
    • Specifically, the website should be compatible with screen readers.

If there is good news for a defendant in ADA litigation, it is that the lawsuit can be mooted. “Courts routinely declare ADA access claims are moot when defendants modify noncompliant items.”[5] This may be difficult when the demands are on physical architecture, but it may be easier for simpler websites. Nevertheless, detecting WCAG compliance is a technical skill in and of itself. While there are automated detectors, a human-based determination is necessary to be certain. The Burton Law Firm does not endorse any vendor or particular method for either WCAG compliance detection or remediation. Nevertheless, the California Department of Rehabilitation has a list of potential vendors, many of which have been used by the state of California, and a few to an extensive degree. Of course, the Department of Rehabilitation also disclaims any recommendation or endorsement, even for these much-used vendors.


[1] Robles v. Domino’s Pizza, LLC, 913 F.3d 898 (9th Cir. 2019).

[2] Robles v. Domino’s Pizza, LLC, 913 F.3d 898, 905 (9th Cir. 2019).

[3] There is for state and local government entities, though. This uses WCAG 2.1, buttressing its role as a safe harbor for the private sector.

[4] Merrell v. Ralph Lauren Corp., No. 23-cv-06669-HSG, 2026 U.S. Dist. LEXIS 152333, at *19 (N.D. Cal. July 9, 2026).

[5] Merrell v. Tapestry Inc., No. 5:25-cv-02510-RGK-MAR, 2026 U.S. Dist. LEXIS 150519, at *7-8 (C.D. Cal. May 12, 2026).

Categories
News

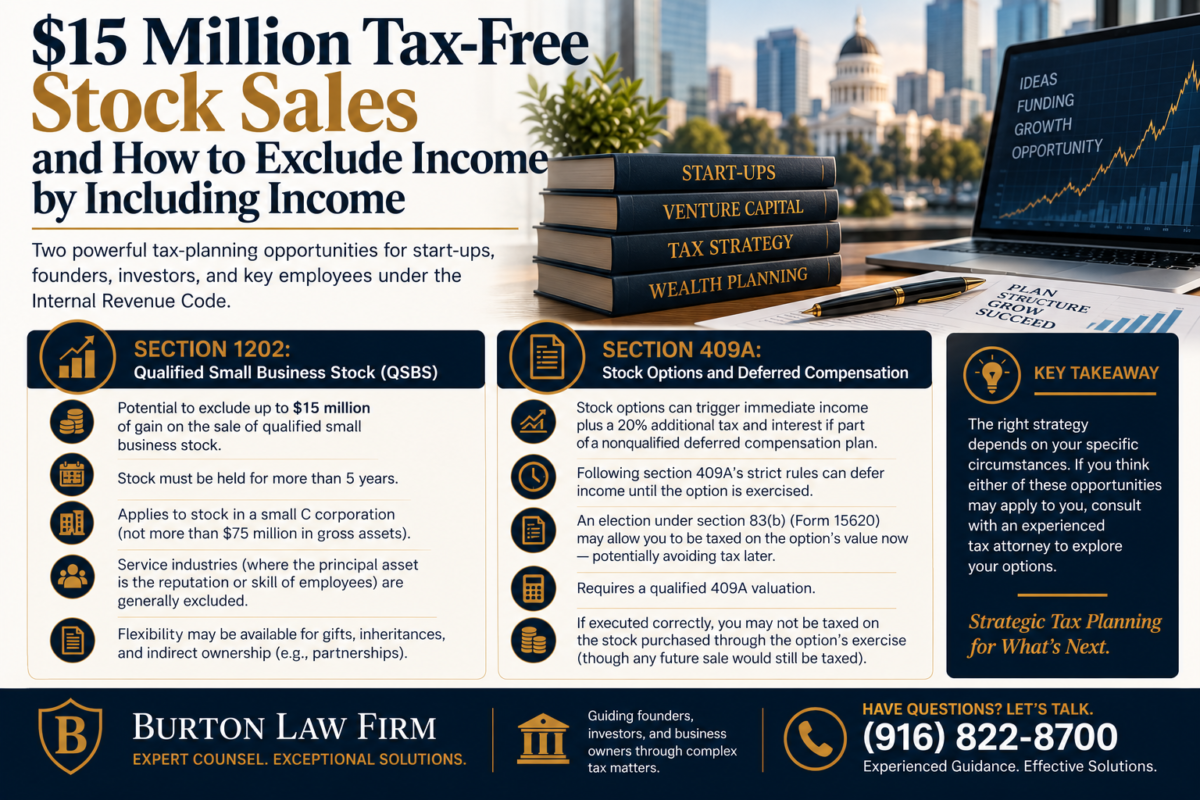
$15 Million Tax-Free Stock Sales and How to Exclude Income by Including Income

California is the land of start-ups. From January to August 2026, venture capitalists invested about $366 billion in California businesses. This venture capital is over triple the amount received by the remaining 49 states combined. Yet most founders, investors, and key employees are likely unaware of two valuable opportunities available under the Internal Revenue Code for start-ups.

The first is qualified small business stock treatment provided by section 1202 of the Internal Revenue Code. A person who purchased stock in a small C corporation (not more than $75 million in gross assets) can potentially exclude up to $15 million of gain if held for more than 5 years. There are several technical requirements. One of the most significant limitations is the disqualification of service industries “where the principal asset of such trade or business is the reputation or skill of 1 or more of its employees.”[1] Yet, there is flexibility facilitating gifts, inheritances, and indirect share ownership (such as through partnerships). There are relatively few regulations regarding qualified small business stock. Consequently, multiple advanced techniques remain viable, especially for the $15 million exclusion limitation.

The second overlooked opportunity lies in the regulations under Internal Revenue Code section 409A. The tax treatment of stock options is multifaceted. If part of a nonqualified deferred compensation plan, the stock option holder is taxed on that option’s value plus 20% of that value, along with interest. One means to avoid this outcome is to follow section 409A’s strict rules, which result in deferring the income inclusion until the option is struck. Another is to file an election under section 83(b) through Form 15620 if the option price is no less than the underlying stock’s fair market value as of the date the stock option was granted.[2] This requires a specific form of appraisal known as a section 409A valuation. If executed correctly, the option’s owner will not be taxed on the stock purchased through the option’s exercise (although any subsequent sale of that stock would still be taxed). Someone who received a stock option with a fair market value of $1 per share for 1,000 shares in 2026 would recognize $1,000 in income. The same person striking that option would not include any income from that exercise even if the fair market value grew to $100 per share.

            Tax planning is usually circumstantial. If you receive a stock option for a corporation’s shares eligible under section 1202 for qualified small business stock treatment, you would probably benefit most by striking that option immediately because the 5-year holding period does not include stock options. However, if the corporation is ineligible under section 1202 and you want to wait to exercise your option, your best tax strategy may be to choose to be taxed on that option now, thereby avoiding the tax on the stock you purchase later. If you suspect that either opportunity is at hand, please call 916-822-8700 or email info@lawburton.com.


[1] IRC § 1202(e)(3).

[2] 26 CFR § 1.409A-1(b)(5).

Categories
News

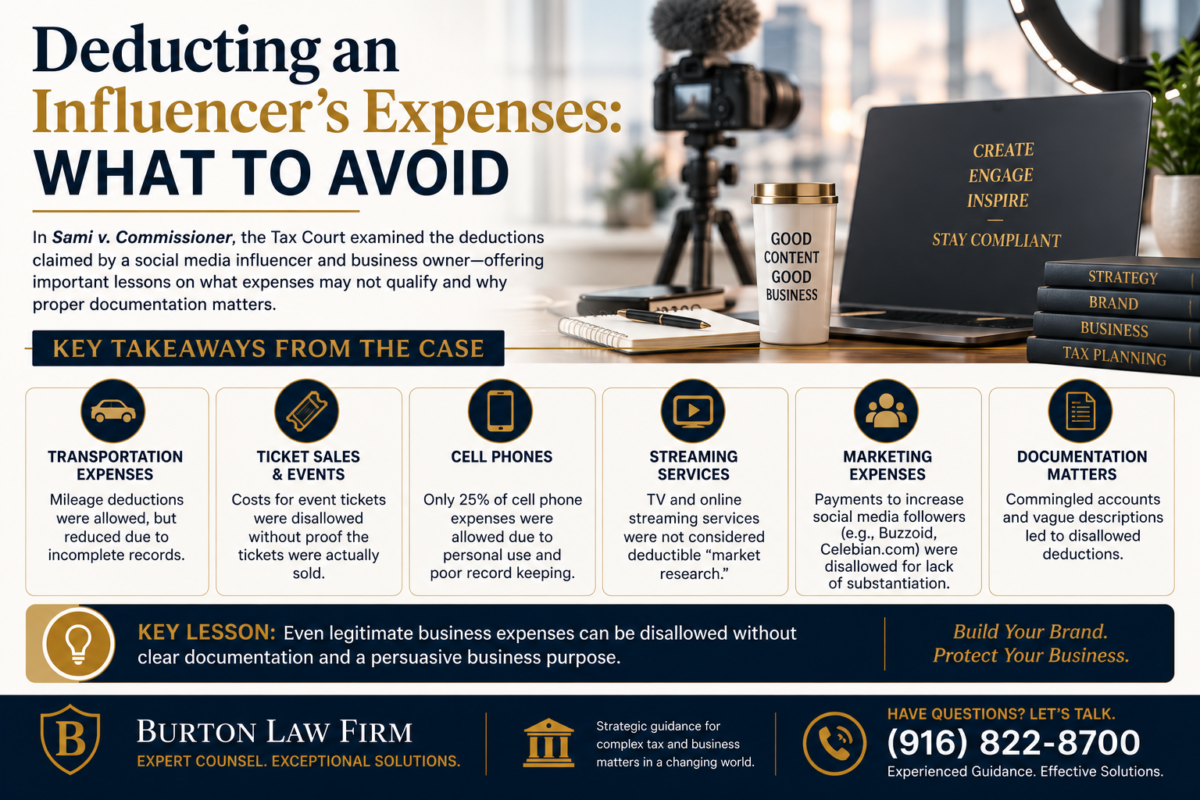
Deducting an Influencer’s Expenses: What to Avoid

“The epitome of a go-getter,” a taxpayer worked full-time in JetBlue’s IT department with two accounting degrees while running his own business.[1] This “business had three components: (1) transportation services, (2) event ticket sales, and (3) social media influencing.”[2] The taxpayer claimed connections with celebrities and the ability to grant access to exclusive events through those connections. However, almost all income for the years in question, 2019-2021, was attributed to transportation services. Sami v. Commissioner discussed the proper treatment of various purported business expenses, including the cost of meeting celebrities.

The taxpayer only claimed $730 as the cost of goods sold, but this was disallowed without proof that he sold the tickets he bought. His sole proof consisted of statements for his personal bank account. The taxpayer was more successful with the transportation deductions because the “strict substantiation requirements” did not apply to “any vehicle used by the taxpayer directly in the trade or business of transporting persons or property for compensation or hire.”[3] In addition, “[f]or the first time in his Simultaneous Opening Brief, the Commissioner argued that The taxpayer failed to show that he meets the requirement that he used the mileage-rate procedure in the first year in which the vehicles were placed in service in the business, 2016. This argument was a surprise and substantial disadvantage to The taxpayer because it requires different evidence to be presented, namely The taxpayer’s 2016 tax returns.”[4] Therefore, it was not considered by the Tax Court. Nevertheless, the Tax Court applied a 20% discount to the transportation deductions because the contemporaneous records lacked “the precise addresses of pickup and delivery of passengers.”[5]

The taxpayer’s office expenses were unchallenged by the IRS, and he was able to support his credit card processing fee deductions. His attempt to deduct the expenses attributable to his four cell phones was less successful. Due to obvious personal use and poor record keeping, only 25% of the reported expenses were upheld “[b]ecause it was reasonable from a business perspective to have at least one of the four phones.”[6] The Tax Court disallowed the claimed contract labor deductions for lack of substantiation. The taxpayer further claimed deductions for “market research.”[7] These were television and streaming services. “Viewing television and online videos is a common source of personal enjoyment, and we are not convinced from the taxpayer’s testimony that these payments were directly related to his business.”[8] Despite his claims that they “allowed him to learn about entertainment events, to which he could then sell tickets, and trends that might help him in his social media influencer activities,” these deductions were disallowed.[9] The taxpayer also claimed a variety of deductions for “general marketing.”[10] “[T]he description of the first general marketing payment of 2019 is ‘Idigic’ followed by a string of 34 numerals.”[11] The Tax Court was left to guess what these expenses might have been. “There seem to be many charges from places that, for a fee, increase the number of followers one has on TikTok and Instagram: Buzzoid, Celebian.com, and the aforementioned Idigic.”[12] Since “[t]he statements do not clearly state the full name of the seller nor the product or service purchased,” and the taxpayer commingled his business and personal accounts, these deductions were disallowed in full.[13] The taxpayer’s case suffered greatly from his lack of due diligence. Yet, he prevailed with regard to the qualified business income deductions largely because the IRS disallowed them without explanation. Indeed, “[i]t is not clear whether the Commissioner now disputes this.”[14] Regardless, the Tax Court found that the taxpayer’s business activities “are neither specified service trades or businesses nor performance of services as an employee” and therefore qualified under § 199A.[15]

The taxpayer’s main expenses consisted of “marketing events and marketing charity.”[16] He paid for and participated in several charitable events hosted or promoted by celebrities who would interact with the payors. These expenses were poorly substantiated. “For example, for 2021 The taxpayer reports one line from his credit card statement as ‘11/16/2021 (CR) TM*TICKETMASTER LOS ANGELES CA [1,661.57).’”[17] More fundamentally, the taxpayer failed to convince the Tax Court that these “expenses are primarily incurred for business rather than personal purposes.”[18] These activities would likely have been done regardless of any business. “The Grammys, (attempting to) catching a pass from Tom Brady, returning a serve from John McEnroe—these are desirable things. Witness the high prices they commanded.”[19] Furthermore, these were not originally reported as business deductions but rather as charitable deductions. Unfortunately, the Tax Court did not discuss the feasibility of these expenses as charitable deductions because the taxpayer abandoned that argument. However, the Tax Court observed that “if a charitable donor received some consideration in return for the donation, then the deduction is limited to the excess of the donated property’s value over the value of the goods or services received in return.”[20] Paying to meet celebrities might have benefited his nascent social media influencing career, but “the question is whether these expenses meet the necessary condition of being primarily undertaken for business, instead of personal reasons.”[21] It is irrelevant whether such “expenses are typical influencer expenses.”[22] In addition, while he now receives income from being an influencer, he did not at the time in question, “making such expenses more likely startup expenditures that must be capitalized under section 195. This would require much more legal analysis than the taxpayer has proffered.”[23] This did not benefit his transportation business because “he could drive only individuals he personally knew” for lack of proper licensing under local law.[24]

The Tax Court did not categorically disallow any expenses as deductions. Even streaming services for one’s own use could theoretically be deductible as a business expense if the Tax Court could be convinced that it was primarily for business purposes. However, Sami v. Commissioner is clear that there is a heavy presumption that conventionally recreational activities are not undertaken primarily for business purposes. While hypothetically rebuttable, this requires consistent reporting, thorough substantiation, and persuasive testimony of compelling business reasons. In summary, the taxpayer must act as a reasonable businessperson in all respects. The Tax Court explicitly rejected that title for the taxpayer by upholding his penalties because of his poor accounting records, particularly in light of his accounting background.

If you are uncertain whether a business expense can be deducted, please call 916-822-8700 or email info@lawburton.com.


[1] Sami v. Commissioner, Nos. 8834-23, 16512-23, 2026 Tax Ct. Memo LEXIS 73, at *3 (T.C. Aug. 18, 2026).

[2] Id.

[3] Id. at *15.

[4] Id. at *16 fn.7.

[5] “Mr. Sami’s original figures on his return relied on the Bank of America website’s categorization of his expenses, to which he no longer has access. On brief, his new figures rely on his contemporaneous hand-filled-out vouchers for each trip. These vouchers had no mileage numbers, simply a starting and ending destination, usually just listed as a city. He then assumed that each trip started and ended at his home, and he used Google Maps to determine the distance between the two boroughs or cities to and from which he was driving, or sometimes just stated an amount (e.g., all Manhattan-to-Manhattan trips seem to have been counted as five miles). Finally, he multiplied this estimated mileage by the IRS standard mileage rate for each year to reach his current claimed amount.” Id. at *16-17.

[6] Id. at *22.

[7] Id.

[8] Id. at *23.

[9] Id.

[10] Id.

[11] Id. at *24.

[12] Id.

[13] Id. at *25.

[14] Id. at *31-32.

[15] Id. at *32.

[16] Id. at *26.

[17] Id. at *30.

[18] Id. at *27.

[19] Id.

[20] Id. at *31 fn.12.

[21] Id. at *28.

[22] Id. at *29.

[23] Id. at *30.

[24] Id. at *29.

Categories
News

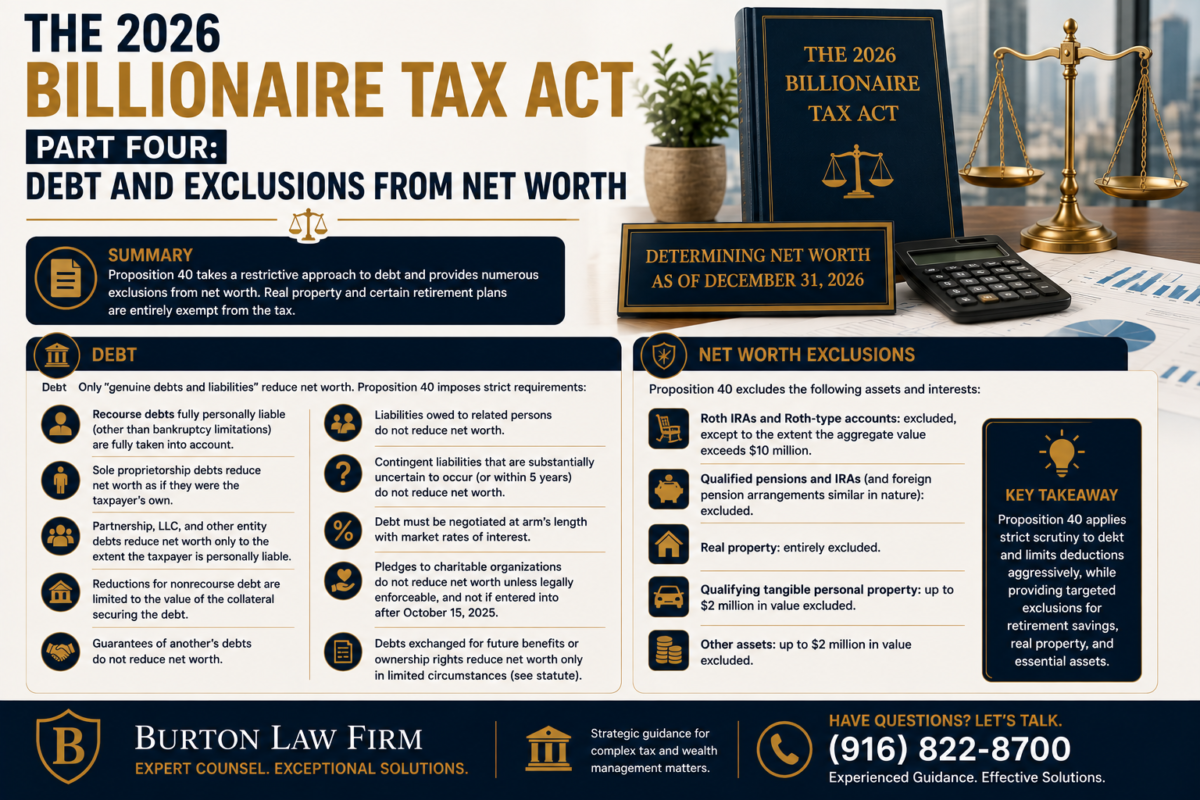
The 2026 Billionaire Tax Act Part Four: Debt and Exclusions from Net Worth

Summary

Welcome to part four of this series on Proposition 40, “The 2026 Billionaire Tax Act.”[1] This part discusses how debt is incorporated into “net worth” and describes the various assets that are excluded from “net worth.” In summary, Proposition 40 is suspicious of debt and imposes strict requirements for any indebtedness to be bona fide in order to impact net worth. Real property and certain retirement plans are entirely exempt from Proposition 40’s tax.

Debt

The 2026 Billionaire Tax Act would take a restrictive view on debt’s role in calculating net worth. Only “[g]enuine debts and liabilities shall be taken into account.”[2] This principle would be enforced through several rules:

  • “Recourse debts for which the taxpayer is fully personally liable, without any limitations other than those arising from bankruptcy law, shall be fully taken into account,” except as provided in the subsequent rules.[3]
  • “Debts and other liabilities of a taxpayer’s sole proprietorship shall reduce net worth as if they were debts or other liabilities of the taxpayer.”[4]
  • “The taxpayer’s net worth shall not be reduced by the amount of debts or other liabilities of a partnership, limited liability company, or other business entity (other than a sole proprietorship) which are allocated to the taxpayer for purposes of computing tax, except to the extent that the taxpayer is personally liable for such debt or other liability.”[5]
  • Reductions due to nonrecourse debts “shall not exceed the amounts included in the taxpayer’s net worth on account of the assets serving as collateral for the debt or liability.”[6]
  • “A taxpayer’s net worth shall not be reduced by the taxpayer’s guarantee of another’s debts or other liabilities.”[7]
  • Net worth would not be decreased for any liability “owed to a related person or persons.”[8]
  • Net worth would not be decreased “if the existence or amount of the liability is contingent on future events that are substantially uncertain to occur or that are substantially uncertain to occur within the subsequent five years.”[9]
  • Any reduction in net worth due to debt requires the debt to be “negotiated for at arm’s length” with “market rates of interest.”[10]
  • “A pledge to make a subsequent contribution to a charitable or philanthropic organization shall not reduce net worth unless such pledge is legally enforceable by the organization to which such contribution is pledged, and in any event no such pledge may reduce net worth if such pledge is entered into after October 15, 2025.”[11]
  • “Any debts or liabilities of a taxpayer in exchange for which the taxpayer is entitled to receive future benefits or future ownership rights” may “only reduce net worth” either:[12]
    • To the extent that future benefits would be included in the net worth.[13]
      • “In the case of a legally enforceable pledge to make a subsequent contribution to a charitable or philanthropic organization, the value of any future benefits received in exchange shall be zero, except to the extent that such benefits would constitute a substantial benefit for purposes of determining the contributor’s charitable contribution deduction.”[14]
    • To the extent that “[t]he taxpayer can demonstrate, through clear and convincing evidence, that the amount owed under the debt or liability is in excess of any future benefits or ownership rights that are not included in the taxpayer’s net assets.”[15]

Net Worth Exclusions

            The 2026 Billionaire Tax Act would offer several exclusions and exceptions to its wealth tax:

  • “Amounts held in Roth IRA or other Roth-type retirement arrangements or any substantially similar accounts, except to the extent that the aggregate value in all such accounts in which the taxpayer holds a beneficial interest, either directly or indirectly, exceeds $10 million ($10,000,000) in present value,” would be excluded from the tax.[16]
  • Apart from Roth-type retirement arrangements or substantially similar accounts, “qualified pensions and individual retirement arrangements, including those described by Section 219(g)( 5) of the Internal Revenue Code, or foreign pension arrangements similar in nature to those described in that Section and exempted from U.S. taxation by a treaty obligation of the United States” would be excluded from the wealth tax.[17]
  • “Nonqualified deferred compensation (other than a contingent profits interest), and any other promises of future payments specified by the Board” that is not described above would be taxed only to the extent that all of the following are true:[18]
    • “[T]he taxpayer has a legally binding right as of the end of the tax year to such payment.”[19]
    • “The compensation has not been actually or constructively received on or before the end of the year.”[20]
    • “Pursuant to the compensation arrangement, the payment is payable to, or on behalf of, the taxpayer on or after the end of the year.”[21]
  • “All interests in any real property held directly by a taxpayer or held via a revocable trust shall not be included in net worth.”[22]
    • Neither “interests” nor “real property” is defined.
  • “Tangible personal property located outside California is excluded if” both of the following are true:[23]
    • The property was “located outside California for at least 270 days during 2026.”[24]
    • The property was not “relocated temporarily with a substantial purpose of avoiding tax.”[25]
  • “In the case of a defined benefit plan,” which is “not otherwise exempt,” the “amount equal to the present value of the taxpayer’s accrued benefit on the last day of the tax year is treated as included by the taxpayer in the taxpayer’s net worth,” while the remainder is excluded.[26]
  • The Franchise Tax Board would be directed to “adopt regulations regarding the taxability of receivables and similar assets,” with the power to exempt them based on “whether a taxpayer is reasonably likely to receive payment from a particular type of receivable.”[27]
    • However, “all receivables shall be included in net worth” until such regulations are adopted.[28]
  • “For all other assets, including art and collectibles, financial instruments other than those that are publicly traded, intellectual property rights, debts and other liabilities owed to the taxpayer (other than those that are publicly traded), and vehicles and other personal property, the taxpayer may exclude up to $5 million ($5,000,000) of total asset value of those assets from net worth and from the reporting requirements.”[29]
    • Beyond the $5 million threshold, “a taxpayer must report the fair market value of those assets, and for each asset or group of substantially interchangeable assets (such as derivative contracts relating to the same underlying security) worth in excess of $1 million ($1,000,000), the taxpayer shall submit a certified appraisal.”[30]

[1] Nothing should be construed as support of or opposition to Proposition 40 by the author or The Burton Law Firm. 

[2] Proposed RTC § 50302(flush language).

[3] Proposed RTC § 50302(a).

[4] Proposed RTC § 50302(c).

[5] Proposed RTC § 50302(c).

[6] Proposed RTC § 50302(b).

[7] Proposed RTC § 50302(d).

[8] Proposed RTC § 50302(e).

[9] Proposed RTC § 50302(e).

[10] Proposed RTC § 50302(e).

[11] Proposed RTC § 50302(f).

[12] Proposed RTC § 50302(g).

[13] Proposed RTC § 50302(g)(1).

[14] Proposed RTC § 50302(g)(3).

[15] Proposed RTC § 50302(g)(2).

[16] Proposed RTC § 50303(c)(7)(B).

[17] Proposed RTC § 50303(c)(7)(A).

[18] By the literal terms of this provision, it would appear that non-qualified deferred compensation is taxable whether it is payable before, on, or after the end of the year, even far into the future. Proposed RTC § 50303(c)(7)(C).

[19] Proposed RTC § 50303(c)(7)(C)(i).

[20] Proposed RTC § 50303(c)(7)(C)(ii).

[21] Proposed RTC § 50303(c)(7)(C)(iii).

[22] Proposed RTC § 50303(c)(4).

[23] Proposed RTC § 50303(c)(5).

[24] Id.

[25] Id.

[26] Proposed RTC § 50303(c)(7)(E).

[27] Proposed RTC § 50303(c)(8).

[28] Proposed RTC § 50303(c)(8).

[29] Proposed RTC § 50303(c)(9).

[30] Id.

Categories
News

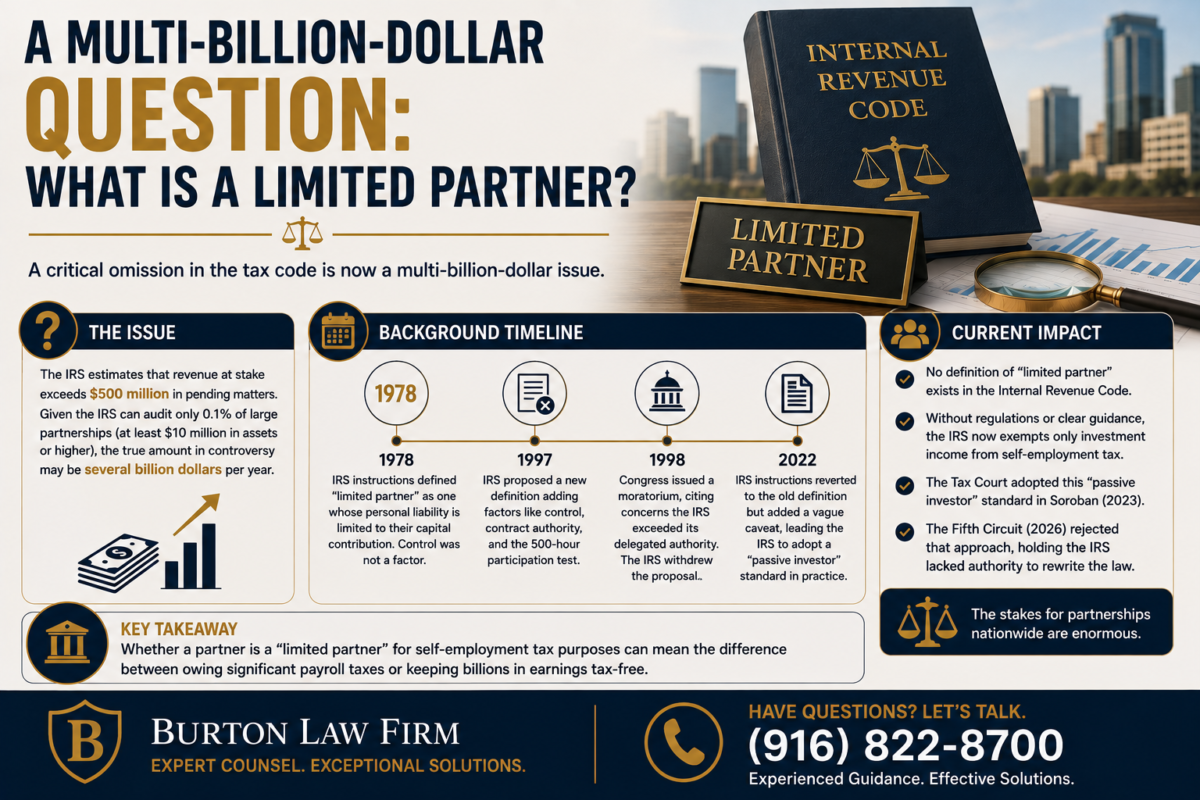
A Multi-Billion-Dollar Question: What is a Limited Partner?

Introduction

Wages are generally subject to payroll taxes. Self-employed individuals are instead subject to a separate yet parallel tax designed to correspond to the payroll tax burden.[1] Self-employment income generally includes “distributive shares of partnership income in net earnings from self-employment.”[2] Section 1402(a)(13) provides an exception excluding “the distributive share of any item of income or loss of a limited partner, as such, other than guaranteed payments described in section 707(c) to that partner for services actually rendered to or on behalf of the partnership to the extent that those payments are established to be in the nature of remuneration for those services.”[3] However, the Internal Revenue Code does not define the term “limited partner.” This is a critical omission. “The IRS estimates that revenue at stake exceeds $500 million, just in pending matters.” Since the IRS can only audit, let alone litigate, 0.1% of large partnerships (at least $10 million in assets or higher), the true amount in controversy may well be several billion dollars per year.

Background

The limited partner exception to the self-employment tax came into effect in 1978. In the same year, “the IRS issued partnership tax return instructions that defined ‘Limited Partner’ as ‘one whose potential personal liability for partnership debts is limited to the amount of money or other property that the partner contributed or is required to contribute to the partnership.’”[4] Control over the partnership was not mentioned as a factor for this exception for over forty years.

Nevertheless, the IRS attempted to define a “limited partner, as such,” in 1997. “The proposed regulation provided that an individual would not be treated as a limited partner if the individual had personal liability for partnership debts, had authority to contract on behalf of the partnership, or participated in the partnership’s trade or business for more than 500 hours during the partnership’s taxable year.”[5]  The IRS did not alter its instructions to conform to its proposed regulations. The proposed regulations caused some alarm in Congress, which issued a moratorium on that proposed regulation until 1998, citing concerns that the IRS exceeded its delegated authority. The IRS did not pursue the regulation further.

Suddenly on January 7, 2022, published instructions “defining ‘limited partner’ in the same way the instructions did in the past,” but with “a vague possible caveat: ‘However, whether a partner qualifies as a limited partner for purposes of self-employment tax depends upon whether the partner meets the definition of a limited partner under section 1402(a)(13).’”[6] There was no indication that this definition contradicted the definition of limited partner given earlier in the instructions. This remains the case today.[7] Yet, without a regulation or even clear published guidance, the IRS began to limit the limited partner definition to exempt only investment income.[8] This “passive investor” standard was adopted by the Tax Court in 2023 through Soroban Capital Partners LP v. Commissioner. The 5th Circuit reversed the Tax Court’s definition in a separate case, Sirius Solutions, L.L.L.P. v. Commissioner, on January 16, 2026: “We hold that a ‘limited partner’ in § 1402(a)(13) is a limited partner in a state-law limited partnership that is afforded limited liability.”[9] The IRS petitioned for an en banc rehearing of this decision by the 5th Circuit. The court denied this petition, yet withdrew its prior opinion and substituted a new one on August 12, 2026.

K Alain, L.L.L.P. v. Commissioner

The case was retitled from Sirius Solutions, L.L.L.P. v. Commissioner to K Alain, L.L.L.P. v. Commissioner, to reflect the partnership’s name change. The new opinion is less than half the old opinion’s length and was written as if the old opinion never existed. Although the 5th Circuit did not discuss why the old opinion was withdrawn, there are material differences between the opinions despite the same basic ruling in the taxpayer’s favor. The old opinion created a bright-line rule that any partner with limited liability under state law is a limited partner, adopting the historical partnership tax return instructions issued by the IRS. In contrast, the new opinion stated: “We hold the ordinary public meaning of this phrase is a partner who plays no significant role in managing or running a business.”[10]

K Alain, L.L.L.P. v. Commissioner used dictionaries, contemporaneous academic treatises, nontax contemporaneous caselaw, and state law to reach “the ordinary understanding of ‘limited partner’ in 1977,” when the exception was enacted.[11] “At bottom, all relevant sources suggest that, in 1977, the ordinary public meaning of ‘limited partner’ included a partner who did not play a significant role in managing or running the business.”[12] This was a straightforward matter, according to the 5th Circuit: “Here, we apply the plain text. Nothing more.”[13] It rejected “the dissent’s parade of horribles,” explaining that “this court’s job is to discern and apply the law’s plain meaning as faithfully as we can, not ‘to assess the consequences of each approach and adopt the one that produces the least mischief.”[14] Although Alain cited the historical interpretation of the IRS as a reason for its ruling, the ruling did not depend on prior practice.

Alain’s withdrawn opinion and over four decades of IRS instructions held that a limited partner is simply a partner with limited liability. The 5th Circuit rejected that standard by adding the condition that the partner must “not play a significant role in managing or running the business.”[15] Alain did not explain why. The taxpayer in Alain won in that the 5th Circuit vacated the unfavorable Tax Court judgment. However, the partnership could still lose on remand. The Tax Court is now tasked with determining whether the limited partners’ involvement was “significant.” Alain gave little guidance on how that is accomplished. Instead, Alain issued a sharp rebuke of the Tax Court for its opinion in Soroban:

With just a few sentences of operative analysis—citing no contemporary textual authority—the Tax Court insisted that ‘limited partner, as such’ somehow denoted more than limited liability. The Tax Court then said, without significant analysis, that this required a ‘passive investor’ rule. The Tax Court made no attempt to ground its rule in the original public meaning of “limited partner” in 1977.[16]

This may influence whether the Tax Court will follow Alain outside of the 5th Circuit.

Broader Context

Alain did not settle the controversy over the limited partner exception to the self-employment tax. The Tax Court “adheres to the doctrine of stare decisis” and “takes seriously its obligation to facilitate uniformity in the tax law” as a nationwide court.[17] “When one of our decisions is reversed by an appellate court, the Court will thoroughly reconsider the problem in the light of the reasoning of the reversing appellate court and, if convinced thereby, follow the higher court.”[18] Yet if “convinced that our original decision was right, the proper course is to follow our own honest beliefs until the Supreme Court decides the point.”[19] Nevertheless, it will follow a contrary appellate decision when both the decision is “squarely on point,” and an appeal from the Tax Court would rest in the circuit court that issued the contrary decision.[20] “To do otherwise would be futile and wasteful given the inevitable reversal from the appellate court.”[21] Therefore, the Tax Court will likely comply with Alain within the 5th Circuit, but it will still need to be convinced to apply it elsewhere.

The self-employment tax and the payroll taxes fund Social Security and Medicare. This funding will be insufficient for Social Security beginning in 2033 and for Medicare beginning in 2033, whereby only 77% and 89% of their respective scheduled benefits will be distributed.


[1] Overview of the Federal Tax System as in Effect for 2025 at 27.

[2] Soroban Capital Partners LP v. Commissioner, 161 T.C. 310, 316 (2023).

[3] IRC § 1402(a)(13).

[4] Alain v. Commissioner, No. 24-60240, 2026 U.S. App. LEXIS 24366, at *13 (5th Cir. Aug. 12, 2026).

[5] Soroban Capital Partners LP v. Commissioner, 161 T.C. 310, 317 (2023).

[6] Sirius Sols. L.L.L.P. v. Commissioner, 165 F.4th 374, 380 (5th Cir. 2026) withdrawn by Alain v. Commissioner, No. 24-60240, 2026 U.S. App. LEXIS 24366(5th Cir. Aug. 12, 2026).

[7] Thus, the 2025 Instructions for Form 1065 states at page 3 that: “A limited partner is a partner in a partnership formed under a state limited partnership law, whose personal liability for partnership debts is limited to the amount of money or other property that the partner contributed or is required to contribute to the partnership.” Furthermore, the instructions provide at page 44: Generally, a limited partner’s share of partnership income (loss) isn’t included in net earnings (loss) from self-employment. Limited partners treat as self-employment earnings only guaranteed payments for services they actually rendered to, or on behalf of, the partnership to the extent that those payments are payment for those services. However, whether a partner qualifies as a limited partner for purposes of self-employment tax depends on whether the partner is considered a limited partner under section 1402(a)(13).”

[8] The 5th Circuit emphasized the magnitude of this shift: 

The Commission’s position in this case is that it can change the meaning of “limited partner” from (A) “limited liability alone,” which was the pre-Soroban standard, to (B) Soroban’s “passive investor” standard—with zero action from Congress to amend § 1402(a)(13)’s text. Perhaps that level of administrative control over billions or trillions of dollars in tax liability is permissible as a general matter. But at a minimum, even assuming the Commissioner can unilaterally effectuate such changes through tax instructions, its instructions must comport with the original public meaning of the text enacted by Congress in 1977.

Alain v. Commissioner, No. 24-60240, 2026 U.S. App. LEXIS 24366, at *14 (5th Cir. Aug. 12, 2026).

[9] Sirius Sols. L.L.L.P. v. Commissioner, 165 F.4th 374, 388 (5th Cir. 2026) withdrawn by Alain v. Commissioner, No. 24-60240, 2026 U.S. App. LEXIS 24366(5th Cir. Aug. 12, 2026).

[10] Alain v. Commissioner, No. 24-60240, 2026 U.S. App. LEXIS 24366, at *6 (5th Cir. Aug. 12, 2026).

[11] Id. at *9.

[12] Id. at *11.

[13] Id.

[14] Id.(omitting internal quotation marks).
[15] Id.

[16] Id. at *12(omitting internal citations; emphasis added by Alain).

[17] Mukhi v. Comm’r of Internal Revenue, 163 T.C. No. 8 at *2 (2024).

[18] Id.(omitting internal quotation mark and ellipsis).

[19] Id.(omitting internal quotation mark and brackets).

[20] Id.(omitting internal brackets).

[21] Id.(omitting internal quotation marks).
Categories
News

The 2026 Billionaire Tax Act Part Two: Rate, Reporting, and Payment

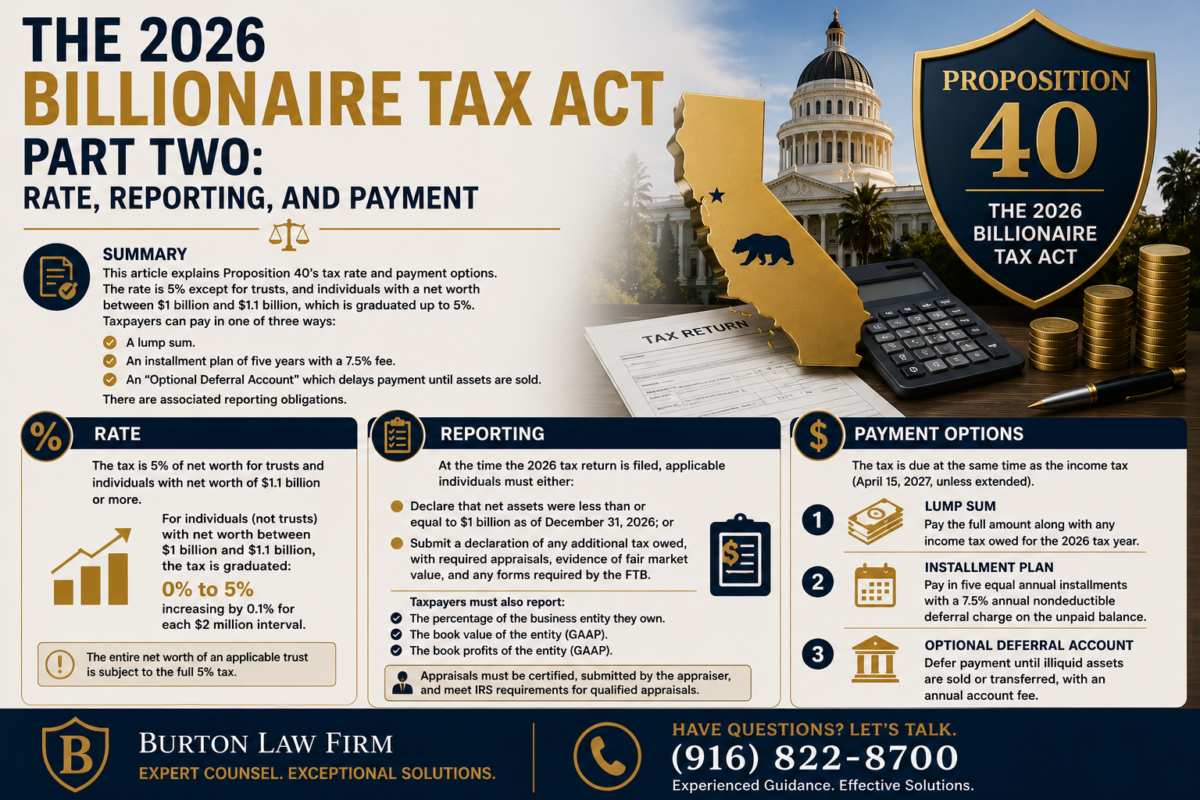
Welcome to part two of this series on Proposition 40, “The 2026 Billionaire Tax Act.”[1] This article discusses the tax rate and how taxpayers can pay the amount due under Proposition 40. The rate is 5% except for trusts, individuals with a net worth below $1.1 billion (but above $1 billion), which is graduated to 5%. There are three ways to pay:

  1. A lump sum.
  2. An installment plan of five years with a 7.5% fee.
  3. An “Optional Deferral Account” which delays payment until assets are sold.

There are associated reporting obligations. For most people, this will be a box to tick, while for others it will be a full disclosure of their net worth, together with appraisals.

Rate

“[T]he tax imposed is 5 percent of the net worth of such individual or trust,” except that “[i]n the case of an individual (other than a trust),” the tax rate would decrease by “0.1 percentage point (but not below zero) for each $2 million” below $1.1 billion in an individual’s net worth.[2] Thus, the tax rises from 0% to 5% for individual (not trust) net worths from $1 billion to $1.1 billion, increasing by 0.1% point for each $2 million interval. Moreover, the entire net worth of an applicable trust is subject to the full 5% tax even if the net worth is less than $1 billion.

Reporting

Each “California resident individual” required to file a California income tax return or an “applicable individual” would need to “[a]t the time a return is filed” for the 2026 tax year either:[3]

  • Declare that their net assets were less than or equal to $1 billion as of December 31, 2026.[4]
  • “Submit a declaration of the amount of any additional tax that is owed” under the 2026 Billionaire Tax Act, “together with any required appraisals or other evidence of fair market value,” and “any forms created by the Franchise Tax Board for calculating any additional tax owed under.”[5]

Furthermore, each “taxpayer” of the Proposition 40 tax must report all of the following:[6]

  • “The percentage of the business entity owned by the taxpayer.”[7]
  • “The book value of the business entity as of the end of the tax year, determined according to generally accepted accounting principles.”[8]
  • “The book profits of the business entity in the tax year according to generally accepted accounting principles.”[9]
    • For the purposes of this particular reporting requirement, “‘the tax year’ of the business entity means the latest tax year of the business entity ending within or with the tax year of the taxpayer.”[10]

If the taxpayer lacks information regarding such a business entity’s book value or book profits, “and also lacks the right to obtain that information, the taxpayer must submit a certified appraisal of all of the taxpayer’s interests in the business entity.”[11] A sole proprietorship’s assets would be treated and reported as the individual’s assets.[12] Any certified appraisal made for the purposes of the 2026 Billionaire Tax Act would need to be submitted to the FTB by the appraiser, along with information identifying the pertinent taxpayer.[13] The 2026 Billionaire Tax Act would borrow the requirements for a qualified appraiser and a qualified appraisal from the IRS regulations.[14]

Payment

The tax would be due at the same time as the income tax.[15] The tax may be paid in three ways:

  • A lump sum “along with any income tax owed for the 2026 tax year.”[16]
  • “[A]nnually in five equal installments commencing in the year the tax is due with each subsequent annual installment payment also being subject to an annual nondeductible deferral charge of 7.5 percent of the remaining unpaid balance.”[17]
  • An “optional deferral account” (ODA) in cases whereby Proposition 40’s tax liability would be in “excess of the combined total value of all of the individual’s publicly traded assets.”[18] In effect, an ODA functions as a sort of receivership or trust policing the relationship between the taxpayer and their illiquid assets, generally taxing 5% of distributions in addition to the income tax:
    • An ODA is a contract that “shall be legally binding on the taxpayer, and also on the taxpayer’s estate and assigns, until” the tax liability is fully paid.[19] This obliges the taxpayer to:
      • File all required forms regarding the ODA regardless of residency.[20]
        • “Failure to make annual reports and file any required forms shall be treated as a breach of contract and shall also be subject to the same penalties as a failure to file income tax forms for California residents who are required to file income tax forms.”[21]
      • “Reconcile and pay all tax liabilities that may arise as a result of the ODA.”[22]
      • Submit to California’s personal jurisdiction regarding the ODA.[23]
    • “A taxpayer may maintain only one ODA.”[24]
    • The ODA may attach to assets only to the extent that the wealth tax liability exceeds the taxpayer’s total sum of publicly traded assets.[25]
    • “[A]ny material distribution transactions made with regard to the ODA” must be annually reported.[26]
      • This generally includes any “withdrawal of money, property, or other value from” ODA assets and any “transaction with the taxpayer, or a related person to the taxpayer, that has the effect of transferring any assets or value of assets to which an ODA is attached without also transferring the ODA obligations.”[27]
      • However, this excludes “ordinary and necessary transactions for maintaining or increasing the value of assets to which an ODA is attached and that would not have the effect of distributing any profits, dividends, or other payments to owners for the use of capital, or similar transfers.”[28]
      • The FTB would be empowered and charged with the responsibility for specifying what transactions are and are not material distribution transactions.[29]
    • Material distribution transactions would be taxed at 5% (in addition to the income tax).[30]
    • An ODA could only be closed by taxing all remaining ODA assets at 5%.[31]

[1] Nothing should be construed as support of or opposition to Proposition 40 by the author or The Burton Law Firm. 

[2] Proposed RTC § 50301(b).

[3] Proposed RTC § 50301(d).

[4] Proposed RTC § 50301(d)(1)(referencing the “valuation date” which is December 31, 2026, pursuant to proposed RTC § 50308(o)).

[5] Proposed RTC § 50301(d)(2).

[6] Proposed RTC § 50303(c)(3)(A). The term “taxpayer” is undefined for these purposes. However, its plain meaning would limit its applicability to persons actually liable for taxes under Proposition 40.

[7] Proposed RTC § 50303(c)(3)(A)(i).

[8] Proposed RTC § 50303(c)(3)(A)(ii).

[9] Proposed RTC § 50303(c)(3)(A)(iii).

[10] Proposed RTC § 50303(c)(3)(A)(iii).

[11] Proposed RTC § 50303(c)(3)(B).

[12] Proposed RTC § 50303(c)(2).

[13] Proposed RTC § 50305(a). Ignorance does not necessarily seem to excuse the appraiser’s duty. It is possible that an appraiser may be required to affirmatively inquire.

[14] Proposed RTC § 50305(b).

[15] Proposed RTC § 50301(c). This would be April 15, 2027, a Thursday. However, an official disaster proclamation may delay its due date. RTC § 18572.

[16] Proposed RTC § 50301(c).

[17] Proposed RTC § 50301(c).

[18] Proposed RTC §§  50301(b) & 50304(a).

[19] Proposed RTC § 50304(b).

[20] Proposed RTC §§ 50304(a)(1) & 50304(d).

[21] Proposed RTC § 50304(d).

[22] Proposed RTC § 50304(a)(2).

[23] Proposed RTC § 50304(a)(3).

[24] Proposed RTC § 50304(c).

[25] Proposed RTC § 50304(c).

[26] Proposed RTC § 50304(d).

[27] Proposed RTC § 50304(f).

[28] Proposed RTC § 50304(g).

[29] Proposed RTC § 50304(h).

[30] Proposed RTC §§ 50304(e) & 50304(i).

[31] Proposed RTC § 50304(l).