Expert Counsel. Exceptional Solutions.

+1 (916) 822-8700

The 2026 Billionaire Tax Act Part Three: Asset Side of Net Worth

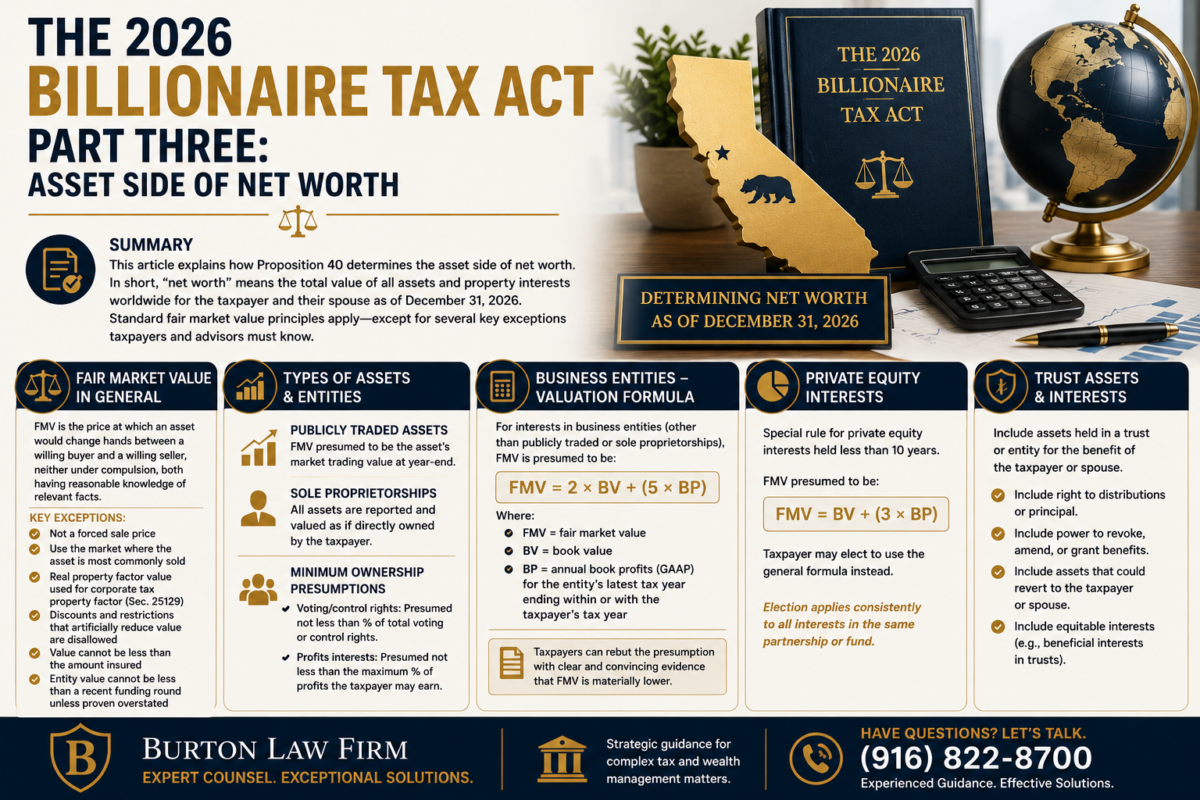
Welcome to part three of this series on Proposition 40, “The 2026 Billionaire Tax Act.”[1] This article discusses how net worth is determined on the asset side. In summary, “‘[n]et worth’ means the total value of all assets and property interests taken into account for the taxpayer and their spouse worldwide under Section 50303 [regarding fair market value] and other applicable provisions of this Part as of” December 31, 2026.[2] Usually, standard fair market value principles apply. Yet there are several important exceptions that taxpayers and their advisors need to be aware of. The next part will discuss the debt side of net worth, as well as the exclusions from “net worth.”

Fair Market Value in General

In general, “the fair market value of each asset owned by a taxpayer is the price at which the asset would change hands between a willing buyer and a willing seller, neither being under any compulsion to buy or to sell, and both having reasonable knowledge of relevant facts.”[3] However, Proposition 40 would provide many exceptions to this rule and empower the FTB to make more.[4] For example, “[t]o the extent valuation of real property is required, the value used for calculating the property factor of the Corporate Income Tax, under Section 25129, is to be used.”[5] The 2026 Billionaire Tax Act would anticipate and attempt to preempt certain strategies, such as discounting and restricted shares. “Any feature of an asset, such as a shareholder rights plan, shall not be taken into account in determining the asset’s value where a significant purpose and effect of adding the feature is to reduce the appraised value of the asset. No valuation or other discount shall be taken into account if such discount would have the effect of reducing the value of a partial interest in an asset below the taxpayer’s pro rata portion of the value of the entire asset.”[6]

There are other rules binding the taxpayer to a form of estoppel. “In no case shall the value of an asset be determined to be less than the amount for which such asset is insured.”[7] Also, “[i]n the case of a business entity, in no case shall the value of such entity be less than the valuation reflected in any funding round or other sale of equity occurring within two years of the valuation date, unless the taxpayer can show by clear and convincing evidence that such valuation would significantly overstate the value of the entity.”[8]

Fair Market Value of Entities

The fair market value of “publicly traded assets” would be “presumed to be the asset’s market trading value at the end of the individual’s tax year.”[9] “[A]ll assets owned by or held through a sole proprietorship shall be reported and valued as though they were directly owned and held by the taxpayer and not through a sole proprietorship.”[10] A minimum amount of ownership is rebuttably imputed regarding rights to control or profit:

  • “For any interests that confer voting or other direct control rights, the percentage of the business entity owned by the taxpayer shall be presumed to be not less than the taxpayer’s percentage of the overall voting or other direct control rights.”[11]
  • “For any profits interests in a business entity, the percentage of the entity owned by the taxpayer shall be presumed to be not less than the maximum such percentage interest of the entity’s profits the taxpayer may earn, without respect to whether such profits interest is subject to a condition precedent that has not yet been met.”[12]

Apart from the extremes of publicly traded assets and sole proprietorships, “all interests in any business entities, including all equity and other ownership interests, all debt interests, and all other contractual or noncontractual interests,” would be rebuttably “presumed” to be governed by the following equation:[13]

  • “FMV” means fair market value.
  • “BV” means book value.
  • “BP” is “the annual book profits of the business entity—as averaged over the current tax year and the preceding two tax years—according to generally accepted accounting principles,” but not below zero.
  • “TP” is the taxpayer’s percentage interest.[14]

There is a special rule for a private equity entity whereby the fair market value of such entity must at least be equal to the fair market value of each entity it owns minus the private equity entity’s liabilities.  “In the case of a private equity entity, this value shall not be less than the sum of the value (as determined under [the above formula]) of each entity owned by the private equity entity, over the liabilities (other than profits interests) of the private equity entity.”[15] “‘Private equity entity’ means a business entity, other than a publicly traded entity, mutual fund, or exchange-traded fund, that engages primarily in the business of investing in other businesses.”[16]

A limited degree of discretion is given to the FTB and the taxpayer regarding valuations. “The Board may permit a taxpayer to compute book value and book profits using an accounting method other than generally accepted accounting principles if the business to be valued consistently maintains its books and records and reports income and expenses using such other method.”[17] The presumption regarding the ownership interests of entities regarding control and profits, as well as the specified calculation of fair market value for entities other than publicly traded assets and sole proprietorships, can be rebutted by either the FTB or the taxpayer if the proponent “can demonstrate with clear and convincing evidence” that these rules “would substantially overstate or understate the actual value of the business entity owned by the taxpayer or the percentage owned by the taxpayer.”[18] The term “clear and convincing evidence” has a well-established meaning in caselaw, requiring proof “sufficiently strong to command the unhesitating assent of every reasonable mind.”[19]

In such cases, “the taxpayer or the Board may instead submit a certified appraisal of the percentage of the business entity owned by the taxpayer and then use the certified appraisal value in place of the presumed percentage method.”[20]

Fair Market Value of Trusts

            “An individual’s net worth includes the net worth of any grantor trust of that individual.”[21] For the 2026 Billionaire Tax Act, a “grantor trust” is defined as “any trust which would be a grantor trust for purposes of the income tax, and also any trust the assets of which would be included in the estate of the grantor for purposes of federal transfer tax.”[22] There are two sets of rules regarding nongrantor trusts. Solely “[f]or purposes of determining whether an individual’s net worth is in excess of $1 billion ($1,000,000,000) or $1.1 billion ($1,100,000,000),” thereby triggering the Proposition 40 tax, “net worth shall include the value of property held by any trust (other than a grantor trust or tax-exempt trust) to which the individual transfers or has transferred property.”[23]

            The second set of rules applies to “all purposes.” Net worth would “include the value of property held by any trust (other than a grantor trust or tax-exempt trust) to which the individual transfers property in 2026, and seventy-five percent of the value of such property transferred in 2025,” but only “[t]o the extent consistent with the U.S. and California Constitutions.”[24] Assets are at risk of being taxed thrice, or more precisely, 2.75 times. For example, if a single individual created a non-grantor trust in 2025 and funded it with $1 million in that year and another $1 million in 2026, the individual would be taxed both on the value of the trust at the end of 2026 plus 75% of the $1 million transferred in 2025, while the trust would be separately taxed on its value.    

“If more than one individual has transferred property to any such trust,” the net worth is increased by the proportion of the trust reflecting the individual’s proportionate contribution to the trust.[25] A trust beneficiary, “whether or not the trust is resident in California,” would “be deemed the owner of the trust’s assets to the extent that the assets are distributable to the beneficiary, whether distributed or not,” unless “the trust is an applicable trust,” and therefore taxed itself under Proposition 40.[26]


[1] Nothing should be construed as support of or opposition to Proposition 40 by the author or The Burton Law Firm. 

[2] Proposed RTC § 50308(f).

[3] Proposed RTC § 50303(a). As if it were not already incorporated into the definition, the proposed statute elaborates that “[t]he fair market value of an asset shall not be” either “[t]he price that a forced sale of the property would produce; or [t]he sales price in a market other than that in which the property is most

commonly sold to the public, if the price in such market would result in a lower fair market value, except in the case of property subject to Section 423, relating to the valuation of restricted open-space land.” Proposed RTC § 50303(a).

[4] Proposed RTC § 50309(b).

[5] However, real estate is excluded from net worth. Proposed RTC § 50303(c)(4).

[6] Proposed RTC § 50302(b).

[7] Proposed RTC § 50303(c)(10).

[8] Proposed RTC § 50303(c)(10).

[9] Proposed RTC § 50303(c)(1).

[10] Proposed RTC § 50303(c)(2).

[11] Proposed RTC § 50303(c)(3)(C).

[12] Proposed RTC § 50303(c)(3)(D).

[13] Proposed RTC § 50303(c)(3)(E).

[14] In text form: “[T]he fair market value of those interests at the end of any tax year shall be presumed to be the sum of the book value of the business entity according to generally accepted accounting principles as of the end of the tax year plus a present-value multiplier of 7.5 times the annual book profits of the business entity—as averaged over the current tax year and the preceding two tax years, if available—according to generally accepted accounting principles, with this entire sum then multiplied by the percentage of the business entity owned by the taxpayer as of the end of the tax year.” Proposed RTC § 50303(c)(3)(E).

[15] Proposed RTC § 50303(c)(3)(E).

[16] Proposed RTC § 50308(i).

[17] Proposed RTC § 50303(c)(3)(E).

[18] Proposed RTC § 50303(c)(3)(F).

[19] Conservatorship of O.B., 9 Cal. 5th 989, 998 fn.2 (2020).

[20] Proposed RTC § 50303(c)(3)(F).

[21] Proposed RTC § 50303(c)(6)(A).

[22] Proposed RTC § 50308(e).

[23] Proposed RTC § 50303(c)(6)(B).

[24] Proposed RTC § 50303(c)(6)(B).

[25] Proposed RTC § 50303(c)(6)(B).

[26] Proposed RTC § 50303(c)(6)(C).
Categories
News

A Multi-Billion-Dollar Question: What is a Limited Partner?

Introduction

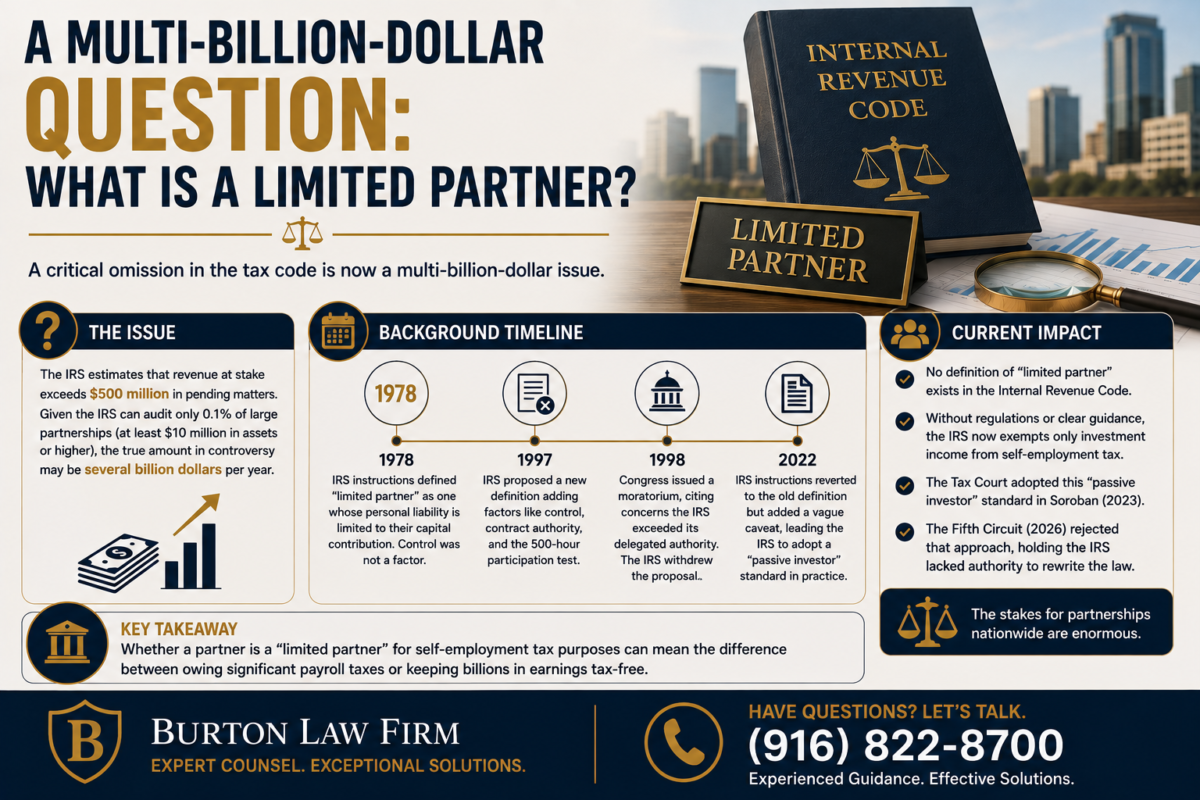
Wages are generally subject to payroll taxes. Self-employed individuals are instead subject to a separate yet parallel tax designed to correspond to the payroll tax burden.[1] Self-employment income generally includes “distributive shares of partnership income in net earnings from self-employment.”[2] Section 1402(a)(13) provides an exception excluding “the distributive share of any item of income or loss of a limited partner, as such, other than guaranteed payments described in section 707(c) to that partner for services actually rendered to or on behalf of the partnership to the extent that those payments are established to be in the nature of remuneration for those services.”[3] However, the Internal Revenue Code does not define the term “limited partner.” This is a critical omission. “The IRS estimates that revenue at stake exceeds $500 million, just in pending matters.” Since the IRS can only audit, let alone litigate, 0.1% of large partnerships (at least $10 million in assets or higher), the true amount in controversy may well be several billion dollars per year.

Background

The limited partner exception to the self-employment tax came into effect in 1978. In the same year, “the IRS issued partnership tax return instructions that defined ‘Limited Partner’ as ‘one whose potential personal liability for partnership debts is limited to the amount of money or other property that the partner contributed or is required to contribute to the partnership.’”[4] Control over the partnership was not mentioned as a factor for this exception for over forty years.

Nevertheless, the IRS attempted to define a “limited partner, as such,” in 1997. “The proposed regulation provided that an individual would not be treated as a limited partner if the individual had personal liability for partnership debts, had authority to contract on behalf of the partnership, or participated in the partnership’s trade or business for more than 500 hours during the partnership’s taxable year.”[5]  The IRS did not alter its instructions to conform to its proposed regulations. The proposed regulations caused some alarm in Congress, which issued a moratorium on that proposed regulation until 1998, citing concerns that the IRS exceeded its delegated authority. The IRS did not pursue the regulation further.

Suddenly on January 7, 2022, published instructions “defining ‘limited partner’ in the same way the instructions did in the past,” but with “a vague possible caveat: ‘However, whether a partner qualifies as a limited partner for purposes of self-employment tax depends upon whether the partner meets the definition of a limited partner under section 1402(a)(13).’”[6] There was no indication that this definition contradicted the definition of limited partner given earlier in the instructions. This remains the case today.[7] Yet, without a regulation or even clear published guidance, the IRS began to limit the limited partner definition to exempt only investment income.[8] This “passive investor” standard was adopted by the Tax Court in 2023 through Soroban Capital Partners LP v. Commissioner. The 5th Circuit reversed the Tax Court’s definition in a separate case, Sirius Solutions, L.L.L.P. v. Commissioner, on January 16, 2026: “We hold that a ‘limited partner’ in § 1402(a)(13) is a limited partner in a state-law limited partnership that is afforded limited liability.”[9] The IRS petitioned for an en banc rehearing of this decision by the 5th Circuit. The court denied this petition, yet withdrew its prior opinion and substituted a new one on August 12, 2026.

K Alain, L.L.L.P. v. Commissioner

The case was retitled from Sirius Solutions, L.L.L.P. v. Commissioner to K Alain, L.L.L.P. v. Commissioner, to reflect the partnership’s name change. The new opinion is less than half the old opinion’s length and was written as if the old opinion never existed. Although the 5th Circuit did not discuss why the old opinion was withdrawn, there are material differences between the opinions despite the same basic ruling in the taxpayer’s favor. The old opinion created a bright-line rule that any partner with limited liability under state law is a limited partner, adopting the historical partnership tax return instructions issued by the IRS. In contrast, the new opinion stated: “We hold the ordinary public meaning of this phrase is a partner who plays no significant role in managing or running a business.”[10]

K Alain, L.L.L.P. v. Commissioner used dictionaries, contemporaneous academic treatises, nontax contemporaneous caselaw, and state law to reach “the ordinary understanding of ‘limited partner’ in 1977,” when the exception was enacted.[11] “At bottom, all relevant sources suggest that, in 1977, the ordinary public meaning of ‘limited partner’ included a partner who did not play a significant role in managing or running the business.”[12] This was a straightforward matter, according to the 5th Circuit: “Here, we apply the plain text. Nothing more.”[13] It rejected “the dissent’s parade of horribles,” explaining that “this court’s job is to discern and apply the law’s plain meaning as faithfully as we can, not ‘to assess the consequences of each approach and adopt the one that produces the least mischief.”[14] Although Alain cited the historical interpretation of the IRS as a reason for its ruling, the ruling did not depend on prior practice.

Alain’s withdrawn opinion and over four decades of IRS instructions held that a limited partner is simply a partner with limited liability. The 5th Circuit rejected that standard by adding the condition that the partner must “not play a significant role in managing or running the business.”[15] Alain did not explain why. The taxpayer in Alain won in that the 5th Circuit vacated the unfavorable Tax Court judgment. However, the partnership could still lose on remand. The Tax Court is now tasked with determining whether the limited partners’ involvement was “significant.” Alain gave little guidance on how that is accomplished. Instead, Alain issued a sharp rebuke of the Tax Court for its opinion in Soroban:

With just a few sentences of operative analysis—citing no contemporary textual authority—the Tax Court insisted that ‘limited partner, as such’ somehow denoted more than limited liability. The Tax Court then said, without significant analysis, that this required a ‘passive investor’ rule. The Tax Court made no attempt to ground its rule in the original public meaning of “limited partner” in 1977.[16]

This may influence whether the Tax Court will follow Alain outside of the 5th Circuit.

Broader Context

Alain did not settle the controversy over the limited partner exception to the self-employment tax. The Tax Court “adheres to the doctrine of stare decisis” and “takes seriously its obligation to facilitate uniformity in the tax law” as a nationwide court.[17] “When one of our decisions is reversed by an appellate court, the Court will thoroughly reconsider the problem in the light of the reasoning of the reversing appellate court and, if convinced thereby, follow the higher court.”[18] Yet if “convinced that our original decision was right, the proper course is to follow our own honest beliefs until the Supreme Court decides the point.”[19] Nevertheless, it will follow a contrary appellate decision when both the decision is “squarely on point,” and an appeal from the Tax Court would rest in the circuit court that issued the contrary decision.[20] “To do otherwise would be futile and wasteful given the inevitable reversal from the appellate court.”[21] Therefore, the Tax Court will likely comply with Alain within the 5th Circuit, but it will still need to be convinced to apply it elsewhere.

The self-employment tax and the payroll taxes fund Social Security and Medicare. This funding will be insufficient for Social Security beginning in 2033 and for Medicare beginning in 2033, whereby only 77% and 89% of their respective scheduled benefits will be distributed.


[1] Overview of the Federal Tax System as in Effect for 2025 at 27.

[2] Soroban Capital Partners LP v. Commissioner, 161 T.C. 310, 316 (2023).

[3] IRC § 1402(a)(13).

[4] Alain v. Commissioner, No. 24-60240, 2026 U.S. App. LEXIS 24366, at *13 (5th Cir. Aug. 12, 2026).

[5] Soroban Capital Partners LP v. Commissioner, 161 T.C. 310, 317 (2023).

[6] Sirius Sols. L.L.L.P. v. Commissioner, 165 F.4th 374, 380 (5th Cir. 2026) withdrawn by Alain v. Commissioner, No. 24-60240, 2026 U.S. App. LEXIS 24366(5th Cir. Aug. 12, 2026).

[7] Thus, the 2025 Instructions for Form 1065 states at page 3 that: “A limited partner is a partner in a partnership formed under a state limited partnership law, whose personal liability for partnership debts is limited to the amount of money or other property that the partner contributed or is required to contribute to the partnership.” Furthermore, the instructions provide at page 44: Generally, a limited partner’s share of partnership income (loss) isn’t included in net earnings (loss) from self-employment. Limited partners treat as self-employment earnings only guaranteed payments for services they actually rendered to, or on behalf of, the partnership to the extent that those payments are payment for those services. However, whether a partner qualifies as a limited partner for purposes of self-employment tax depends on whether the partner is considered a limited partner under section 1402(a)(13).”

[8] The 5th Circuit emphasized the magnitude of this shift: 

The Commission’s position in this case is that it can change the meaning of “limited partner” from (A) “limited liability alone,” which was the pre-Soroban standard, to (B) Soroban’s “passive investor” standard—with zero action from Congress to amend § 1402(a)(13)’s text. Perhaps that level of administrative control over billions or trillions of dollars in tax liability is permissible as a general matter. But at a minimum, even assuming the Commissioner can unilaterally effectuate such changes through tax instructions, its instructions must comport with the original public meaning of the text enacted by Congress in 1977.

Alain v. Commissioner, No. 24-60240, 2026 U.S. App. LEXIS 24366, at *14 (5th Cir. Aug. 12, 2026).

[9] Sirius Sols. L.L.L.P. v. Commissioner, 165 F.4th 374, 388 (5th Cir. 2026) withdrawn by Alain v. Commissioner, No. 24-60240, 2026 U.S. App. LEXIS 24366(5th Cir. Aug. 12, 2026).

[10] Alain v. Commissioner, No. 24-60240, 2026 U.S. App. LEXIS 24366, at *6 (5th Cir. Aug. 12, 2026).

[11] Id. at *9.

[12] Id. at *11.

[13] Id.

[14] Id.(omitting internal quotation marks).

[15] Id.

[16] Id. at *12(omitting internal citations; emphasis added by Alain).

[17] Mukhi v. Comm’r of Internal Revenue, 163 T.C. No. 8 at *2 (2024).

[18] Id.(omitting internal quotation mark and ellipsis).

[19] Id.(omitting internal quotation mark and brackets).

[20] Id.(omitting internal brackets).

[21] Id.(omitting internal quotation marks).

Inspector General: IRS is Struggling with Partnership Audits

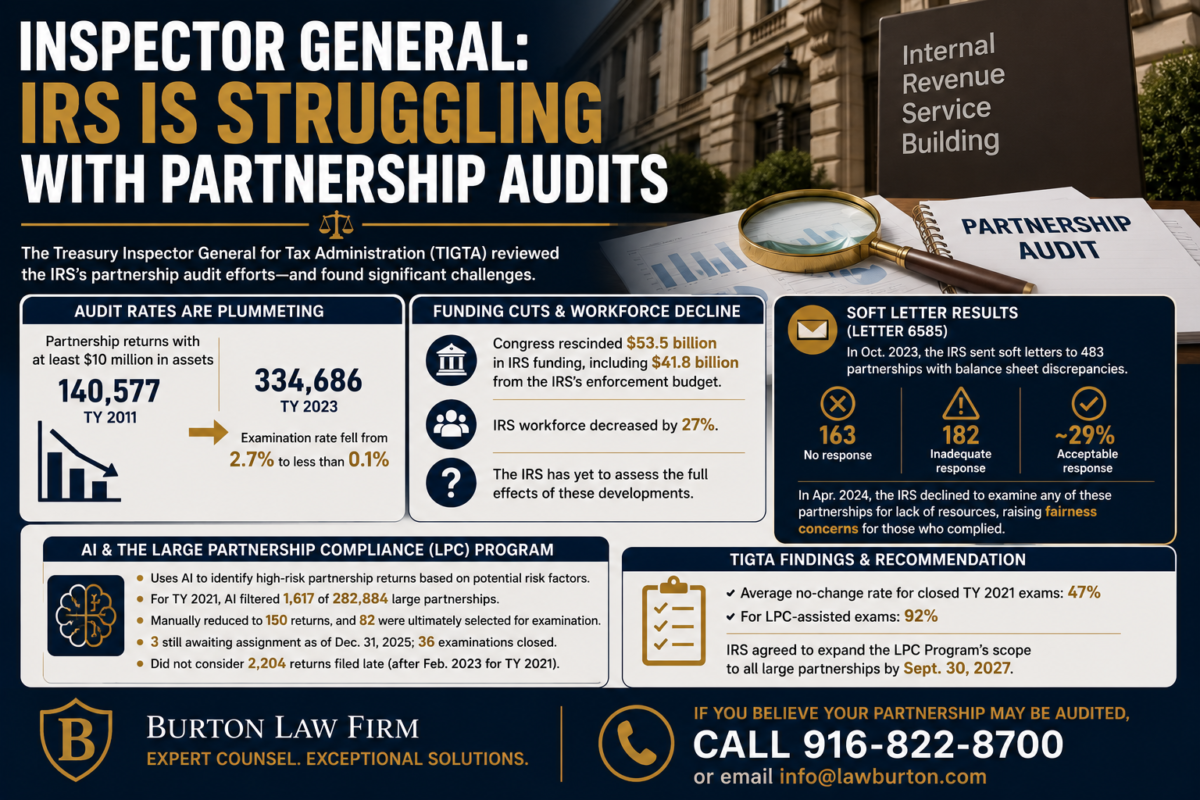
The IRS received 140,577 returns for Tax Year (TY) 2011 for partnerships with at least $10 million in assets. This increased to 334,686 returns for TY 2023. Meanwhile, the examination rate for these partnerships fell from 2.7% to less than 0.1%. The IRS previously set the target audit rate for TY 2026 at 1%. However, that ambition was premised on the $79.4 billion the IRS received through the Inflation Reduction Act. Instead, Congress rescinded $53.5 billion in funding, including $41.8 billion from the IRS’s enforcement budget. Furthermore, the IRS’s workforce decreased by 27%. The IRS has yet to assess the effects of these developments. The Treasury Inspector General for Tax Administration (TIGTA) reviewed the situation.

In October 2023, the IRS issued a letter to 483 large partnerships with balance sheet discrepancies (the assets did not equal equity plus liabilities). This letter was Letter 6585, Soft Letter Pass-Through Entity Campaign. “A soft letter is not an examination activity but can be a way to alert taxpayers of potential noncompliance.” Of these 483 letters asking for documentation, 163 simply lacked a response, and 182 had an inadequate response. Only about 29% had responses acceptable to the IRS. In April 2024, the IRS declined to examine any of these partnerships for lack of resources. TIGTA sympathized with the partnerships that complied. “We believe the decision not to conduct examinations on partnerships that did not respond or whose responses were rejected presents a fairness issue and a burden for partnerships who potentially spent time and money responding to the letter.” The IRS explained that less than 12 months remained before the statute of limitations expired. TIGTA countered that it was the IRS’s own fault for delaying.

The TIGTA report contained precious information regarding IRS examination practices. The IRS generally initiates examinations only when there are more than 12 months left before the statute of limitations period bars action. The Large Business and International (LB&I) Division is tasked with administering partnership tax returns. In 2018, the LB&I Division launched the Partnership Model Project, which classifies partnership returns as high, medium, or low risk through a weighted algorithm of “potential risk factors.” “High-risk returns are sent to examiners. Beginning in 2021, the LB&I Division has used AI for this process through the Large Partnership Compliance (LPC) Program. This AI is trained through the manual identification of “high-risk domestic and international business transactions that affect income, gains, expenses, or losses in the largest partnerships.”  For TY 2021, the LPC Program filtered 1,617 out of 282,884 large partnerships for potential examination. This was manually reduced to 150 “returns spread across a distribution of industry categories within the large partnership population.” In turn, 82 were ultimately selected for examination. Of these, 3 still awaited assignment to an examiner as of December 31, 2025, but the LB&I Division closed examination on 36 other partnerships by that time. Interestingly, the LPC Program did not consider 2,204 large partnership returns simply because they were filed too late (after February 2023 for TY 2021). The AI risk assessment was only conducted once. Relatively few of the TY 2021 examinations were attributable to the LPC Program. The IRS agreed to TIGTA’s recommendation to expand the LPC Program’s scope to all large partnerships by September 30, 2027. This may be beneficial for large partnerships. The average no-change rate for closed examinations TY 2021 returns was 47%, yet it was 92% for the closed examinations selected with the assistance of the LPC Program.

If you believe your partnership may be audited, please call 916-822-8700 or email info@lawburton.com.

Categories
News

The 2026 Billionaire Tax Act Part Two: Rate, Reporting, and Payment

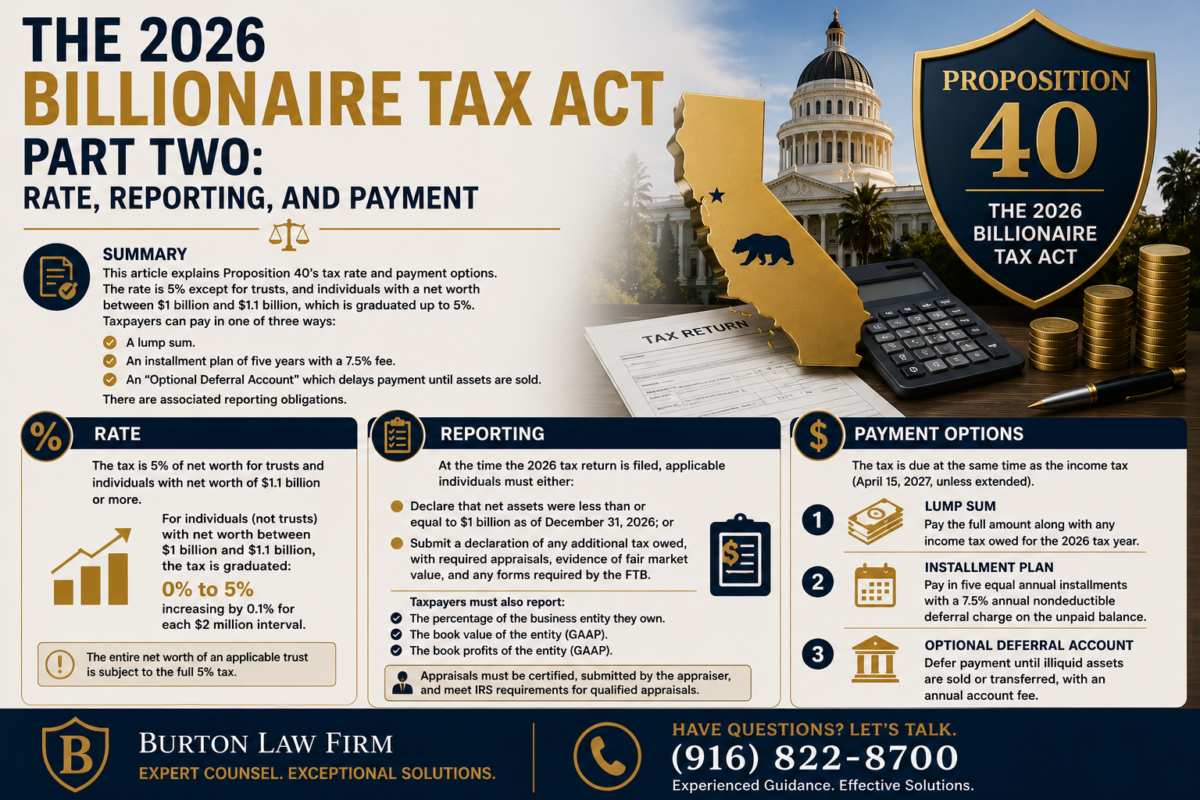
Welcome to part two of this series on Proposition 40, “The 2026 Billionaire Tax Act.”[1] This article discusses the tax rate and how taxpayers can pay the amount due under Proposition 40. The rate is 5% except for trusts, individuals with a net worth below $1.1 billion (but above $1 billion), which is graduated to 5%. There are three ways to pay:

  1. A lump sum.
  2. An installment plan of five years with a 7.5% fee.
  3. An “Optional Deferral Account” which delays payment until assets are sold.

There are associated reporting obligations. For most people, this will be a box to tick, while for others it will be a full disclosure of their net worth, together with appraisals.

Rate

“[T]he tax imposed is 5 percent of the net worth of such individual or trust,” except that “[i]n the case of an individual (other than a trust),” the tax rate would decrease by “0.1 percentage point (but not below zero) for each $2 million” below $1.1 billion in an individual’s net worth.[2] Thus, the tax rises from 0% to 5% for individual (not trust) net worths from $1 billion to $1.1 billion, increasing by 0.1% point for each $2 million interval. Moreover, the entire net worth of an applicable trust is subject to the full 5% tax even if the net worth is less than $1 billion.

Reporting

Each “California resident individual” required to file a California income tax return or an “applicable individual” would need to “[a]t the time a return is filed” for the 2026 tax year either:[3]

  • Declare that their net assets were less than or equal to $1 billion as of December 31, 2026.[4]
  • “Submit a declaration of the amount of any additional tax that is owed” under the 2026 Billionaire Tax Act, “together with any required appraisals or other evidence of fair market value,” and “any forms created by the Franchise Tax Board for calculating any additional tax owed under.”[5]

Furthermore, each “taxpayer” of the Proposition 40 tax must report all of the following:[6]

  • “The percentage of the business entity owned by the taxpayer.”[7]
  • “The book value of the business entity as of the end of the tax year, determined according to generally accepted accounting principles.”[8]
  • “The book profits of the business entity in the tax year according to generally accepted accounting principles.”[9]
    • For the purposes of this particular reporting requirement, “‘the tax year’ of the business entity means the latest tax year of the business entity ending within or with the tax year of the taxpayer.”[10]

If the taxpayer lacks information regarding such a business entity’s book value or book profits, “and also lacks the right to obtain that information, the taxpayer must submit a certified appraisal of all of the taxpayer’s interests in the business entity.”[11] A sole proprietorship’s assets would be treated and reported as the individual’s assets.[12] Any certified appraisal made for the purposes of the 2026 Billionaire Tax Act would need to be submitted to the FTB by the appraiser, along with information identifying the pertinent taxpayer.[13] The 2026 Billionaire Tax Act would borrow the requirements for a qualified appraiser and a qualified appraisal from the IRS regulations.[14]

Payment

The tax would be due at the same time as the income tax.[15] The tax may be paid in three ways:

  • A lump sum “along with any income tax owed for the 2026 tax year.”[16]
  • “[A]nnually in five equal installments commencing in the year the tax is due with each subsequent annual installment payment also being subject to an annual nondeductible deferral charge of 7.5 percent of the remaining unpaid balance.”[17]
  • An “optional deferral account” (ODA) in cases whereby Proposition 40’s tax liability would be in “excess of the combined total value of all of the individual’s publicly traded assets.”[18] In effect, an ODA functions as a sort of receivership or trust policing the relationship between the taxpayer and their illiquid assets, generally taxing 5% of distributions in addition to the income tax:
    • An ODA is a contract that “shall be legally binding on the taxpayer, and also on the taxpayer’s estate and assigns, until” the tax liability is fully paid.[19] This obliges the taxpayer to:
      • File all required forms regarding the ODA regardless of residency.[20]
        • “Failure to make annual reports and file any required forms shall be treated as a breach of contract and shall also be subject to the same penalties as a failure to file income tax forms for California residents who are required to file income tax forms.”[21]
      • “Reconcile and pay all tax liabilities that may arise as a result of the ODA.”[22]
      • Submit to California’s personal jurisdiction regarding the ODA.[23]
    • “A taxpayer may maintain only one ODA.”[24]
    • The ODA may attach to assets only to the extent that the wealth tax liability exceeds the taxpayer’s total sum of publicly traded assets.[25]
    • “[A]ny material distribution transactions made with regard to the ODA” must be annually reported.[26]
      • This generally includes any “withdrawal of money, property, or other value from” ODA assets and any “transaction with the taxpayer, or a related person to the taxpayer, that has the effect of transferring any assets or value of assets to which an ODA is attached without also transferring the ODA obligations.”[27]
      • However, this excludes “ordinary and necessary transactions for maintaining or increasing the value of assets to which an ODA is attached and that would not have the effect of distributing any profits, dividends, or other payments to owners for the use of capital, or similar transfers.”[28]
      • The FTB would be empowered and charged with the responsibility for specifying what transactions are and are not material distribution transactions.[29]
    • Material distribution transactions would be taxed at 5% (in addition to the income tax).[30]
    • An ODA could only be closed by taxing all remaining ODA assets at 5%.[31]

[1] Nothing should be construed as support of or opposition to Proposition 40 by the author or The Burton Law Firm. 

[2] Proposed RTC § 50301(b).

[3] Proposed RTC § 50301(d).

[4] Proposed RTC § 50301(d)(1)(referencing the “valuation date” which is December 31, 2026, pursuant to proposed RTC § 50308(o)).

[5] Proposed RTC § 50301(d)(2).

[6] Proposed RTC § 50303(c)(3)(A). The term “taxpayer” is undefined for these purposes. However, its plain meaning would limit its applicability to persons actually liable for taxes under Proposition 40.

[7] Proposed RTC § 50303(c)(3)(A)(i).

[8] Proposed RTC § 50303(c)(3)(A)(ii).

[9] Proposed RTC § 50303(c)(3)(A)(iii).

[10] Proposed RTC § 50303(c)(3)(A)(iii).

[11] Proposed RTC § 50303(c)(3)(B).

[12] Proposed RTC § 50303(c)(2).

[13] Proposed RTC § 50305(a). Ignorance does not necessarily seem to excuse the appraiser’s duty. It is possible that an appraiser may be required to affirmatively inquire.

[14] Proposed RTC § 50305(b).

[15] Proposed RTC § 50301(c). This would be April 15, 2027, a Thursday. However, an official disaster proclamation may delay its due date. RTC § 18572.

[16] Proposed RTC § 50301(c).

[17] Proposed RTC § 50301(c).

[18] Proposed RTC §§  50301(b) & 50304(a).

[19] Proposed RTC § 50304(b).

[20] Proposed RTC §§ 50304(a)(1) & 50304(d).

[21] Proposed RTC § 50304(d).

[22] Proposed RTC § 50304(a)(2).

[23] Proposed RTC § 50304(a)(3).

[24] Proposed RTC § 50304(c).

[25] Proposed RTC § 50304(c).

[26] Proposed RTC § 50304(d).

[27] Proposed RTC § 50304(f).

[28] Proposed RTC § 50304(g).

[29] Proposed RTC § 50304(h).

[30] Proposed RTC §§ 50304(e) & 50304(i).

[31] Proposed RTC § 50304(l).

Categories
News

The 2026 Billionaire Tax Act Part One:

Introduction, Structure, and Applicability

Introduction

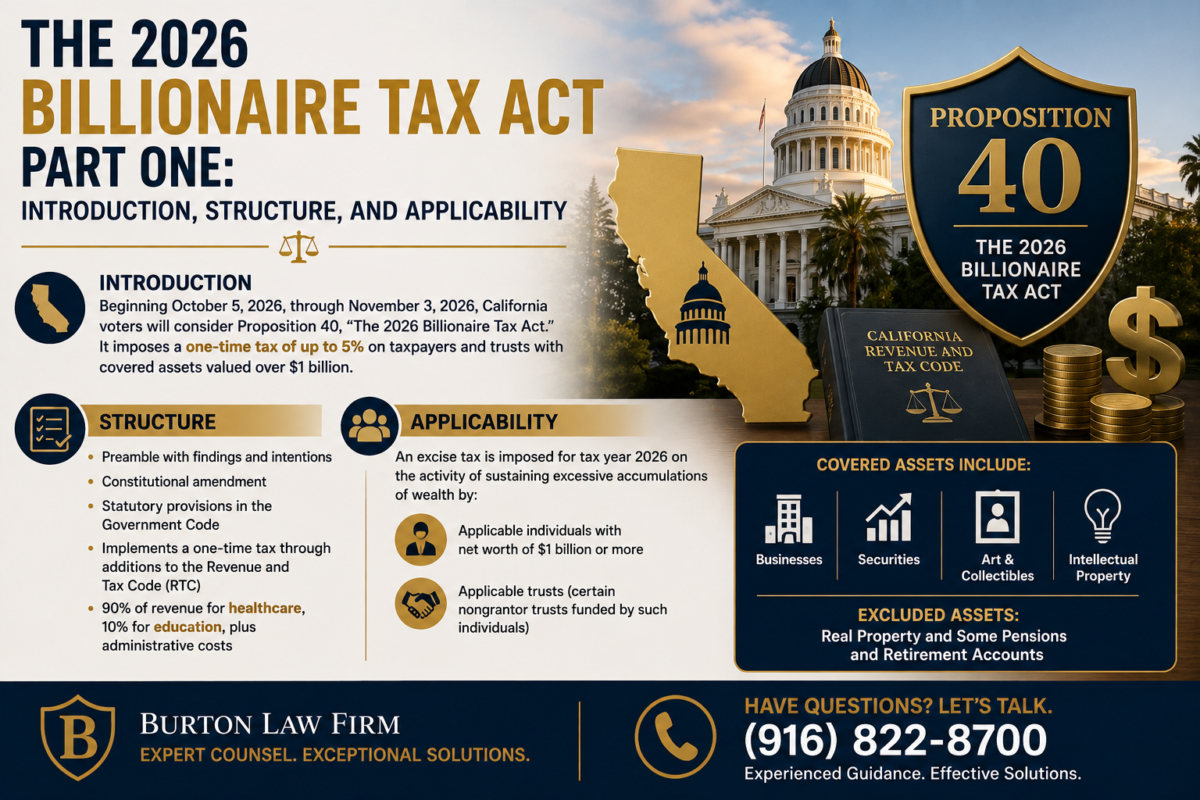
Beginning on October 5, 2026, and ending on November 3, 2026, California voters will consider Proposition 40, “The 2026 Billionaire Tax Act.” As part of Proposition 40’s official summary, prepared by California’s Attorney General, states: It “[i]mposes one-time tax of up to 5% on taxpayers and trusts with covered assets valued over $1 billion; covered assets include businesses, securities, art, collectibles, and intellectual property, but exclude real property and some pensions and retirement accounts.” However, there are many nuances varying from the graduated rate to the definition of “net worth” that will be comprehensively covered in this new series of posts in the coming weeks.[1]

Structure

Proposition 40 is divided into a preamble listing its findings and intentions, a constitutional amendment, and several statutory sections. The preamble explains that Proposition 40 is necessary (according to its creators) to adjust to decreases in federal public health funding. More fundamentally, Proposition 40 cites distributional justice concerns. For example, it claims that: “California has around 200 billionaires who collectively possess an astonishing $2 trillion in wealth. These billionaires pay less than 1.5% of their total wealth in annual taxes, including federal, state, and local taxes, according to leading economic estimates-a small fraction of what ordinary Californians pay.”[2]

The constitutional amendment “authorizes and enables a one-time tax on the accumulated wealth of California billionaires.”[3] Yet, most of the constitutional amendment governs the spending of the 2026 Billionaire Tax Act’s revenue and is followed by implementing sections in the Government Code. Ninety percent of the total revenue (anticipated by supporters to be $100 billion) would be devoted to healthcare, with the rest for public education, apart from yearly administrative expenses for the Franchise Tax Board in enforcing the “2026 Billionaire Tax Act.”[4] The bulk of Proposition 40 consists of additions to the Revenue and Tax Code of California (“RTC”) to implement the wealth tax by the Franchise Tax Board (“FTB”). 

Applicability

“An excise tax is imposed for tax year 2026 on the activity of sustaining excessive accumulations of wealth by applicable individuals with net worth of $1 billion dollars ($1,000,000,000) or more, and on applicable trusts.”[5] A 2026 Billionaire Tax Act taxpayer would be either an “applicable individual” with a net worth of at least $1 billion or an “applicable trust.” The term “applicable trust” has a more complex definition, but it is intended to encompass nongrantor trusts that received contributions by an “applicable individual” with a net worth of at least $1 billion.

Applicable Individual

An “‘[a]pplicable individual’ means, for the 2026 tax year, any individual who is a resident of this State, within the meaning of Sections 17014 and 17015.5, as of the tax obligation date.”[6] The tax obligation date is January 1, 2026. Therefore, an individual meeting the wealth threshold is liable for the tax if they were considered a resident of California under the normal state income tax for any part of the year as of January 1, 2026. “[A] married couple shall be considered as one individual” for the purposes of the tax liability and the filing requirement.[7]

Applicable Trust

An “applicable trust” is defined as a “trust” for which all of the following are true:[8]

  • The trust is not a grantor trust for the purposes of the income tax.
  • The trust is not a tax-exempt trust under IRC § 501.
  • An “applicable individual” transferred property to the trust, wherein all of the following are true.
    • The applicable individual is “still living.”
      • Proposition 40 does not specify when the applicable individual must be alive.
    • The applicable individual has a “net worth” of at least $1 billion.
      • Proposition 40 does not specify when the net worth threshold must be met for these purposes.

The transfer by such an applicable individual is deemed accomplished if performed by “any entity that would constitute a related person with respect to such individual.”[9] Proposition incorporates Internal Revenue Code §§ 267 and 318 (“as of January 1, 2026”) for the definition of a related person.[10] This generally includes close family members and controlled entities. However, a “related person” also includes “any other person so specified by regulations adopted by the Board.”[11] “If more than one individual has transferred property to such trust,” the trust portion which is “treated as an applicable trust” is the portion proportionate to such an applicable individual’s transfer (including through a related entity), “holds to the total value of assets transferred to the trust.”[12] Thus, if an applicable individual (still living with a billion dollars) contributes to a trust alongside a nonapplicable individual in equal proportions, 50% of the trust would be deemed the applicable trust. This definition is modified by two different elections:

  • “[A]ny trust may elect to be an applicable trust by notifying the Board of such election by any method the Board may designate.”[13]
  • “An individual with net worth of $1 billion ($1,000,000,000) or more who has transferred property to an applicable trust may elect to treat such trust as part of the net worth of such individual by notifying the Board of such election by any method the Board may designate.”[14] 

Therefore, a trust can elect to be an applicable trust, and an individual 2026 Billionaire Tax Act taxpayer may elect to incorporate the trust’s assets into their own net worth.

            Please visit next week for more information about Proposition 40 in this new weekly series of posts.


[1] Nothing should be construed as support of or opposition to Proposition 40 by the author or The Burton Law Firm. 

[2] Proposition 40, § 2(r).

[3] Proposed California Constitution, Art. XIII, § 37(a).

[4] Proposed California Constitution, Art. XIII, § 37(d).

[5] Proposed RTC § 50301(a).

[6] Proposed RTC § 50308(a).

[7] Proposed RTC § 50301(a).

[8] Proposed RTC § 50308(b).

[9] Id.

[10] Proposed RTC § 50308(k).

[11] Id.

[12] Proposed RTC § 50308(b).

[13] Id.

[14] Id.

Categories
News

9th Circuit: Jack Daniels is not Diluted by a Dog Toy

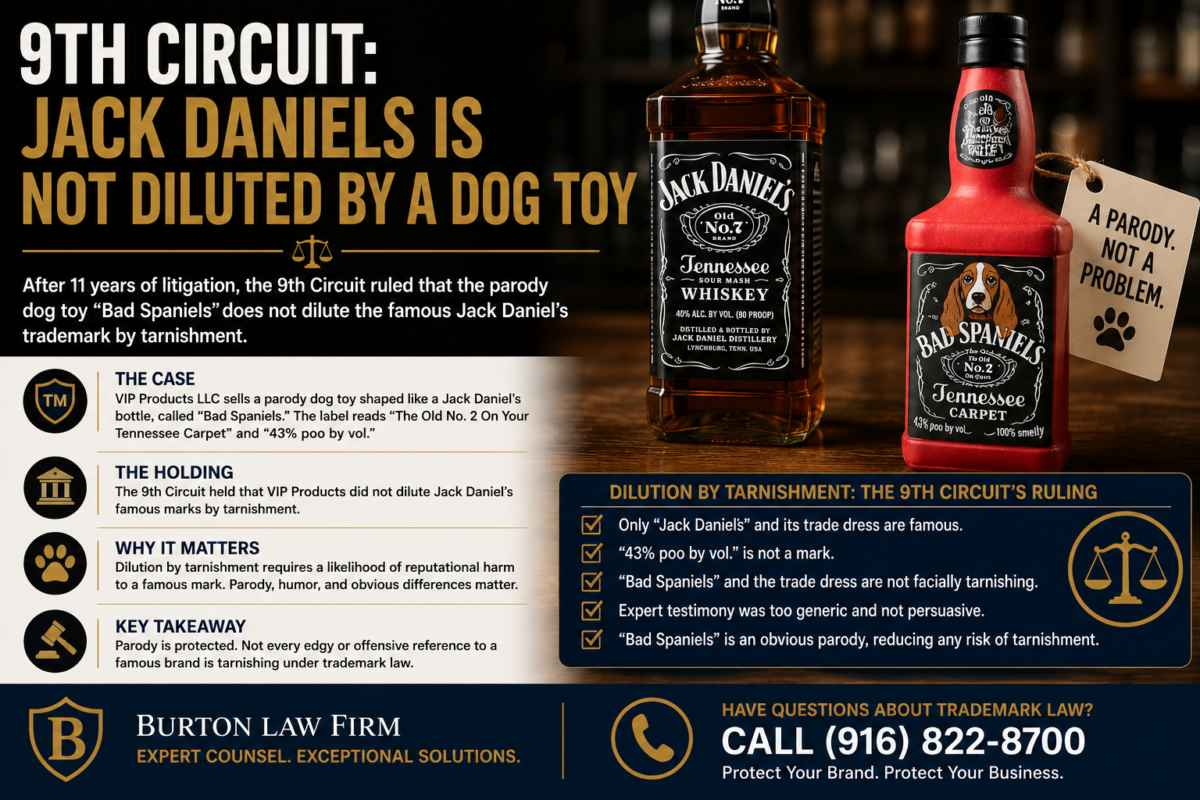
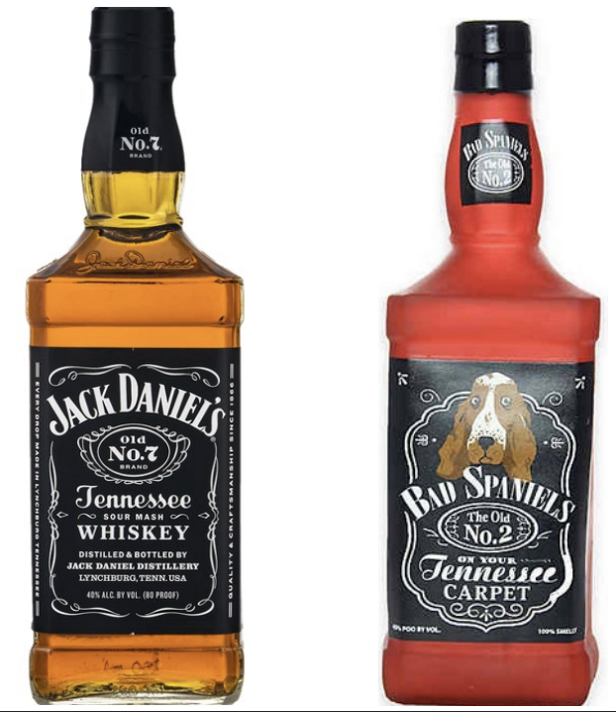
After 11 years, the litigation between Jack Daniel’s Properties, Inc. and VIP Products LLC regarding a dog toy’s resemblance to liquor ended in VIP Products LLC’s favor. VIP Products LLC sells dog toys parodying Jack Daniel’s beverage. The toys are similarly shaped (but of different materials) and are called “Bad Spaniels,” with a descriptive label of “The Old No. 2 On Your Tennessee Carpet” instead of “Old No. 7 Brand Tennessee Sour Mash Whiskey.” “The small print at the bottom substitutes ‘43% poo by vol.’ and ‘100% smelly’ for ‘40% alc. by vol. (80 proof).’”[1]

 The Lanham Act protects trademarks from confusion and dilution. This case already reached the Supreme Court in 2023, which instructed the 9th Circuit on the proper standard.[2] In turn, the 9th Circuit remanded the case to the district court. The district court ruled that the liquor cannot likely be confused with the dog toy, so the dog toy does not infringe on the liquor’s trademark. However, VIP Products LLC was held liable for dilution by tarnishment. VIP Products LLC appealed the dilution by tarnishment judgment, but Jack Daniel’s Properties, Inc. (JDPI) did not appeal the infringement ruling.

“Dilution by tarnishment means an association arising from the similarity between a mark or trade name and a famous mark that harms the reputation of the famous mark.”[3] Consumer confusion is irrelevant. However, this action “protects only famous marks from dilution and only where a similar junior mark is likely to tarnish its reputation because of the marks’ association.”[4] Here, the Jack Daniel’s liquor was compared with canine feces. Yet, “[t]he only marks JDPI proved famous are ‘Jack Daniel’s’ and its registered trade dress.”[5] “[A] mark is famous if it is widely recognized by the general consuming public of the United States as a designation of source of the goods or services of the mark’s owner.”[6] To qualify, “the mark must be a ‘household name.’”[7] The most objectionable detail, “43% poo by vol.” simply “does not mimic or reproduce any famous, similar mark. The equivalent language on JDPI’s product, ‘40% ALC. BY VOL. (80 PROOF),’ is not a mark.”[8] Therefore, “the only similar junior marks for our review are ‘Bad Spaniels’ and the dog toy’s trade dress.”[9] The “trade dress” is “the overall appearance of a product and its packaging.”[10] Neither the trade dress nor the name is facially tarnishing. “If a junior mark is not facially tarnishing, the context in which it is used may become relevant to the tarnishment analysis, depending on the facts of the case. For example, using a famous mark or a closely related depiction on a product that is of poor quality or pornographic or illegal may be tarnishing if the other requisites are met.”[11]

Here, the district court and JDPI relied on an expert witness to conclude that there is tarnishment. The 9th Circuit rejected that testimony as “generic.”[12] Although Dr. Simonson stated that aversion usually occurs when excrement is associated with a beverage, he did “not show that any association between either ‘Bad Spaniels’ and ‘Jack Daniel’s’ or between the products’ similar trade dress is likely to damage the reputation of JDPI’s famous marks.”[13] The studies he cited were not specific to this case, and “Bad Spaniels is a parodic dog toy not intended for human consumption.”[14] Finally, “Bad Spaniels is an obvious parody.”[15] Although not dispositive per se, “clarity of VIP’s parodic intent impacts the likelihood that JDPI’s famous marks are harmed by association with VIP’s product.”[16] This is so because “no matter how similar to its famous counterpart, a parodic junior mark ultimately relies upon a difference from the original mark, presumably a humorous difference, in order to produce its desired effect.”[17] Therefore, the 9th Circuit ordered the district court to vacate its permanent injunction and enter judgment in favor of VIP.

If you are considering registering a trademark or if you have any trademark questions, please call 916-822-8700 or email info@lawburton.com.


[1] Jack Daniel’s Props. v. VIP Prods. LLC, 599 U.S. 140, 150 (2023).

[2] Specifically, the Rogers test does not apply when “the use is at least in part for source identification—when the defendant may be trading on the good will of the trademark owner to market its own goods.” Jack Daniel’s Props. v. VIP Prods. LLC, 599 U.S. 140, 156 (2023)(omitting internal quotation marks). The “Rogers test requires dismissal of an infringement claim at the outset unless the complainant can show one of two things: that the challenged use of a mark has no artistic relevance to the underlying work or that it explicitly misleads as to the source or the content of the work.” Id. at 151(omitting internal quotation marks).

[3] VIP Prods., Ltd. Liab. Co. v. United States, No. 25-2027, 2026 U.S. App. LEXIS 23257, at *12 (9th Cir. Aug. 4, 2026)(omitting internal quotation marks).

[4] Id. at *13-14.

[5] Id. at *14.

[6] Id. at *16.

[7] Id.

[8] Id. at *14 fn.3.

[9] Id. at *14.

[10] Id. at *12.

[11] Id. at *20.

[12] Id. at *23.

[13] Id. at *23-24.

[14] Id. at *24(emphasis in original).

[15] Id. at *26.

[16] Id. at *27(omitting internal brackets and quotation marks).

[17] Id. at *28(omitting internal quotation mark).

Categories
News

 Right to Moonshine Causes Circuit Split

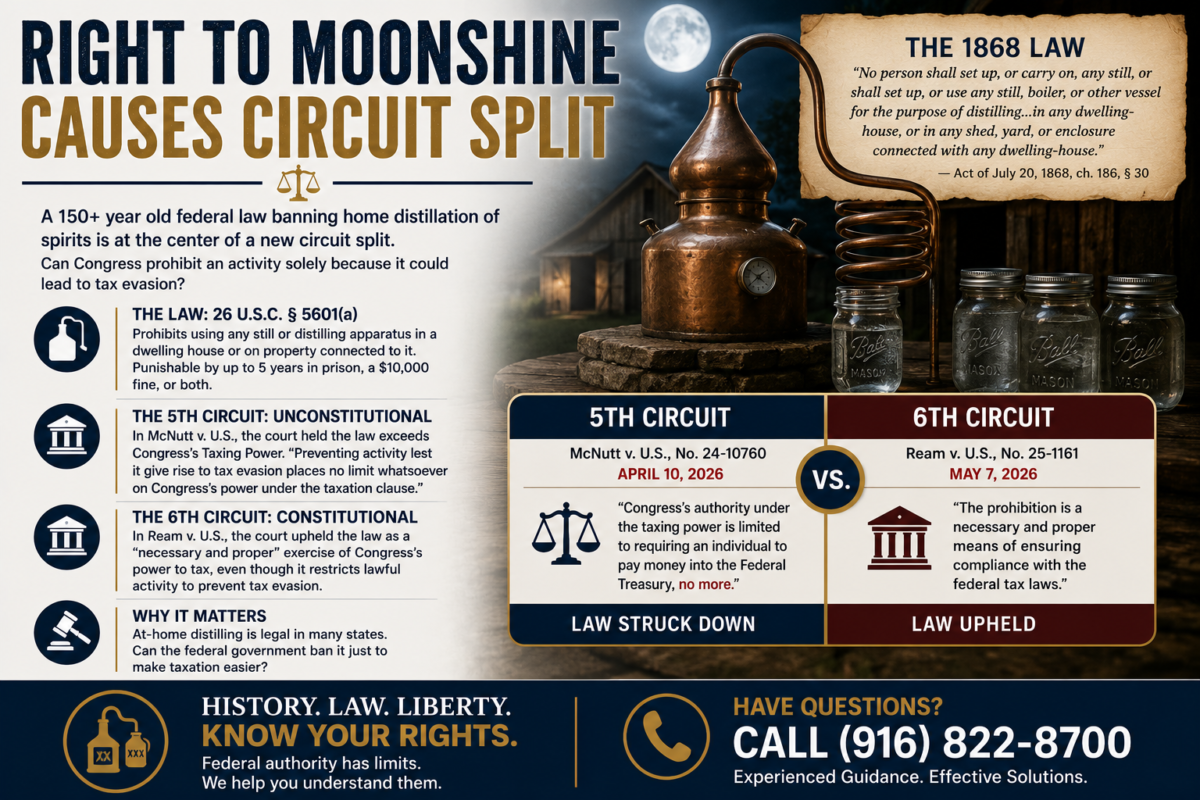
In 1868, Congress passed a law taxing tobacco and distilled spirits. The same statute “prevented a person from using ‘any still, boiler, or other vessel for purpose of distilling’ when the still was located, among other places, ‘in any dwelling-house’ or ‘in any shed, yard, or enclosure connected with any dwelling-house.’”[1] Doing so is a crime punishable by imprisonment for up to 5 years or a fine of up to $10,000, or both.[2] In April 2026, the 5th Circuit Court struck down this restriction as unconstitutional in McNutt v. U.S.,yet the 6th Circuit upheld the same law in Ream v. U.S soon thereafter.

“The government defends the statutory prohibition on at-home distillation of spirits as a ‘necessary and proper’ exercise of Congress’s power to ‘tax.’”[3] Specifically, prohibiting at-home distillation would promote the tax since it would be relatively easy to evade the tax if the distillation occurred at home. The 5th Circuit disagreed. “[P]reventing activity lest it give rise to tax evasion places no limit whatsoever on Congress’s power under the taxation clause.”[4] Quoting the Supreme Court, “Congress’s authority under the taxing power is limited to requiring an individual to pay money into the Federal Treasury, no more.”[5] Here, the challenged law prevents revenue by preventing the revenue-generating activity. The 6th Circuit agreed that the Taxing Clause is limited to taxing in a much briefer analysis.

For reasons unknown, the government abandoned its Commerce Clause on appeal in McNutt v. U.S. and apparently did not cite it as justification in Ream v. U.S.[6] Therefore, neither the 5th nor the 6th Circuit considered the Commerce Clause for this issue. The District Court for McNutt rejected the government’s Commerce Clause claim because “where regulating a purely local activity does not serve a broader, overarching statutory scheme, Congress cannot not [sic] reach it.”[7] The wheat restriction upheld in Wickard v. Filburn was part of an elaborate statutory scheme.[8] However, the prohibition litigated here “is not a ‘comprehensive’ regulation of commerce of the kind that allows Congressional intervention in every related local activity. This is because the Act does not directly regulate the supply and demand of alcohol, does not make Congress a production manager over each distillery to inflate prices, and is not part of a federal directive to either promote or eliminate a national marketplace for alcohol.”[9] The relative nakedness of the home distillery ban distinguishes it from the federal ban on controlled substances.

Instead of the Commerce Clause, both Ream and McNutt turned on the Necessary and Proper Clause, the “last, best hope of those who defend ultra vires congressional action.”[10] “In general,” this “gives Congress power to pass laws both ‘vertically’ to implement its own enumerated powers and ‘horizontally’ to implement the constitutionally vested powers of federal executive and judicial officers.”[11] The primary standard dates from 1819 in McCulloch v. Maryland: “Let the end be legitimate, let it be within the scope of the constitution, and all means which are appropriate, which are plainly adapted to that end, which are not prohibited, but consist with the letter and spirit of the constitution, are constitutional.”[12] Nevertheless, “even where a law is necessary, it may still be improper.”[13] “[T]o be necessary, a law must be plainly adapted to an enumerated power.”[14] Here, the law prevents the activity from being taxed rather than assisting in the taxation of the activity. This is similar to a law struck down as unconstitutional in U.S. v. Dewitt, a 1869 Supreme Court case. “There, the challenged statute prohibited the sale of naphtha mixed with illuminating oils. The government attempted unsuccessfully to defend the statute’s constitutionality under the Commerce Clause and taxing power.”[15] The Supreme Court found that it was too attenuated from the taxation to be considered “necessary.”

A law is “proper” under the Necessary and Proper Clause “when it is not prohibited by another enumerated powers [sic] and is consistent with the letter and spirit of the constitution.”[16] Such consistency is absent here, according to the 5th Circuit. Ruling otherwise risks “creating a general federal authority akin to the police power.”[17] Ultimately, the law’s legal defense was a non-sequitur. “Logically, the Necessary and Proper Clause cannot expand the reach of the taxing power to criminalize conduct that could produce taxable revenue under the pretext that generating revenue for the federal government will be enhanced.”[18] Nevertheless, the injunction is limited to the plaintiffs.

The 6th Circuit created a circuit split through Ream v. U.S. The majority of the panel upheld the law as constitutional, while one judge dissented, arguing that the plaintiff lacked standing. The dissenting opinion cited the 5th Circuit’s McNutt v. U.S. to contrast the standing in that case with Ream. However, the majority did not mention McNutt. Ream had a different perspective on the challenged law’s logic. “Even now its rationale is almost self-evident: stills are more easily hidden in homes than in bonded premises dedicated to distilling spirits.”[19] Ream also countered the argument that the law reduces revenue rather than increases it. “As a matter of direct causation, that might be so; but Congress can take account of causal chains longer than that.”[20] Specifically, “Congress had ample reason to conclude that, for every at-home distiller who pays the tax, many others would not. The ban thus shifts consumption from untaxed spirits to taxed spirits—thereby increasing revenue.”[21] Consequently, the law is “necessary” under the Necessary and Proper Clause. As for propriety and concerns of general police power implications, the Necessary and Proper Clause’s application cannot be abstracted and reused with ease. “[W]hether a law is ‘plainly adapted’ to a permissible end depends on an empirical judgment—which is to say the judgment is, by nature, factbound.”[22] There were more than enough pertinent facts here, the court held. “Here, those facts include a history of tax evasion as old as the Republic itself; and Congress concluded—based on that history, and after a month of testimony before a select committee of the House—that the home-distilling ban, along with the 1868 Act’s other provisions, were in fact necessary to collect federal excise taxes on spirits.”[23] Collecting excise taxes on alcohol is a distinctive challenge, permitting flexibility. “Indeed, rules concerning alcohol more generally are unique as to the evasion that often accompanies them—from excise taxes, to Prohibition, to the use of fake IDs to obtain alcohol (itself almost a rite of passage for some generations), to moonshiners even today. The judgment required in this case, again, is an empirical one; and empirically, alcohol is sui generis, or very close to it.”[24]

It remains to be seen whether Ream or McNutt will prevail. Perhaps neither will, and the country will be split between “wet” and “dry” states regarding home distilleries. Indeed, this is the statistically likely outcome given the scarcity of Supreme Court decisions. Defenders of the Ream ruling will need to address U.S. v. Dewitt because Ream did not. Dewitt seems strikingly similar to the facts at hand. Although the 1869 case seemed most concerned with the federal regulation of intrastate commerce, a subject that has since become more nuanced, it also ruled that the Necessary and Proper Clause was insufficient. However, Dewitt does not necessarily support McNutt as McNutt claimed. In Dewitt, the prohibition was on a specific type of oil that is not taxed, supposedly to promote other types of oil that are taxed. Dewitt explicitly distinguished it from the statutory framework for liquor taxation:

And we have been referred to provisions, supposed to be analogous, regulating the business of distilling liquors, and the mode of packing various manufactured articles; but the analogy appears to fail at the essential point, for the regulations referred to are restricted to the very articles which are the subject of taxation, and are plainly adapted to secure the collection of the tax imposed; while, in the case before us, no tax is imposed on the oils the sale of which is prohibited.[25]McNutt nevertheless relied on this discussion to hold that an important restriction on the business of distilling liquors is unconstitutional.


[1] McNutt v. United States DOJ, No. 24-10760, 2026 U.S. App. LEXIS 10423, at *5 (5th Cir. Apr. 10, 2026).

[2] The district court in McNutt noted: “As a matter of principle, this Court is distressed at an impropriety contained in TTB’s letter. Regardless of the reader’s level of comfort with the federal government receiving purchase data and using that data to ‘forewarn’ ne’er-do-well citizens about potential criminal liability, this Court is highly disturbed that the letter attempts to threaten a ‘$500,000 fine’ when the statutory maximum is $10,000. See 26 U.S.C. § 5601(a).” Hobby Distillers Ass’n v. Alcohol & Tobacco Tax & Trade Bureau, 740 F. Supp. 3d 509, 520 n.1 (N.D. Tex. 2024).

[3] McNutt v. United States DOJ, No. 24-10760, 2026 U.S. App. LEXIS 10423, at *12 (5th Cir. Apr. 10, 2026).

[4] Id. at *16-17.

[5] Id. at *14(quoting with emphasis added, Nat’l Fed’n of Indep. Bus. v. Sebelius, 567 U.S. 519, 574 (2012)).

[6] The plaintiff argued in the District Court that the Dormant Commerce Clause (a limitation on state law) somehow renders the law unconstitutional. Ream v. United States Dep’t of the Treasury, 771 F. Supp. 3d 998, 1007 (S.D. Ohio 2025).

[7] Hobby Distillers Ass’n v. Alcohol & Tobacco Tax & Trade Bureau, 740 F. Supp. 3d 509, 531 (N.D. Tex. 2024).

[8] Wickard v. Filburn, 317 U.S. 111 (1942).

[9] Hobby Distillers Ass’n v. Alcohol & Tobacco Tax & Trade Bureau, 740 F. Supp. 3d 509, 533 (N.D. Tex. 2024).

[10] McNutt v. United States DOJ, No. 24-10760, 2026 U.S. App. LEXIS 10423, at *17 (5th Cir. Apr. 10, 2026)(quoting Printz v. United States, 521 U.S. 898, 923, 117 S. Ct. 2365, 2378 (1997)).

[11] Id. at *17-18.

[12] Id. at *18(quoting McCulloch v. Maryland, 17 U.S. (4 Wheat.) 316, 421 (1819)).

[13] Id.(omitting internal quotation marks).

[14] Id.(omitting internal quotation marks).

[15] Id. at *22-23(omitting internal citation).

[16] Id. at *26(omitting internal brackets and quotation marks).

[17] Id. at *27 (5th Cir. Apr. 10, 2026)(quoting Nat’l Fed’n of Indep. Bus. v. Sebelius, 567 U.S. 519, 536 (2012)). 

[18] Id.

[19] Ream v. U.S. Dep’t of the Treasury, No. 25-3259, 2026 U.S. App. LEXIS 11310, at *13 (6th Cir. Apr. 21, 2026).

[20] Id. at *15.

[21] Id.

[22] Id. at *17.

[23] Id.

[24] Id. at *17-18.

[25] United States v. Dewitt, 76 U.S. (9 Wall.) 41, 44 (1869).

Categories
News

Tax Court Limits Extra-Statutory Limitations

Simens Medical Solutions USA Inc. v. Commissioner is simultaneously broad and narrow in scope. The Tax Court’s judgment addresses a specific and unusual situation. However, its methodology in doing so is applicable to innumerable circumstances.

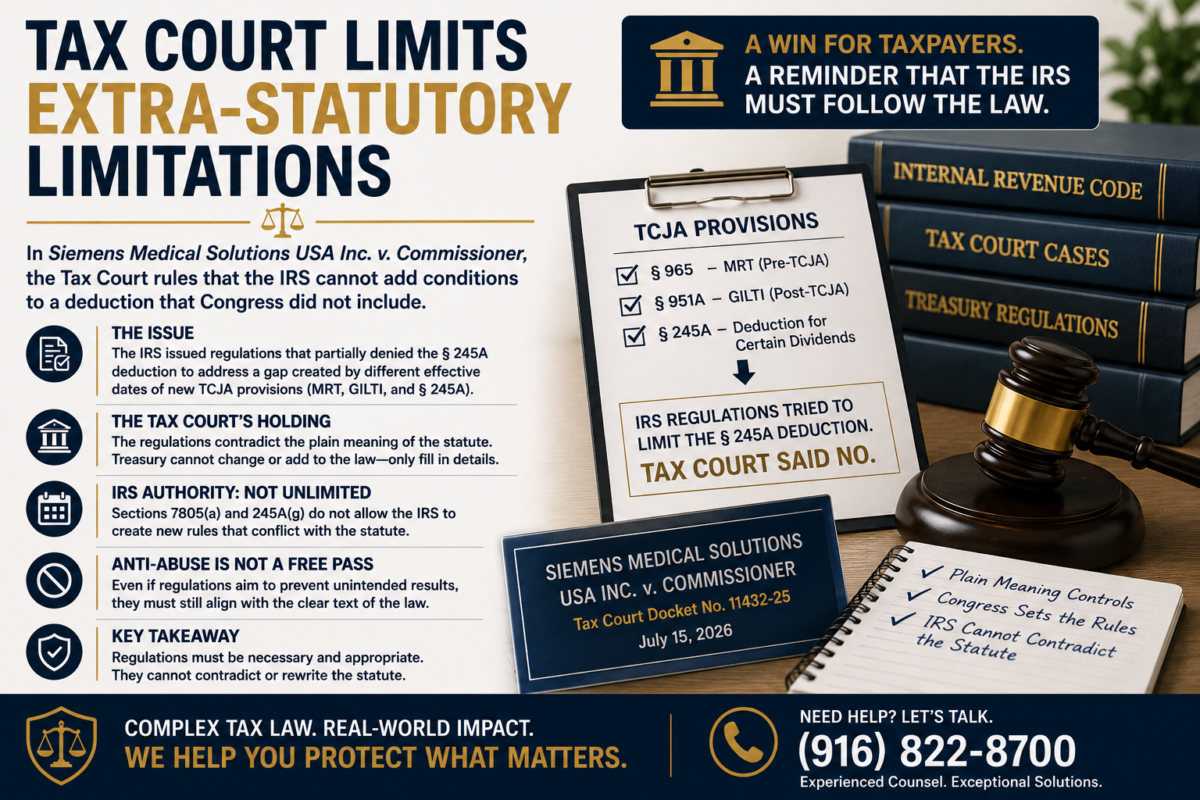
The Tax Cuts and Jobs Act of 2017 (TCJA) introduced many changes into the international aspects of the Internal Revenue Code. “[I]n general terms, section 965 (MRT) taxes foreign earnings accumulated before the TCJA was enacted while section 951A (GILTI) taxes post-TCJA foreign earnings. Section 245A allows a deduction for certain post-TCJA dividends from foreign corporations, effectively exempting such dividends from U.S. tax.”[1] However, “the section 245A deduction should apply only to the type of earnings that are not subject to subpart F, the GILTI, and the MRT.”[2] Each of these three new components (MRT, GILTI, and § 245A) has different effective dates. This leaves a gap whereby “the foreign income of a CFC may not be subject to any tax and yet still be eligible for the section 245A deduction.”[3] The IRS promulgated regulations to fill that gap by partially denying the § 245A deduction. Effectively, the regulations only regard the 2018 taxable year in rather specific scenarios. Yet, the question of whether the IRS could create such regulations affects nearly everyone.

In Simens Medical Solutions USA Inc., the taxpayer met all conditions set in § 245A for its deduction. That was enough for the Tax Court. In Varian Medical System v. Commissioner, the Tax Court rejected the IRS’s attempt to change the effective date of another section amended by the TCJA that was originally advantageous because it was mismatched with § 245A.[4] There, the IRS attempted to directly change the effective date rather than impose additional conditions. Here, the regulations “do not specifically change an effective date, but Treasury specifically drafted the Extraordinary Disposition Rules to address a gap created solely by different effective dates.”[5] At least in this instance, the IRS is barred by a congressional delegation version of the substance over form doctrine. “Thus, while the mechanism for addressing the perceived problem is different, the effect is materially the same.”[6]

The IRS claimed that sections 7805(a) and 245A(g) authorize the regulations in question. Section 7805(a) is the general delegation, providing that the IRS “shall prescribe all needful rules and regulations for the enforcement” of the Internal Revenue Code.[7] The more specific § 245A(g) provides that: “The Secretary shall prescribe such regulations or other guidance as may be necessary or appropriate to carry out the provisions of this section, including regulations for the treatment of United States shareholders owning stock of a specified 10 percent owned foreign corporation through a partnership.” The Tax Court explained that “appropriate is a quintessentially context dependent term that often draws its meaning from surrounding provisions.”[8] Yet “the statute contains no hint” of the regulations here.[9] “Treasury is not trying to construe the language of section 245A. Instead, Treasury is trying to correct the mismatch in effective dates by changing the plain meaning of the statute.”[10] The IRS may be able to “fill[] up the details of a statutory scheme.”[11] Nevertheless, “[a]dding entirely new rules at odds with the statute goes beyond filling in the gaps.”[12] The anti-abuse nature of these regulations is irrelevant. “[S]elf-serving regulations never justify departing from the statute’s clear text.”[13] Ultimately, “a regulation that purports to contradict the statute can be neither necessary nor appropriate.”[14]

The Treasury Regulations are filled with provisions not found in the Internal Revenue Code. The line between filling in the gaps left by the Code and rewriting it may be vague at times. However, if the regulations’ substance is not even “hinted” at by the statutes, they may exceed the IRS’s authority.


[1] Siemens Med. Sols. USA, Inc. v. Commissioner, No. 11432-25, 2026 U.S. Tax Ct. LEXIS 1531, at *10 (T.C. July 15, 2026).

[2] Id. at *13.

[3] Id. at *14.

[4] Varian Med. Sys. v. Commissioner, 163 T.C. 76 (2024).

[5] Siemens Med. Sols. USA, Inc. v. Commissioner, No. 11432-25, 2026 U.S. Tax Ct. LEXIS 1531, at *20 (T.C. July 15, 2026).

[6] Id.

[7] Id. at *22.

[8] Id. at *23(omitting internal quotation marks and brackets).

[9] Id. at *24.

[10] Id.

[11] Id. at *26.

[12] Id.

[13] Id. at *25(omitting internal quotation marks).

[14] Id. at *24.

Categories
News

When a Sole Proprietorship is Not a Unitary Business

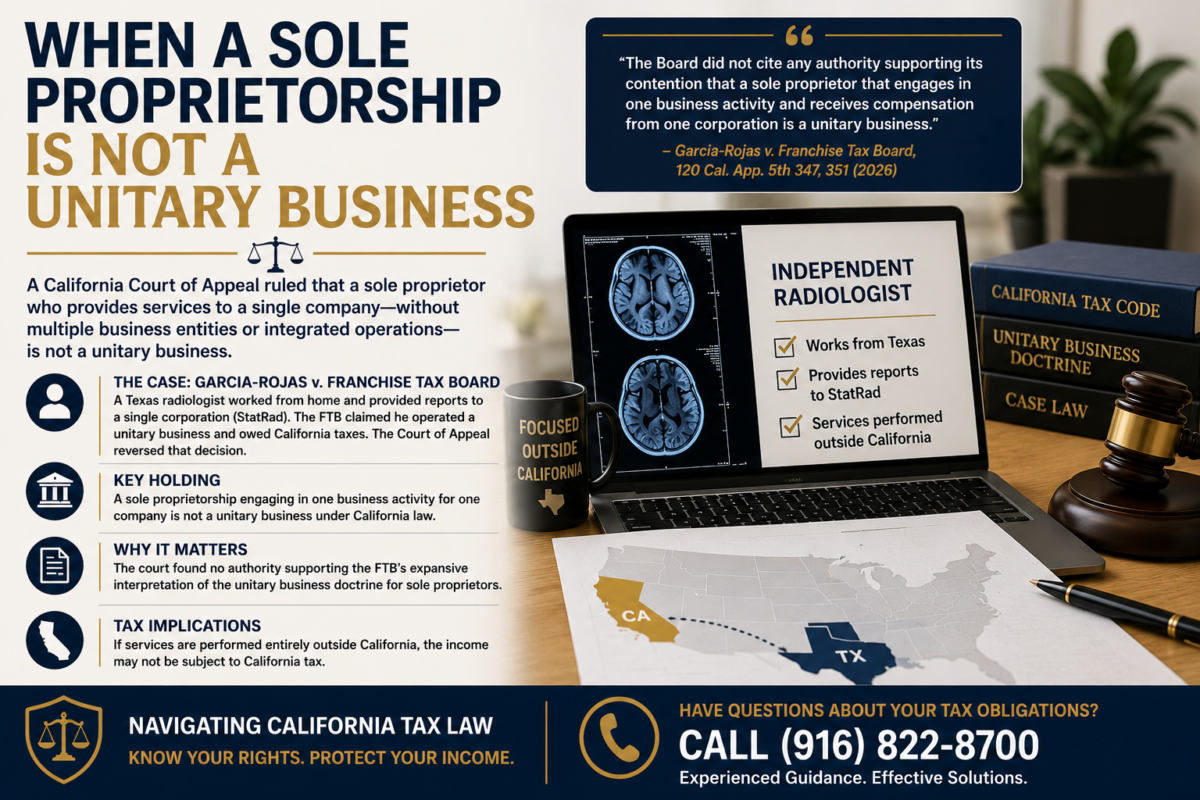
Dr. Xavier Garcia-Rojas worked as an independent contractor for Stat Radiology Medical Corporation (StadRad) as a radiologist. StatRad provided the radiologist with equipment, which he used from his Texas home to submit reports. Some of the images he studied were from medical facilities in California. The FTB demanded a California tax return in July 2019. “He filed returns for 2018, 2019, and 2020, paid the amounts requested by the Board, and then requested a refund. The Board never responded,” over six years later.[1] Dr. Garcia-Rojas sued in May 2023, and the trial court sided with the FTB’s theory that Dr. Garcia-Rojas operated a unitary business as a sole proprietorship. The Court of Appeal reversed. “[T]he Board did not cite any authority supporting its contention that a sole proprietor that engages in one business activity and receives compensation from one corporation—even when that corporation’s clients are found both in and outside of California—is a unitary business.”[2] There simply has not been a case “apply[ing] the unitary business theory to a single person or sole proprietorship engaging in one business activity.”[3] The Court of Appeal did not start here in Garcia-Rojas v. Franchise Tax Board.

“Unitary business has a long recognized meaning in California—two or more business entities that are commonly owned and integrated in a way that transfers value among the affiliated entities.”[4] Here, the sole proprietorship is solitary and therefore cannot be a unitary business. The court disapproved of Appeal of Bindley, an Office of Tax Appeals (OTA) case.[5] In Bindley a screenplay writer residing in Arizona worked as an independent contractor for two California LLCs, performing all work in Arizona. The OTA held that this was a unitary business, which applies in equal force to sole proprietorships. In considering Appeal of Bindley, the Court of Appeal found that the OTA “ignored that there must be separate business activities to unite.”[6] The Court of Appeal did not mention that the self-employed taxpayer in Bindley worked for two companies.

The Board of Equalization held in 1982 that the taxpayer “bears the burden of proof, i.e., [the taxpayer] must establish by a preponderance of the evidence that the unitary connections present in the case are, in the aggregate, so trivial and insubstantial as to require a holding that a single unitary business did not exist.”[7] This is embedded in the FTB audit manual regarding the unitary business doctrine (at p. 22). Garcia-Rojas did not discuss this burden. Instead, it assumed that the FTB must prove its unitary business theory rather than forcing the taxpayer to disprove it.[8]

Tax treatment of nonresident taxpayers begins with the general rule that “in the case of nonresident taxpayers the gross income includes only the gross income from sources within this state.”[9] But the details are delegated to the FTB. Namely, such income “shall be allocated and apportioned under rules and regulations prescribed by the Franchise Tax Board.”[10] Section 17951-4 functions as a railroad track switch, directing circumstances to more specific statutes or regulations. Situations that are not directed to the Uniform Division of Income for Tax Purposes Act (RTC § 25120 et seq.) are implicitly left behind to be dealt with through the regulations for §§ 17951-17953. These tend to be more favorable to the taxpayer and are more influenced by physical presence. As applicable here, it appears that Dr. Garcia-Rojas would not be taxed by California at all because all of his services were performed outside of California.[11]

The full implications of Garcia-Rojas remain to be seen. Unfortunately, the court disclaimed in its 6-page opinion that “[w]e express no opinion as to whether the Board can tax Garcia-Rojas under a different legal theory.”[12] Nevertheless, the subsequent petition for review filed by the California Justice Department on behalf of the FTB gave some indication of potential changes: “The result could be that the Board would have to instead apply ‘separate’ accounting methods to determine taxable income for all such entities, throwing into question how to account for shared overhead expenses and making it harder to ensure that such taxpayers file tax returns and remit taxes to California.”[13] The filing did not elaborate. However, it appears that the FTB would require businesses within Garcia-Rojas’s scope to track the origin of each dollar they receive if they do not apportion their income.

Garcia-Rojas may be an exercise in Orwellian doublethink, but it simply takes the FTB legal landscape to its logical conclusion. The unitary business doctrine requires multiple businesses or business activities. A simple business performing a sole trade without subsidiary entities cannot be “unitary.” Although Garcia-Rojas regarded sole proprietorships, its reasoning is equally applicable to all entity types. If curious whether Garcia-Rojas can be used to save you from being taxed by California, please contact us at (916) 822-8700.


[1] Garcia-Rojas v. Franchise Tax Bd., 120 Cal. App. 5th 347, 349 (2026). The refund claims for 2018 and 2019 were filed on April 17, 2020.

[2] Garcia-Rojas v. Franchise Tax Bd., 120 Cal. App. 5th 347, 351 (2026).

[3] Garcia-Rojas v. Franchise Tax Bd., 120 Cal. App. 5th 347, 351 (2026).

[4] Garcia-Rojas v. Franchise Tax Bd., 120 Cal. App. 5th 347, 351 (2026)(omitting internal quotation marks).

[5] Appeal of Bindley, 2019 – OTA – 179P.

[6] Garcia-Rojas v. Franchise Tax Bd., 120 Cal. App. 5th 347, 352 (2026).

[7] Appeal of Saga Corporation, 82-SBE-102, June 29, 1982.

[8] However, the court commented that “[t]he party moving for summary judgment bears the burden of persuasion that there is no triable issue of material fact and that he is entitled to judgment as a matter of law,” and the matter before the court was a motion for summary judgment. Garcia-Rojas v. Franchise Tax Bd., 120 Cal. App. 5th 347, 350 (2026)(omitting internal quotation marks). Yet, the dispute here was what the material facts meant for the case, rather than the material facts themselves.

[9] RTC § 17951(a).

[10] RTC § 17954.

[11] “Nonresident attorneys, physicians, accountants, engineers, etc., even though not regularly engaged in carrying on their professions in this State, must include in gross income as income from sources within this State the entire amount of fees or compensation for services performed in this State on behalf of their clients.” 18 CCR § 17951-5(a)(3).

[12] Garcia-Rojas v. Franchise Tax Bd., 120 Cal. App. 5th 347, 349 (2026).

[13] FTB Petition for Review at p. 16 (Not freely available online, but available on request).

Categories
News

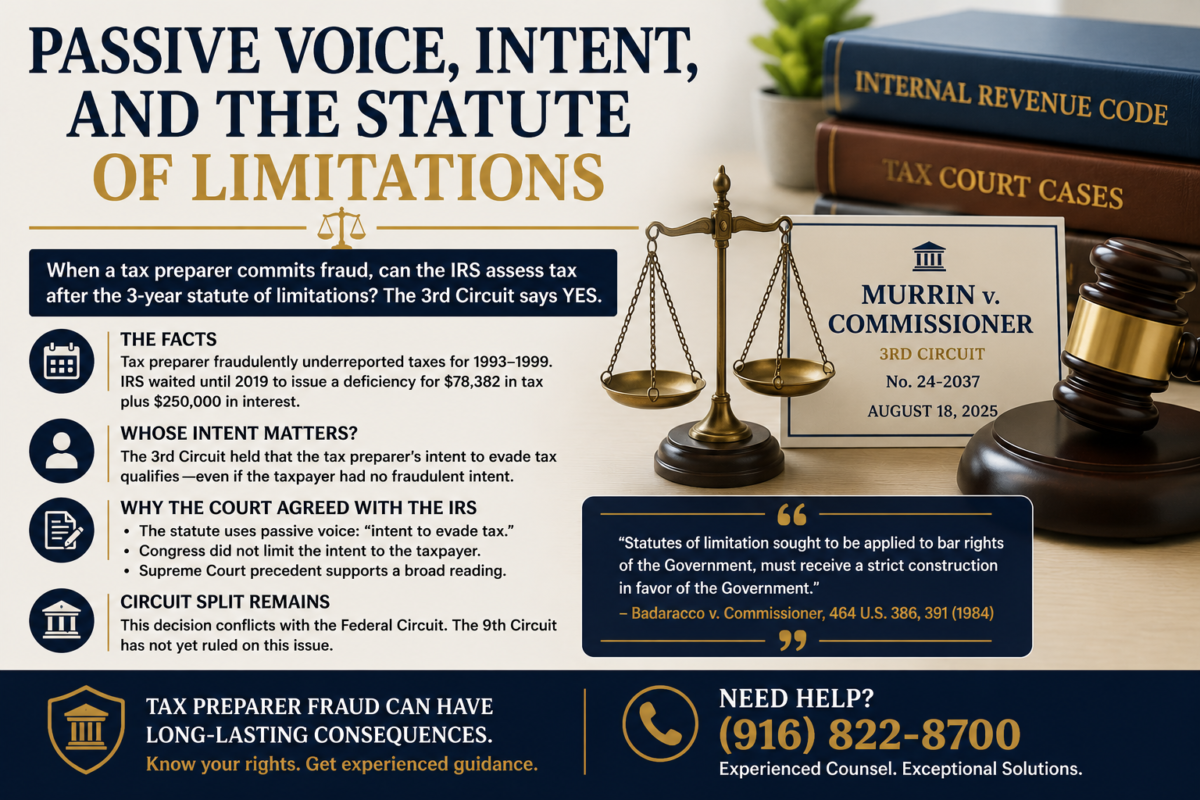
Passive Voice, Intent, and the Statute of Limitations

As with many facets of tax law, the question of the statute of limitations has a relatively straightforward answer that generally applies with a dozen exceptions. Fraud is one of the 12 exceptions to the 3-year rule. Specifically: “In the case of a false or fraudulent return with the intent to evade tax, the tax may be assessed, or a proceeding in court for collection of such tax may be begun without assessment, at any time.”[1] Whose intent?

            When Ms. Murrin received a notice of deficiency for tax years 1993-1999 in 2019, the decades of delay were justified because their tax preparer committed fraud for these tax years, according to the IRS. For reasons unknown, the parties stipulated that the tax preparer did indeed commit fraud, resulting in underpayment of taxes and associated accuracy penalties. The total amount was $78,382, but interest added another $250,000.

The Third Circuit in Murrin v. Commissioner upheld the Tax Court’s ruling that the tax preparer’s intent qualifies for these purposes. “First, the plain and ordinary meaning of the phrase ‘intent to evade tax’ reveals no taxpayer-only limitation.”[2] Although the tax liability is specific to a person, that specificity is not necessarily transmuted to the intent. The taxpayers are further defeated by the grammatical passive voice. This indicates that “Congress drafted § 6501(c)(1) by focusing on an event that occurs without respect to a specific actor, and therefore without respect to any specific actor’s intent or culpability.”[3] Murrin was particularly influenced by Bartenwerfer v. Buckley,where the Supreme Court explained in the context of bankruptcy law that “[p]assive voice pulls the actor off the stage.”[4] However, the 3rd Circuit refused to “determine the outer bounds of how an ‘intent to evade tax’ applies in every context.”[5]

The taxpayer argued that the most natural reading assigns the intent to the taxpayer whose tax is being evaded and whose return is false. This “argument is a fair one,” the 3rd Circuit conceded. “But the plainest and most straightforward reading of § 6501(c)(1) is that it simply requires an ‘intent to evade tax’ attached to a ‘false or fraudulent return,’ and whether a taxpayer, accountant, lawyer, or tax preparer evinced such intent is beside the point.”[6] The court did not explain why its reading is plainer than the taxpayer’s interpretation. However, the court bolstered its argument by observing that “Congress expressly used the term ‘taxpayer’ in § 6501(a) to define what return is at issue but declined to use the same qualifier in § 6501(c)(1).”[7] The difference in language yields a difference in meaning. The taxpayer’s appeals to other statutory provisions that create individualized responsibility backfired because they only served to prove that Congress is capable of limiting its language to the taxpayer. Contrary to another argument, “our interpretation of § 6501(c)(1) renders nothing superfluous in this statute.”[8]

            Together with the Supreme Court’s command that statutes of limitations must be strictly construed in favor of the IRS, the 3rd Circuit easily found in favor of the IRS despite expressions of sympathy for the taxpayer.[9] Nevertheless, the 3rd Circuit recognized that it created a circuit split with the Federal Circuit, noting that the Federal Circuit’s decision came before the Supreme Court’s grammar lesson in Bartenwerfer. As the 3rd Circuit implied, BASR Partnership v. United States did not discuss the passive voice.[10] However, the 3rd Circuit did not point out that BASR Partnership is weakened by three opinions in a three-judge panel. As the Tax Court explained when it considered Murrin v. Commissioner:

Laying out the scorecard: (1) the author of the majority opinion concluded that section 6501(c)(1) ‘suspends the three-year limitations period only when the IRS establishes that the taxpayer acted with the intent to evade tax,’ (2) the author of the concurring opinion reasoned that “it is the taxpayer (or possibly his authorized agent) who must have the requisite ‘intent to evade tax,’ and (3) the author of the dissenting opinion agreed with our holding in Allen.[11]

In any event, the IRS agreed with both sides in its history. In January 2001, it issued FSA 200104006, which limited the intent to that of the taxpayer. Like the taxpayer in Murrin,the IRS argued that the emphasis on fraud connotes the personal responsibility of the taxpayer. The IRS published FSA 200126019 six months later, completely changing its position. This becomes even more curious because both field service advisories were in response to the same fact pattern and were written by the same individual.

The Supreme Court rejected the taxpayer’s appeal of Murrin’s ruling, leaving the circuit split intact. However, the 9th Circuit has yet to opine in this matter, so Murrin is not necessarily binding on Californians. If you suffered from your tax preparer’s fraud, please contact (916) 822-8700 for assistance.


[1] § 6501(c)(1)(emphasis added).

[2] Murrin v. Commissioner, No. 24-2037, 2025 U.S. App. LEXIS 20972, at *5 (3d Cir. Aug. 18, 2025).

[3] Id. at *6(omitting internal quotation mark and brackets).

[4] Bartenwerfer v. Buckley, 598 U.S. 69, 75 (2023).

[5] Murrin v. Commissioner, No. 24-2037, 2025 U.S. App. LEXIS 20972, at *9 n.7 (3d Cir. Aug. 18, 2025).

[6] Id. at *7.

[7] Id. at *8.

[8] Id. at *8-9 (3d Cir. Aug. 18, 2025). The superfluous argument was not well explained, and the court stated that it did not understand it.

[9] “This Court long ago pronounced the standard: ‘Statutes of limitation sought to be applied to bar rights of the Government, must receive a strict construction in favor of the Government.’” Badaracco v. Commissioner, 464 U.S. 386, 391, 104 S. Ct. 756, 761 (1984).

[10] Basr P’ship v. United States, 795 F.3d 1338, 1356 (Fed. Cir. 2015).

[11] Murrin v. Commissioner (T.C. Memo. 2024-10)(omitting internal citations).