
Introduction
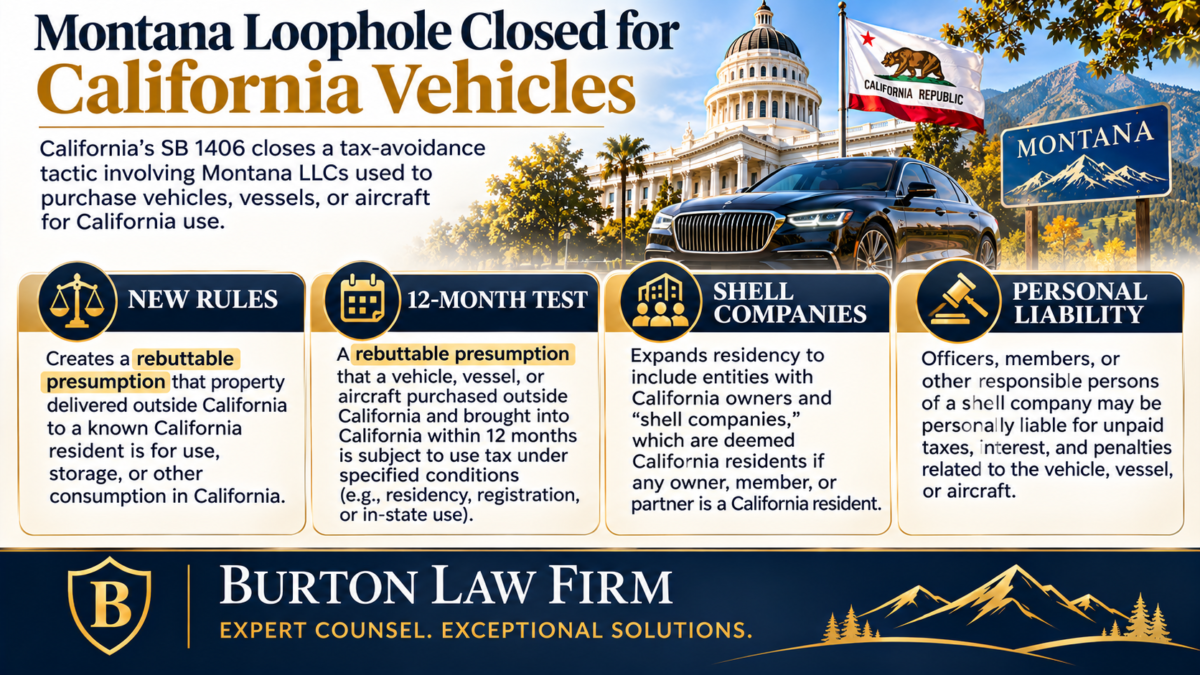
California closed the so-called “Montana Loophole,” whereby “some Californians form a ‘shell company’ domiciled in Montana (Montana LLC) and buy the vehicle in the Montana LLC’s name. Subsequently, they take delivery outside the state and register the vehicle in Montana, where no sales or use tax applies, and return the vehicle to California for use or storage within 12 months,” according to an Assembly analysis. To combat this tactic, SB 1406 created two rebuttable presumptions effective immediately.[1]
First Presumption
The first presumption states that “it shall be presumed that tangible personal property delivered outside this state to a purchaser known by the retailer to be a resident of this state, as defined in Section 6248, was purchased from a retailer for storage, use, or other consumption in this state and stored, used, or otherwise consumed in this state.”[2] This may be rebutted in two ways. One is to provide “a written statement, signed by the purchaser or their authorized representative, and retained by the vendor, that the property was purchased for use at a designated point or points outside this state.”[3] The language does not require the statement to be under penalty of perjury. The other method is through “other evidence satisfactory to the California Department of Tax and Fee Administration that the property was not purchased for storage, use, or other consumption in this state.”[4]
Second Presumption
The second presumption provides: “There shall be a rebuttable presumption that any vehicle, vessel, or aircraft bought outside of this state on or after the effective date of this section, and which is brought into California within 12 months from the date of its purchase, was acquired for storage, use, or other consumption in this state and is subject to use tax if any of the following occurs:”[5]
- “The vehicle, vessel, or aircraft was purchased by a resident of California.”[6]
- “In the case of a vehicle,” the vehicle needed to be registered in California “during the first 12 months of ownership.”[7]
- “In the case of a vessel or aircraft, that vessel or aircraft was subject to property tax in this state during the first 12 months of ownership.”[8]
- “If purchased by a nonresident of California, the vehicle, vessel, or aircraft is used or stored in this state more than one-half of the time during the first 12 months of ownership.”[9]“
“This presumption may be controverted by documentary evidence that the vehicle, vessel, or aircraft was purchased for use outside of this state during the first 12 months of ownership.”[10] Such evidence nonexclusively includes “evidence of registration of that vehicle, vessel, or aircraft, with the proper authority outside of this state.”[11] In addition, the presumption may be rebutted through “documentary evidence that the vehicle was brought into this state for the exclusive purpose of warranty or repair service and was used or stored in this state for that purpose for 30 days or less,” if such evidence “include[s] a work order stating the dates that the vehicle is in the possession of the warranty or repair facility and a statement by the owner of the vehicle specifying dates of travel to and from the warranty or repair facility.”[12] Aircraft and vessels brought into California exclusively for repairs or upgrades are exempt if the repair facility is appropriately licensed.[13] Finally, this presumption “shall not apply to any vehicle, vessel, or aircraft used in interstate or foreign commerce pursuant to regulations prescribed by the department.”[14]
Expanded Residency
The Vehicle Code defines a “resident” as “any person who manifests an intent to live or be located in this state on more than a temporary or transient basis. Presence in the state for six months or more in any 12‐month period gives rise to a rebuttable presumption of residency.”[15] This definition is expanded for the two presumptions in two ways. The first deems any entity to be a California resident if at least half of its equity is owned by residents.[16] The second provides that “a shell company shall be deemed to be a California resident if any shareholder, partner, member, or beneficial owner is a resident of California.”[17] In turn, a “shell company” is defined as “a closely held corporation, partnership, limited partnership, limited liability partnership, or limited liability company used for the purpose of evading the payment of taxes due under this part.”[18] This nonexclusively considers the following as evidence:
- The entity “lacks a specific business activity or purpose.”[19]
- “It fails to maintain a physical location outside California.”[20]
- “It fails to employ individual persons and provide those persons with Internal Revenue Service Form W-2 wage and tax statements.”[21]
- “It fails to file federal tax returns or fails to file a required state tax return in a state other than California.”[22]
The definition of a shell company is further relevant because this new law makes “[a]ny officer, manager, partner, beneficial owner, or member of a shell company” become “personally liable for any unpaid taxes, and any interest and penalties on those taxes” arising from “purchase of a vehicle, vessel, or aircraft” which was “stored, used, or otherwise consumed” within California by the shell company “within 12 months from the date of purchase and failed to pay the tax to the seller or to remit the tax to the department or the Department of Motor Vehicles.”[23]
[1] However, “[t]he amendments made to this section by the act adding this subdivision shall not apply to any vehicle, vessel, or aircraft that is either purchased, or is the subject of a binding purchase contract that is entered into, on or before the operative date of this subdivision.” RTC § 6248(d).
[2] RTC § 6247(a).
[3] RTC § 6247(b).
[4] RTC § 6247(b).
[5] RTC § 6248(a).
[6] RTC § 6248(a)(1).
[7] RTC § 6248(a)(2).
[8] RTC § 6248(a)(3).
[9] RTC § 6248(a)(4).
[10] RTC § 6248(b).
[11] Id.
[12] RTC § 6248(f).
[13] RTC § 6248(e).
[14] RTC § 6248(c).
[15] Veh. Code § 516.
[16] RTC § 6248(a)(1)(A).
[17] RTC § 6248(a)(1)(B).
[18] RTC § 6248(a)(1)(C).
[19] RTC § 6248(a)(1)(C)(i).
[20] RTC § 6248(a)(1)(C)(ii).
[21] RTC § 6248(a)(1)(C)(iii).
[22] RTC § 6248(a)(1)(C)(iv).
[23] RTC §§ 6249.5(a) & (b).