Expert Counsel. Exceptional Solutions.

+1 (916) 822-8700

Inspector General: IRS is Struggling with Partnership Audits

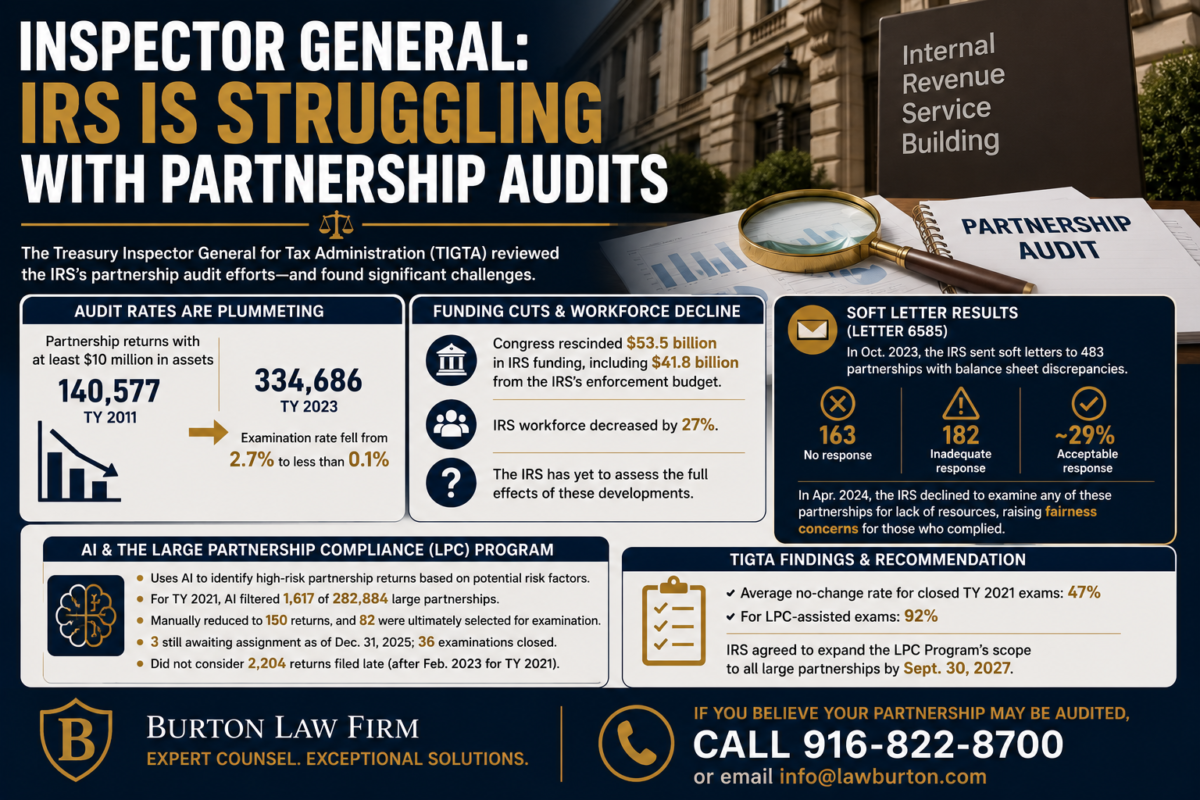
The IRS received 140,577 returns for Tax Year (TY) 2011 for partnerships with at least $10 million in assets. This increased to 334,686 returns for TY 2023. Meanwhile, the examination rate for these partnerships fell from 2.7% to less than 0.1%. The IRS previously set the target audit rate for TY 2026 at 1%. However, that ambition was premised on the $79.4 billion the IRS received through the Inflation Reduction Act. Instead, Congress rescinded $53.5 billion in funding, including $41.8 billion from the IRS’s enforcement budget. Furthermore, the IRS’s workforce decreased by 27%. The IRS has yet to assess the effects of these developments. The Treasury Inspector General for Tax Administration (TIGTA) reviewed the situation.

In October 2023, the IRS issued a letter to 483 large partnerships with balance sheet discrepancies (the assets did not equal equity plus liabilities). This letter was Letter 6585, Soft Letter Pass-Through Entity Campaign. “A soft letter is not an examination activity but can be a way to alert taxpayers of potential noncompliance.” Of these 483 letters asking for documentation, 163 simply lacked a response, and 182 had an inadequate response. Only about 29% had responses acceptable to the IRS. In April 2024, the IRS declined to examine any of these partnerships for lack of resources. TIGTA sympathized with the partnerships that complied. “We believe the decision not to conduct examinations on partnerships that did not respond or whose responses were rejected presents a fairness issue and a burden for partnerships who potentially spent time and money responding to the letter.” The IRS explained that less than 12 months remained before the statute of limitations expired. TIGTA countered that it was the IRS’s own fault for delaying.

The TIGTA report contained precious information regarding IRS examination practices. The IRS generally initiates examinations only when there are more than 12 months left before the statute of limitations period bars action. The Large Business and International (LB&I) Division is tasked with administering partnership tax returns. In 2018, the LB&I Division launched the Partnership Model Project, which classifies partnership returns as high, medium, or low risk through a weighted algorithm of “potential risk factors.” “High-risk returns are sent to examiners. Beginning in 2021, the LB&I Division has used AI for this process through the Large Partnership Compliance (LPC) Program. This AI is trained through the manual identification of “high-risk domestic and international business transactions that affect income, gains, expenses, or losses in the largest partnerships.”  For TY 2021, the LPC Program filtered 1,617 out of 282,884 large partnerships for potential examination. This was manually reduced to 150 “returns spread across a distribution of industry categories within the large partnership population.” In turn, 82 were ultimately selected for examination. Of these, 3 still awaited assignment to an examiner as of December 31, 2025, but the LB&I Division closed examination on 36 other partnerships by that time. Interestingly, the LPC Program did not consider 2,204 large partnership returns simply because they were filed too late (after February 2023 for TY 2021). The AI risk assessment was only conducted once. Relatively few of the TY 2021 examinations were attributable to the LPC Program. The IRS agreed to TIGTA’s recommendation to expand the LPC Program’s scope to all large partnerships by September 30, 2027. This may be beneficial for large partnerships. The average no-change rate for closed examinations TY 2021 returns was 47%, yet it was 92% for the closed examinations selected with the assistance of the LPC Program.

If you believe your partnership may be audited, please call 916-822-8700 or email info@lawburton.com.
Categories
News

The 2026 Billionaire Tax Act Part Two: Rate, Reporting, and Payment

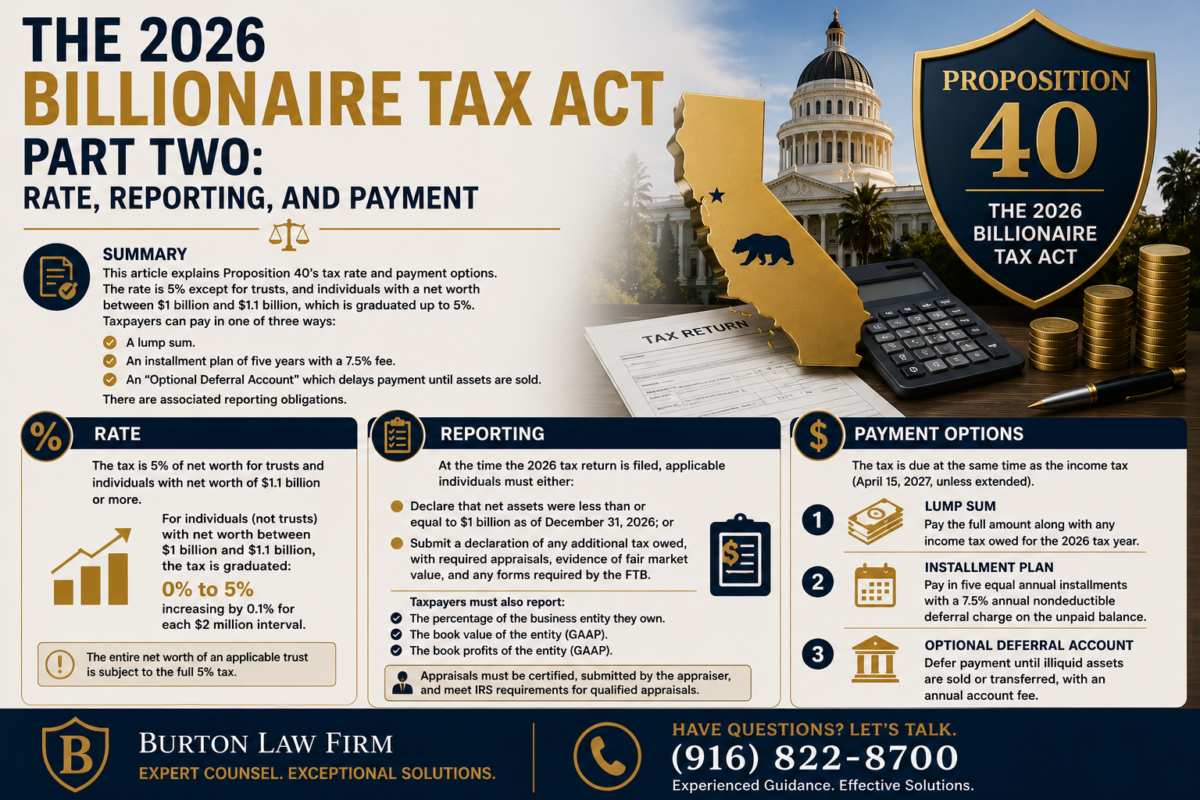
Welcome to part two of this series on Proposition 40, “The 2026 Billionaire Tax Act.”[1] This article discusses the tax rate and how taxpayers can pay the amount due under Proposition 40. The rate is 5% except for trusts, individuals with a net worth below $1.1 billion (but above $1 billion), which is graduated to 5%. There are three ways to pay:

  1. A lump sum.
  2. An installment plan of five years with a 7.5% fee.
  3. An “Optional Deferral Account” which delays payment until assets are sold.

There are associated reporting obligations. For most people, this will be a box to tick, while for others it will be a full disclosure of their net worth, together with appraisals.

Rate

“[T]he tax imposed is 5 percent of the net worth of such individual or trust,” except that “[i]n the case of an individual (other than a trust),” the tax rate would decrease by “0.1 percentage point (but not below zero) for each $2 million” below $1.1 billion in an individual’s net worth.[2] Thus, the tax rises from 0% to 5% for individual (not trust) net worths from $1 billion to $1.1 billion, increasing by 0.1% point for each $2 million interval. Moreover, the entire net worth of an applicable trust is subject to the full 5% tax even if the net worth is less than $1 billion.

Reporting

Each “California resident individual” required to file a California income tax return or an “applicable individual” would need to “[a]t the time a return is filed” for the 2026 tax year either:[3]

  • Declare that their net assets were less than or equal to $1 billion as of December 31, 2026.[4]
  • “Submit a declaration of the amount of any additional tax that is owed” under the 2026 Billionaire Tax Act, “together with any required appraisals or other evidence of fair market value,” and “any forms created by the Franchise Tax Board for calculating any additional tax owed under.”[5]

Furthermore, each “taxpayer” of the Proposition 40 tax must report all of the following:[6]

  • “The percentage of the business entity owned by the taxpayer.”[7]
  • “The book value of the business entity as of the end of the tax year, determined according to generally accepted accounting principles.”[8]
  • “The book profits of the business entity in the tax year according to generally accepted accounting principles.”[9]
    • For the purposes of this particular reporting requirement, “‘the tax year’ of the business entity means the latest tax year of the business entity ending within or with the tax year of the taxpayer.”[10]

If the taxpayer lacks information regarding such a business entity’s book value or book profits, “and also lacks the right to obtain that information, the taxpayer must submit a certified appraisal of all of the taxpayer’s interests in the business entity.”[11] A sole proprietorship’s assets would be treated and reported as the individual’s assets.[12] Any certified appraisal made for the purposes of the 2026 Billionaire Tax Act would need to be submitted to the FTB by the appraiser, along with information identifying the pertinent taxpayer.[13] The 2026 Billionaire Tax Act would borrow the requirements for a qualified appraiser and a qualified appraisal from the IRS regulations.[14]

Payment

The tax would be due at the same time as the income tax.[15] The tax may be paid in three ways:

  • A lump sum “along with any income tax owed for the 2026 tax year.”[16]
  • “[A]nnually in five equal installments commencing in the year the tax is due with each subsequent annual installment payment also being subject to an annual nondeductible deferral charge of 7.5 percent of the remaining unpaid balance.”[17]
  • An “optional deferral account” (ODA) in cases whereby Proposition 40’s tax liability would be in “excess of the combined total value of all of the individual’s publicly traded assets.”[18] In effect, an ODA functions as a sort of receivership or trust policing the relationship between the taxpayer and their illiquid assets, generally taxing 5% of distributions in addition to the income tax:
    • An ODA is a contract that “shall be legally binding on the taxpayer, and also on the taxpayer’s estate and assigns, until” the tax liability is fully paid.[19] This obliges the taxpayer to:
      • File all required forms regarding the ODA regardless of residency.[20]
        • “Failure to make annual reports and file any required forms shall be treated as a breach of contract and shall also be subject to the same penalties as a failure to file income tax forms for California residents who are required to file income tax forms.”[21]
      • “Reconcile and pay all tax liabilities that may arise as a result of the ODA.”[22]
      • Submit to California’s personal jurisdiction regarding the ODA.[23]
    • “A taxpayer may maintain only one ODA.”[24]
    • The ODA may attach to assets only to the extent that the wealth tax liability exceeds the taxpayer’s total sum of publicly traded assets.[25]
    • “[A]ny material distribution transactions made with regard to the ODA” must be annually reported.[26]
      • This generally includes any “withdrawal of money, property, or other value from” ODA assets and any “transaction with the taxpayer, or a related person to the taxpayer, that has the effect of transferring any assets or value of assets to which an ODA is attached without also transferring the ODA obligations.”[27]
      • However, this excludes “ordinary and necessary transactions for maintaining or increasing the value of assets to which an ODA is attached and that would not have the effect of distributing any profits, dividends, or other payments to owners for the use of capital, or similar transfers.”[28]
      • The FTB would be empowered and charged with the responsibility for specifying what transactions are and are not material distribution transactions.[29]
    • Material distribution transactions would be taxed at 5% (in addition to the income tax).[30]
    • An ODA could only be closed by taxing all remaining ODA assets at 5%.[31]

[1] Nothing should be construed as support of or opposition to Proposition 40 by the author or The Burton Law Firm. 

[2] Proposed RTC § 50301(b).

[3] Proposed RTC § 50301(d).

[4] Proposed RTC § 50301(d)(1)(referencing the “valuation date” which is December 31, 2026, pursuant to proposed RTC § 50308(o)).

[5] Proposed RTC § 50301(d)(2).

[6] Proposed RTC § 50303(c)(3)(A). The term “taxpayer” is undefined for these purposes. However, its plain meaning would limit its applicability to persons actually liable for taxes under Proposition 40.

[7] Proposed RTC § 50303(c)(3)(A)(i).

[8] Proposed RTC § 50303(c)(3)(A)(ii).

[9] Proposed RTC § 50303(c)(3)(A)(iii).

[10] Proposed RTC § 50303(c)(3)(A)(iii).

[11] Proposed RTC § 50303(c)(3)(B).

[12] Proposed RTC § 50303(c)(2).

[13] Proposed RTC § 50305(a). Ignorance does not necessarily seem to excuse the appraiser’s duty. It is possible that an appraiser may be required to affirmatively inquire.

[14] Proposed RTC § 50305(b).

[15] Proposed RTC § 50301(c). This would be April 15, 2027, a Thursday. However, an official disaster proclamation may delay its due date. RTC § 18572.

[16] Proposed RTC § 50301(c).

[17] Proposed RTC § 50301(c).

[18] Proposed RTC §§  50301(b) & 50304(a).

[19] Proposed RTC § 50304(b).

[20] Proposed RTC §§ 50304(a)(1) & 50304(d).

[21] Proposed RTC § 50304(d).

[22] Proposed RTC § 50304(a)(2).

[23] Proposed RTC § 50304(a)(3).

[24] Proposed RTC § 50304(c).

[25] Proposed RTC § 50304(c).

[26] Proposed RTC § 50304(d).

[27] Proposed RTC § 50304(f).

[28] Proposed RTC § 50304(g).

[29] Proposed RTC § 50304(h).

[30] Proposed RTC §§ 50304(e) & 50304(i).

[31] Proposed RTC § 50304(l).

Categories
News

The 2026 Billionaire Tax Act Part One:

Introduction, Structure, and Applicability

Introduction

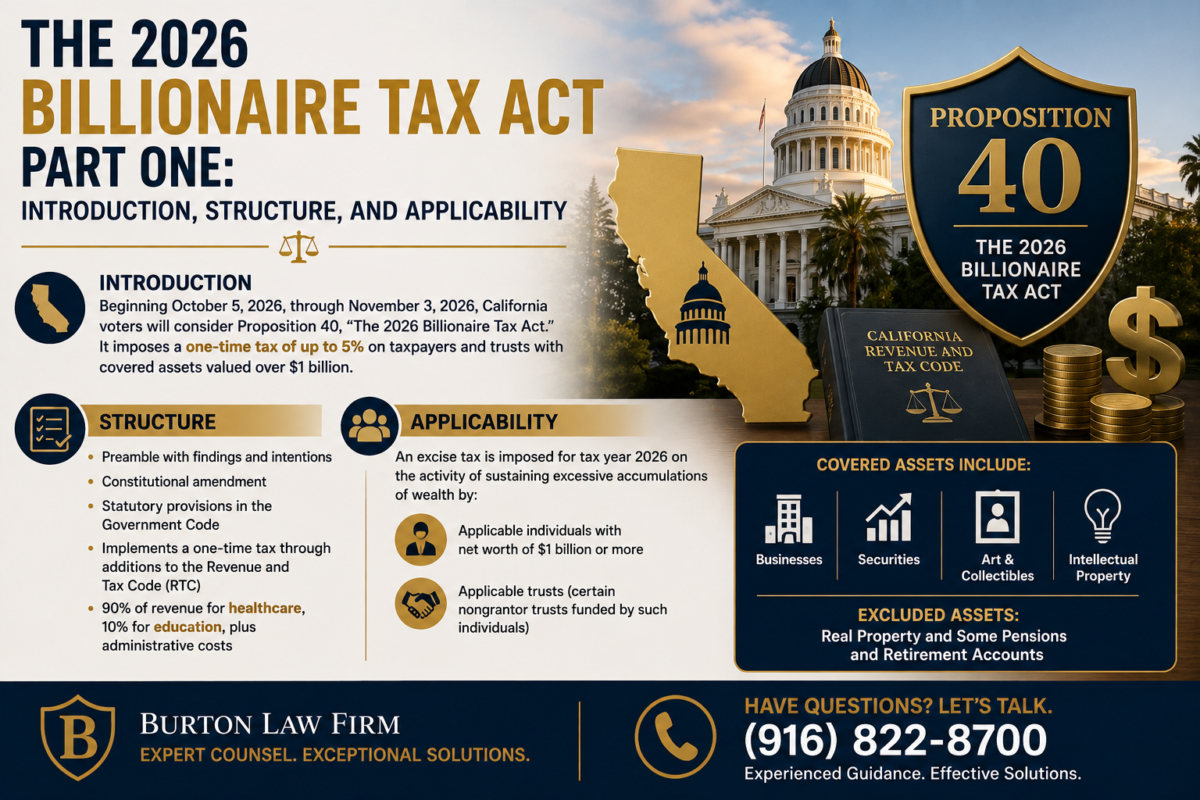
Beginning on October 5, 2026, and ending on November 3, 2026, California voters will consider Proposition 40, “The 2026 Billionaire Tax Act.” As part of Proposition 40’s official summary, prepared by California’s Attorney General, states: It “[i]mposes one-time tax of up to 5% on taxpayers and trusts with covered assets valued over $1 billion; covered assets include businesses, securities, art, collectibles, and intellectual property, but exclude real property and some pensions and retirement accounts.” However, there are many nuances varying from the graduated rate to the definition of “net worth” that will be comprehensively covered in this new series of posts in the coming weeks.[1]

Structure

Proposition 40 is divided into a preamble listing its findings and intentions, a constitutional amendment, and several statutory sections. The preamble explains that Proposition 40 is necessary (according to its creators) to adjust to decreases in federal public health funding. More fundamentally, Proposition 40 cites distributional justice concerns. For example, it claims that: “California has around 200 billionaires who collectively possess an astonishing $2 trillion in wealth. These billionaires pay less than 1.5% of their total wealth in annual taxes, including federal, state, and local taxes, according to leading economic estimates-a small fraction of what ordinary Californians pay.”[2]

The constitutional amendment “authorizes and enables a one-time tax on the accumulated wealth of California billionaires.”[3] Yet, most of the constitutional amendment governs the spending of the 2026 Billionaire Tax Act’s revenue and is followed by implementing sections in the Government Code. Ninety percent of the total revenue (anticipated by supporters to be $100 billion) would be devoted to healthcare, with the rest for public education, apart from yearly administrative expenses for the Franchise Tax Board in enforcing the “2026 Billionaire Tax Act.”[4] The bulk of Proposition 40 consists of additions to the Revenue and Tax Code of California (“RTC”) to implement the wealth tax by the Franchise Tax Board (“FTB”). 

Applicability

“An excise tax is imposed for tax year 2026 on the activity of sustaining excessive accumulations of wealth by applicable individuals with net worth of $1 billion dollars ($1,000,000,000) or more, and on applicable trusts.”[5] A 2026 Billionaire Tax Act taxpayer would be either an “applicable individual” with a net worth of at least $1 billion or an “applicable trust.” The term “applicable trust” has a more complex definition, but it is intended to encompass nongrantor trusts that received contributions by an “applicable individual” with a net worth of at least $1 billion.

Applicable Individual

An “‘[a]pplicable individual’ means, for the 2026 tax year, any individual who is a resident of this State, within the meaning of Sections 17014 and 17015.5, as of the tax obligation date.”[6] The tax obligation date is January 1, 2026. Therefore, an individual meeting the wealth threshold is liable for the tax if they were considered a resident of California under the normal state income tax for any part of the year as of January 1, 2026. “[A] married couple shall be considered as one individual” for the purposes of the tax liability and the filing requirement.[7]

Applicable Trust

An “applicable trust” is defined as a “trust” for which all of the following are true:[8]

  • The trust is not a grantor trust for the purposes of the income tax.
  • The trust is not a tax-exempt trust under IRC § 501.
  • An “applicable individual” transferred property to the trust, wherein all of the following are true.
    • The applicable individual is “still living.”
      • Proposition 40 does not specify when the applicable individual must be alive.
    • The applicable individual has a “net worth” of at least $1 billion.
      • Proposition 40 does not specify when the net worth threshold must be met for these purposes.

The transfer by such an applicable individual is deemed accomplished if performed by “any entity that would constitute a related person with respect to such individual.”[9] Proposition incorporates Internal Revenue Code §§ 267 and 318 (“as of January 1, 2026”) for the definition of a related person.[10] This generally includes close family members and controlled entities. However, a “related person” also includes “any other person so specified by regulations adopted by the Board.”[11] “If more than one individual has transferred property to such trust,” the trust portion which is “treated as an applicable trust” is the portion proportionate to such an applicable individual’s transfer (including through a related entity), “holds to the total value of assets transferred to the trust.”[12] Thus, if an applicable individual (still living with a billion dollars) contributes to a trust alongside a nonapplicable individual in equal proportions, 50% of the trust would be deemed the applicable trust. This definition is modified by two different elections:

  • “[A]ny trust may elect to be an applicable trust by notifying the Board of such election by any method the Board may designate.”[13]
  • “An individual with net worth of $1 billion ($1,000,000,000) or more who has transferred property to an applicable trust may elect to treat such trust as part of the net worth of such individual by notifying the Board of such election by any method the Board may designate.”[14] 

Therefore, a trust can elect to be an applicable trust, and an individual 2026 Billionaire Tax Act taxpayer may elect to incorporate the trust’s assets into their own net worth.

            Please visit next week for more information about Proposition 40 in this new weekly series of posts.


[1] Nothing should be construed as support of or opposition to Proposition 40 by the author or The Burton Law Firm. 

[2] Proposition 40, § 2(r).

[3] Proposed California Constitution, Art. XIII, § 37(a).

[4] Proposed California Constitution, Art. XIII, § 37(d).

[5] Proposed RTC § 50301(a).

[6] Proposed RTC § 50308(a).

[7] Proposed RTC § 50301(a).

[8] Proposed RTC § 50308(b).

[9] Id.

[10] Proposed RTC § 50308(k).

[11] Id.

[12] Proposed RTC § 50308(b).

[13] Id.

[14] Id.

Categories
News

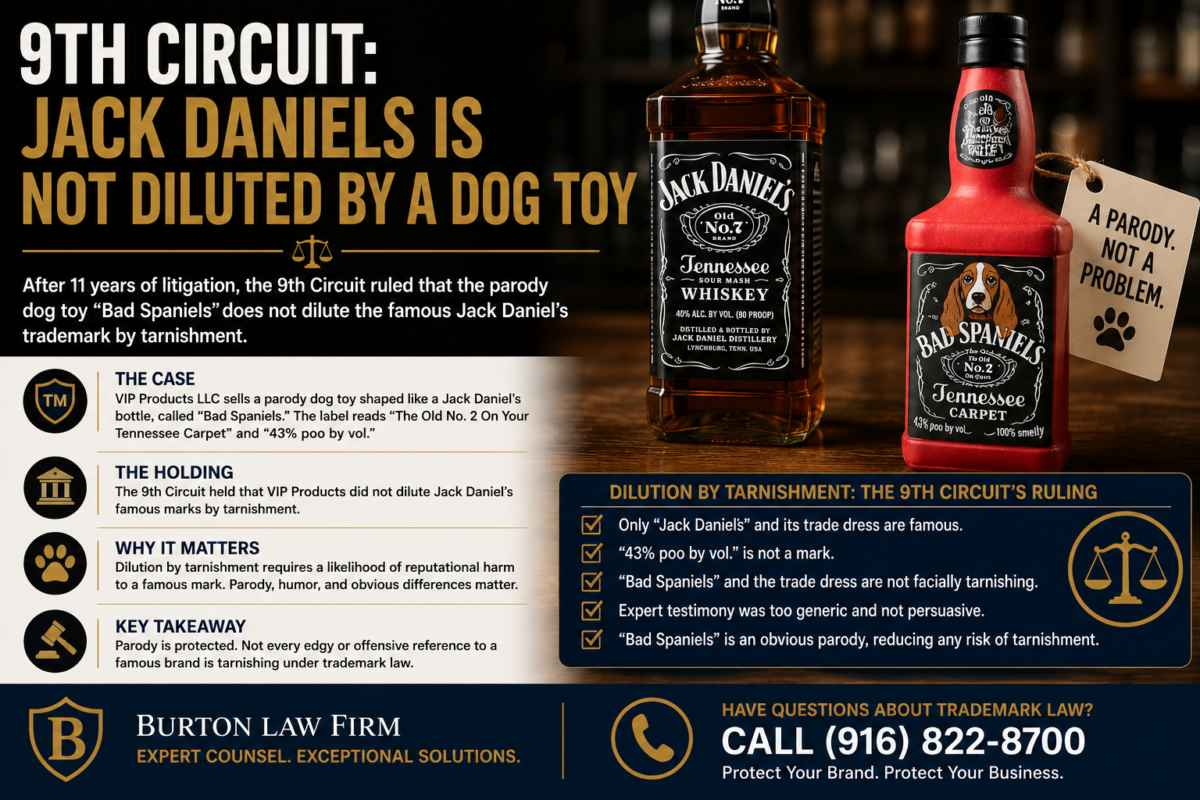
9th Circuit: Jack Daniels is not Diluted by a Dog Toy

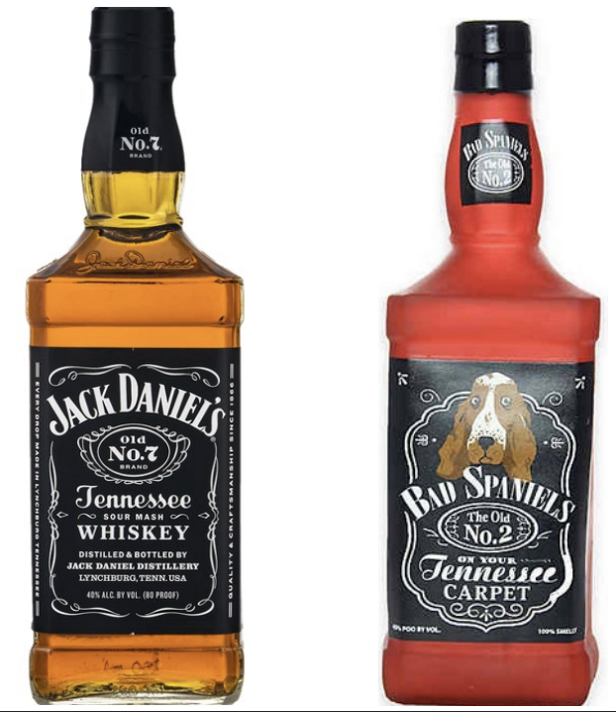
After 11 years, the litigation between Jack Daniel’s Properties, Inc. and VIP Products LLC regarding a dog toy’s resemblance to liquor ended in VIP Products LLC’s favor. VIP Products LLC sells dog toys parodying Jack Daniel’s beverage. The toys are similarly shaped (but of different materials) and are called “Bad Spaniels,” with a descriptive label of “The Old No. 2 On Your Tennessee Carpet” instead of “Old No. 7 Brand Tennessee Sour Mash Whiskey.” “The small print at the bottom substitutes ‘43% poo by vol.’ and ‘100% smelly’ for ‘40% alc. by vol. (80 proof).’”[1]

 The Lanham Act protects trademarks from confusion and dilution. This case already reached the Supreme Court in 2023, which instructed the 9th Circuit on the proper standard.[2] In turn, the 9th Circuit remanded the case to the district court. The district court ruled that the liquor cannot likely be confused with the dog toy, so the dog toy does not infringe on the liquor’s trademark. However, VIP Products LLC was held liable for dilution by tarnishment. VIP Products LLC appealed the dilution by tarnishment judgment, but Jack Daniel’s Properties, Inc. (JDPI) did not appeal the infringement ruling.

“Dilution by tarnishment means an association arising from the similarity between a mark or trade name and a famous mark that harms the reputation of the famous mark.”[3] Consumer confusion is irrelevant. However, this action “protects only famous marks from dilution and only where a similar junior mark is likely to tarnish its reputation because of the marks’ association.”[4] Here, the Jack Daniel’s liquor was compared with canine feces. Yet, “[t]he only marks JDPI proved famous are ‘Jack Daniel’s’ and its registered trade dress.”[5] “[A] mark is famous if it is widely recognized by the general consuming public of the United States as a designation of source of the goods or services of the mark’s owner.”[6] To qualify, “the mark must be a ‘household name.’”[7] The most objectionable detail, “43% poo by vol.” simply “does not mimic or reproduce any famous, similar mark. The equivalent language on JDPI’s product, ‘40% ALC. BY VOL. (80 PROOF),’ is not a mark.”[8] Therefore, “the only similar junior marks for our review are ‘Bad Spaniels’ and the dog toy’s trade dress.”[9] The “trade dress” is “the overall appearance of a product and its packaging.”[10] Neither the trade dress nor the name is facially tarnishing. “If a junior mark is not facially tarnishing, the context in which it is used may become relevant to the tarnishment analysis, depending on the facts of the case. For example, using a famous mark or a closely related depiction on a product that is of poor quality or pornographic or illegal may be tarnishing if the other requisites are met.”[11]

Here, the district court and JDPI relied on an expert witness to conclude that there is tarnishment. The 9th Circuit rejected that testimony as “generic.”[12] Although Dr. Simonson stated that aversion usually occurs when excrement is associated with a beverage, he did “not show that any association between either ‘Bad Spaniels’ and ‘Jack Daniel’s’ or between the products’ similar trade dress is likely to damage the reputation of JDPI’s famous marks.”[13] The studies he cited were not specific to this case, and “Bad Spaniels is a parodic dog toy not intended for human consumption.”[14] Finally, “Bad Spaniels is an obvious parody.”[15] Although not dispositive per se, “clarity of VIP’s parodic intent impacts the likelihood that JDPI’s famous marks are harmed by association with VIP’s product.”[16] This is so because “no matter how similar to its famous counterpart, a parodic junior mark ultimately relies upon a difference from the original mark, presumably a humorous difference, in order to produce its desired effect.”[17] Therefore, the 9th Circuit ordered the district court to vacate its permanent injunction and enter judgment in favor of VIP.

If you are considering registering a trademark or if you have any trademark questions, please call 916-822-8700 or email info@lawburton.com.

[1] Jack Daniel’s Props. v. VIP Prods. LLC, 599 U.S. 140, 150 (2023).

[2] Specifically, the Rogers test does not apply when “the use is at least in part for source identification—when the defendant may be trading on the good will of the trademark owner to market its own goods.” Jack Daniel’s Props. v. VIP Prods. LLC, 599 U.S. 140, 156 (2023)(omitting internal quotation marks). The “Rogers test requires dismissal of an infringement claim at the outset unless the complainant can show one of two things: that the challenged use of a mark has no artistic relevance to the underlying work or that it explicitly misleads as to the source or the content of the work.” Id. at 151(omitting internal quotation marks).

[3] VIP Prods., Ltd. Liab. Co. v. United States, No. 25-2027, 2026 U.S. App. LEXIS 23257, at *12 (9th Cir. Aug. 4, 2026)(omitting internal quotation marks).

[4] Id. at *13-14.

[5] Id. at *14.

[6] Id. at *16.

[7] Id.

[8] Id. at *14 fn.3.

[9] Id. at *14.

[10] Id. at *12.

[11] Id. at *20.

[12] Id. at *23.

[13] Id. at *23-24.

[14] Id. at *24(emphasis in original).

[15] Id. at *26.

[16] Id. at *27(omitting internal brackets and quotation marks).

[17] Id. at *28(omitting internal quotation mark).